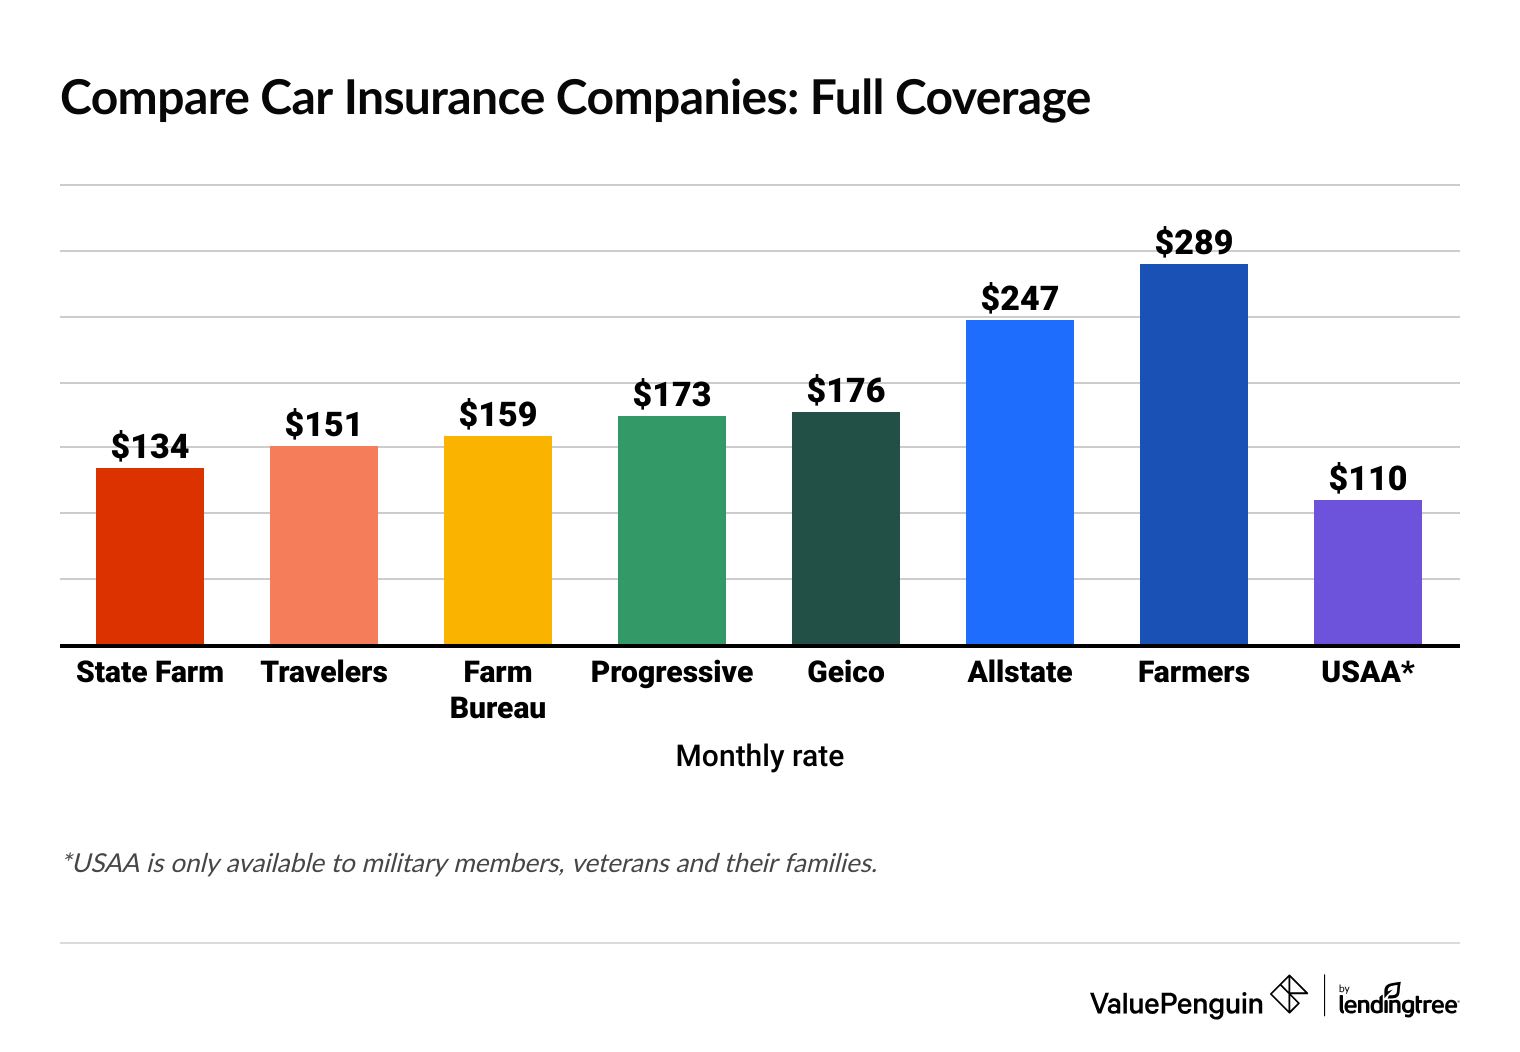
Auto insurance quotes and comparison refer to the process of obtaining price estimates from multiple insurers and evaluating the coverage details side by side. For example, a driver in Ohio might receive a $1,200 quote from State Farm, a $1,050 quote from GEICO, and a $1,300 quote from Allstate, then compare deductibles, liability limits, and customer service ratings before deciding.
This practice holds significant importance because it empowers motorists to secure affordable premiums while maintaining adequate protection against accidents, theft, and liability. Historically, the rise of online aggregators in the early 2000s transformed a once‑paper‑driven task into a quick, data‑rich experience, reducing information asymmetry between insurers and consumers.
The following sections explore pricing dynamics, coverage nuances, digital tools, common pitfalls, legal considerations, and future trends, providing a comprehensive roadmap for anyone seeking the best auto insurance quotes and comparison outcomes.
1. Pricing Dynamics
- Risk Scoring
Insurers assign a risk score based on driving record, vehicle type, and location. A 30‑year‑old with a clean record driving a compact sedan in suburban Texas may receive a lower score, resulting in a reduced premium. Understanding this score helps target discounts.
- Geographic Factors
Urban areas with higher accident rates often generate higher quotes. For instance, a driver in Manhattan might see a $1,800 estimate versus a $1,200 estimate for a similar driver in rural Iowa. Adjusting mileage or selecting a lower‑risk zip code can influence rates.
- Age and Experience
Young drivers under 25 typically face steep premiums due to statistical risk. A 22‑year‑old driver may pay $2,400 annually, while a 45‑year‑old with ten years of accident‑free driving might pay $1,100. Bundling policies can mitigate age‑related costs.
Pricing also reflects seasonal promotions and market competition. When multiple carriers vie for market share, temporary discounts may appear, prompting savvy shoppers to time their quote requests strategically.
Conversely, price‑only focus can overlook essential coverage elements, leading to under‑insuring. Balancing cost with comprehensive protection remains a core objective of effective comparison.
2. Coverage Nuances
Liability limits, collision deductibles, and comprehensive add‑ons constitute the core of any auto policy. Selecting a $100,000/$300,000 bodily injury limit versus a $50,000/$100,000 limit can double the premium but significantly increase financial protection after a severe crash.
Collision coverage reimburses repair costs after an accident, while comprehensive covers non‑collision events such as theft or natural disasters. A driver in Florida, prone to hurricanes, may prioritize comprehensive coverage despite a modest premium increase.
Additional endorsements—like roadside assistance, rental reimbursement, or gap insurance—tailor policies to individual needs. Including these options during the quote phase ensures transparent cost assessment.
3. Digital Comparison Tools
- Aggregator Platforms
Websites such as NerdWallet, The Zebra, and Compare.com pull data from dozens of carriers, presenting side‑by‑side tables. A user entering zip code 90210 receives instant visual comparisons, expediting decision‑making.
- Mobile Apps
Apps from insurers like Progressive and Liberty Mutual allow real‑time quote adjustments based on driving behavior captured via telematics. A driver who consistently maintains safe speeds may see a 10% discount reflected instantly.
- AI‑Powered Engines
Emerging AI tools analyze personal data, claim history, and market trends to suggest optimal coverage levels. While still evolving, these engines can highlight hidden savings opportunities.
Despite convenience, digital tools require careful scrutiny of data privacy policies. Ensuring that personal information is encrypted and not sold to third parties protects against identity theft.
4. Common Mistakes to Avoid
One frequent error involves selecting the lowest premium without reviewing deductible amounts. A $900 annual premium paired with a $2,000 deductible may cost more out‑of‑pocket after a minor accident than a $1,200 premium with a $500 deductible.
Another pitfall is neglecting to update policy information after life changes—such as moving, adding a teen driver, or purchasing a new vehicle. Failure to reflect these changes can invalidate coverage or trigger rate increases.
Lastly, relying solely on online reviews without confirming licensing and financial stability can expose drivers to insolvent carriers. Checking ratings from A.M. Best or Moody’s adds an extra layer of security.
5. Legal and Regulatory Landscape
State‑mandated minimum liability limits vary widely; California requires $15,000/$30,000/$5,000, while Michigan historically demanded unlimited personal injury protection (now reduced). Understanding local statutes ensures compliance and avoids penalties.
Recent federal initiatives encourage the use of usage‑based insurance (UBI) by standardizing data collection methods. Drivers participating in UBI programs may qualify for discounts up to 30%, but must consent to continuous monitoring.
Regulators also enforce transparent quote disclosures, mandating that insurers present total cost of ownership, including fees and taxes, within a clear format. Scrutinizing these disclosures prevents hidden charges.
6. Future Trends in Auto Insurance
Autonomous vehicle technology promises to reshape risk assessment. As self‑driving cars reduce human error, insurers anticipate lower premiums for fully autonomous fleets, while offering new liability models that shift responsibility from driver to manufacturer.
Blockchain‑based smart contracts are emerging as a method to automate claims verification, reducing processing time from weeks to minutes. Early adopters report higher customer satisfaction and lower administrative costs.
Climate change intensifies the need for robust comprehensive coverage in flood‑prone regions. Insurers are adjusting underwriting criteria to factor in climate risk scores, influencing quote calculations.
Frequently Asked Questions
Question 1: How many quotes should be obtained before deciding?
Gathering at least three to five quotes provides a balanced view of market rates, allowing identification of outliers and ensuring that the chosen policy reflects both price competitiveness and coverage adequacy.
Question 2: Do lower premiums always mean poorer coverage?
Not necessarily; some insurers achieve lower rates through efficient operations or targeted discounts. However, a thorough comparison of deductibles, limits, and exclusions is essential to confirm that reduced cost does not compromise essential protection.
Question 3: What role does credit score play in auto insurance quotes?
Many states permit insurers to factor credit-based insurance scores into premium calculations. A higher credit score often correlates with lower risk perception, resulting in reduced quotes, whereas lower scores may increase rates.
Question 4: Can bundling home and auto policies lower the quote?
Bundling typically yields multi‑policy discounts ranging from 5% to 15%. Insurers reward combined risk exposure with reduced premiums, provided that coverage needs for each line are adequately met.
Question 5: How often should auto insurance quotes be refreshed?
Refreshing quotes annually, or after major life events such as moving, purchasing a new vehicle, or adding a driver, ensures that the policy remains competitive and aligned with current risk factors.
Question 6: Are usage‑based insurance programs worth the privacy trade‑off?
For disciplined drivers who maintain safe habits, usage‑based programs can deliver 10%–30% discounts. Weighing potential savings against continuous data collection is a personal decision that hinges on comfort with telemetry monitoring.
Tips for Smart Auto Insurance Quotes and Comparison
Tip 1: Verify licensing. Confirm that each insurer holds a valid state license to avoid unlicensed entities.
Tip 2: Align coverage with vehicle value. Match comprehensive limits to the car’s market price to prevent over‑insuring.
Tip 3: Review deductible impact. Calculate potential out‑of‑pocket costs for different deductible levels before selecting the lowest premium.
Tip 4: Leverage multi‑policy discounts. Combine home, renters, or umbrella policies with auto insurance for bundled savings.
Tip 5: Update personal information promptly. Reflect address changes, new drivers, or vehicle upgrades immediately to maintain accurate pricing.
Tip 6: Examine insurer’s financial strength. Check ratings from A.M. Best or Moody’s to ensure claim‑paying ability.
Tip 7: Utilize telematics responsibly. Participate in usage‑based programs only if driving habits consistently qualify for discounts.
Tip 8: Re‑quote after major life events. Reassess premiums after moving, marriage, or purchasing a new car to capture fresh savings opportunities.
Conclusion
Understanding pricing dynamics, coverage nuances, digital tools, common pitfalls, regulatory frameworks, and emerging trends equips motorists to navigate the complex landscape of auto insurance quotes and comparison. By applying systematic analysis and leveraging available resources, optimal protection can be secured at a competitive price.
Future advancements such as autonomous driving and blockchain will further transform how quotes are generated and compared, promising even greater transparency and efficiency for the informed driver.

