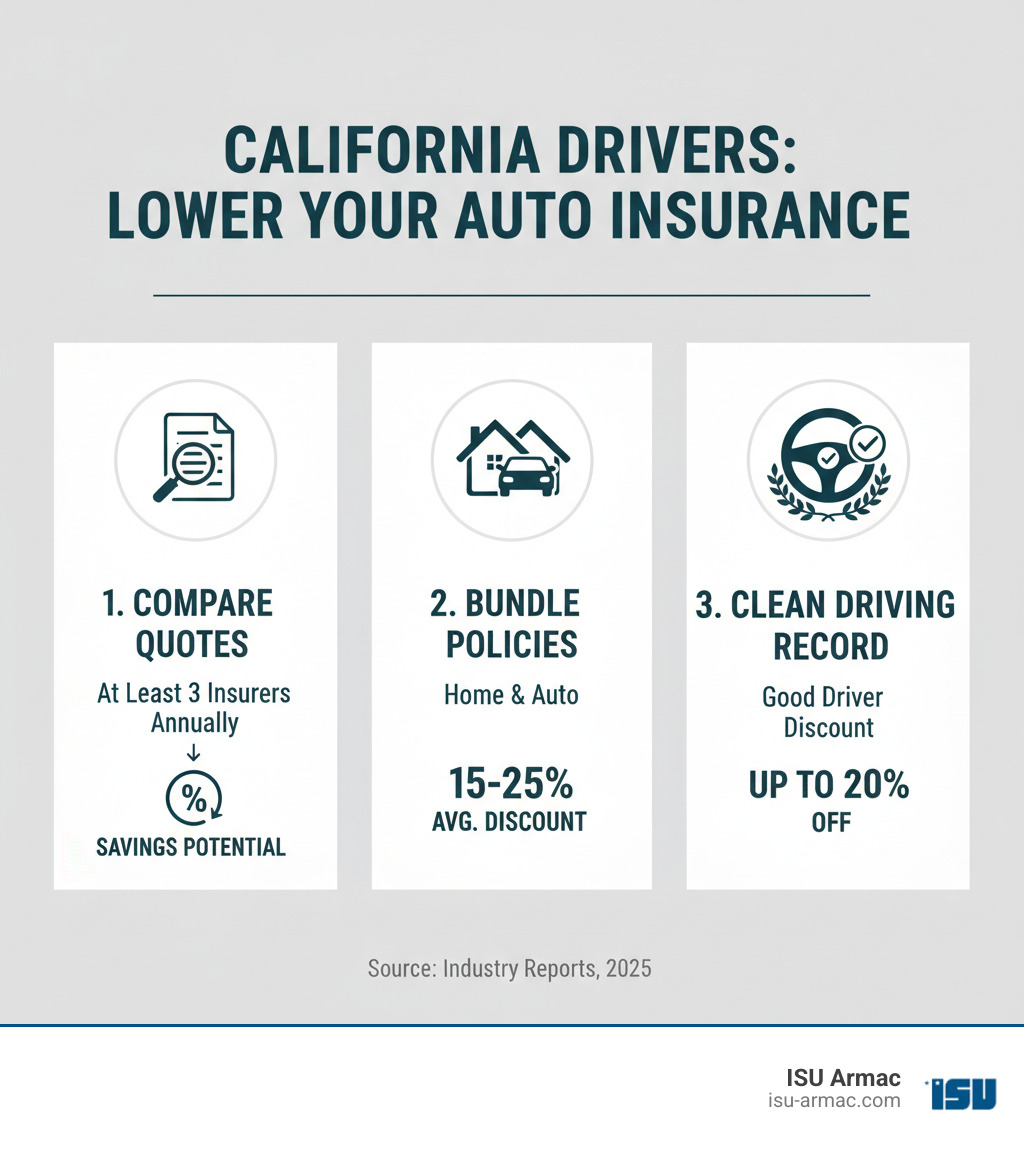
An **auto insurance quote CA** represents a personalized estimate of premium costs, coverage limits, and deductibles for a driver in California, tailored to their vehicle, driving history, and location. For example, a 30-year-old driver in Los Angeles with a clean record and a 2020 Toyota Camry might receive a quote ranging from **$1,200 to $2,500 annually**, depending on the insurer and policy details. These quotes serve as the foundation for purchasing car insurance—balancing legal compliance (California mandates minimum liability coverage of 15/30/5) with financial protection against accidents, theft, or natural disasters like wildfires.
The importance of securing an accurate **auto insurance quote CA** cannot be overstated. California’s high traffic density, frequent natural disasters, and rising repair costs make insurance both a legal requirement and a critical safeguard. A well-researched quote can save drivers thousands over time, while a poorly chosen policy might leave them exposed to exorbitant out-of-pocket expenses. Historically, California’s insurance market has seen volatility—from the 1970s insurance crisis to recent rate hikes due to climate-related claims—highlighting the need for proactive comparison and negotiation.
This guide explores the key components of an **auto insurance quote CA**, from pricing dynamics to coverage nuances, and provides actionable strategies to optimize quotes. Whether navigating mandatory minimums, leveraging discounts, or comparing providers, understanding these elements ensures drivers secure the best possible protection without overpaying.
1. Pricing Dynamics in California
California’s auto insurance premiums are influenced by a mix of state regulations, local risk factors, and insurer-specific algorithms. Unlike no-fault states, California’s tort system allows claimants to sue at-fault drivers, increasing liability costs. Urban areas like Los Angeles and San Francisco see higher rates due to congestion and theft risks, while rural regions may offer lower quotes but could lack robust coverage options. For instance, a driver in San Diego might pay **$1,800 annually** for full coverage, while a similar policy in Fresno could cost **$1,400**—a difference driven by claim frequency and infrastructure costs.
Insurers also factor in vehicle type, age, and safety ratings. A Tesla Model 3 in California might qualify for lower collision rates due to advanced safety features, while a modified truck could incur higher premiums. Additionally, California’s Proposition 103 (1988) caps premium increases based on inflation and requires insurers to justify rate hikes, adding another layer of complexity to pricing.
2. Coverage Types and Their Impact
An **auto insurance quote CA** typically includes six core coverage types, each affecting the final premium. Understanding these helps drivers customize their policies to avoid overpaying for unnecessary protections.
- Liability Insurance: Mandatory in California, covering bodily injury and property damage to others in an at-fault accident. Minimum limits (15/30/5) may leave drivers underinsured; opting for higher limits (e.g., 100/300/50) adds ~$50–$100 annually but shields against lawsuits.
- Collision Coverage: Pays for damage to the policyholder’s vehicle after a crash, regardless of fault. A 2019 Honda Civic with this coverage might add **$300–$600 yearly**, but it’s essential for leased or financed cars.
- Comprehensive Coverage: Protects against non-collision events like theft, vandalism, or hail. In high-theft areas like Oakland, this can add **$200–$500 annually** but is often waived on older vehicles.
- Uninsured/Underinsured Motorist: Critical in California, where ~15% of drivers lack insurance. This covers medical bills if the at-fault party is uninsured, adding ~$100–$200 yearly.
- Medical Payments (MedPay): Covers medical expenses for the driver and passengers, regardless of fault. Often bundled with health insurance, it adds minimal cost but provides quick access to funds.
Excluding optional coverages like roadside assistance or rental reimbursement can reduce premiums by **10–20%**, but drivers must weigh the trade-offs. For example, skipping rental reimbursement might save **$20–$50 annually**, but a 3-day rental after an accident could cost **$300+**.
3. Discounts That Slash Your Quote
California insurers offer discounts that can lower an **auto insurance quote CA** by **20–50%**, but many drivers overlook them. Discounts are often stacked, meaning combining multiple can yield significant savings. For instance, a driver in Sacramento with a good credit score (700+), a safe vehicle (e.g., Subaru Outback), and a monitoring device might qualify for discounts totaling **$800 annually** on a $2,000 policy.
- Safe Driver Discounts: Insurers like GEICO and Progressive reward accident-free histories with **10–30% off**. A driver with 5+ years without claims could save **$400–$700 yearly**.
- Bundling Policies: Combining auto with home or renters insurance (e.g., with State Farm or Allstate) often grants **10–20% off**. A homeowner in San Jose bundling policies might reduce their auto quote by **$300 annually**.
- Low Mileage Discounts: Useful for remote workers or students, this discount applies if annual mileage is under **7,500 miles**. A commuter driving 5,000 miles/year could save **$150–$300**.
- Anti-Theft Device Discounts: Installing systems like LoJack or OnStar can cut premiums by **5–15%**. A theft-prone area like Long Beach sees higher savings here.
- Good Student Discounts: Full-time students with a B average or higher may qualify for **5–25% off**. A teen driver in Berkeley could save **$200–$500 annually** with this discount.
Discounts vary by insurer, so drivers should request a detailed breakdown during the quoting process. Some insurers, like Farmers, offer additional perks like **pay-per-mile programs** for low-mileage drivers, further reducing costs.
4. How Quotes Vary by Insurer
Not all **auto insurance quote CA** providers calculate risk the same way, leading to stark differences in premiums for identical drivers. For example, a 45-year-old in Anaheim with a 2018 Honda Accord might receive quotes ranging from **$1,300 (Liberty Mutual)** to **$2,100 (Allstate)**—a **$800 annual gap**. This variance stems from insurer underwriting models, claims payout histories, and regional market dominance.
Direct insurers (e.g., Progressive, GEICO) often undercut traditional agencies by cutting overhead costs, while regional providers (e.g., Mercury Insurance, based in California) may offer localized expertise and faster claims processing. Independent agents, like those at Farmers or State Farm, provide personalized service but may charge slightly higher premiums. Comparing at least **3–5 quotes** is critical; tools like the California Department of Insurance’s **Compare Rates** tool can streamline this process.
5. Credit Score’s Surprising Role
California law permits insurers to use credit-based insurance scores (not traditional FICO scores) to determine premiums, a practice that can increase quotes by **20–50%** for drivers with poor credit. A study by the Consumer Federation of America found that drivers with credit scores below 570 paid **$1,800 annually** on average, compared to **$1,200** for those with scores above 720. This disparity exists because statistical data links creditworthiness to claim frequency—drivers with financial stress may file more claims.
Improving a credit score by **50–100 points** can lower an **auto insurance quote CA** by **$300–$600 annually**. Steps include paying bills on time, reducing credit card balances, and avoiding new credit applications. For example, a driver in Fresno with a 600 credit score might see their quote drop from **$1,900 to $1,500** after 12 months of financial discipline. Insurers like American Family offer credit monitoring tools to help policyholders track and improve their scores.
6. Common Mistakes That Inflate Quotes
Even experienced drivers often make errors that unnecessarily inflate their **auto insurance quote CA**. These mistakes can add **$500–$1,500 annually** to premiums, money that could be saved with simple adjustments.
- Ignoring Usage-Based Programs: Telematics devices (e.g., Progressive’s Snapshot, State Farm’s Drive Safe & Save) track driving habits and reward safe behavior with **10–30% discounts**. A driver in San Francisco with aggressive braking habits might see their quote drop by **$400** after 6 months of improved driving.
- Underreporting Mileage: Insurers verify mileage through GPS or odometer checks. Underreporting to qualify for low-mileage discounts can void coverage or lead to claim denials. A driver claiming 5,000 miles but actually driving 12,000 could face **$500+ in unexpected costs**.
- Skipping the Annual Review: Life changes—marriage, moving, or buying a new car—can impact insurance needs. Failing to update an **auto insurance quote CA** after relocating from Los Angeles to a lower-risk area like Bakersfield could mean overpaying by **$300–$800 annually**.
- Choosing the Wrong Deductible: A high deductible (e.g., $2,000) lowers premiums but requires out-of-pocket payments after claims. A driver with a $500 deductible might pay **$1,500 annually**, while a $1,500 deductible could reduce that to **$1,100—but only if they can afford the higher upfront cost**.
- Not Comparing After Major Life Events: Events like divorce, retirement, or adding a teen driver can spike premiums. A retired driver in Palm Springs might qualify for senior discounts, reducing their quote by **$200–$400**, but insurers won’t adjust rates proactively.
Regularly auditing coverage and shopping for new quotes every **6–12 months** mitigates these pitfalls. Tools like **The Zebra** or **NerdWallet** automate comparisons, ensuring drivers never overpay.
7. How to Get the Best Quote
Securing the best **auto insurance quote CA** requires a strategic approach beyond entering basic details into an online form. Start by gathering accurate information: vehicle identification number (VIN), annual mileage, and driving history. Even small inaccuracies—like listing a vehicle as the primary driver when it’s not—can lead to claim denials or higher rates. For example, a driver in Oakland mistakenly listing themselves as the primary driver on a car they rarely use might face a **$200 annual premium increase** due to higher risk assumptions.
Timing also matters. Insurers often offer discounts for **new policies** or during **slow seasons** (e.g., winter months). Bundling with other policies, such as homeowners insurance with the same provider, can unlock additional savings. Additionally, requesting quotes from **direct insurers, independent agents, and captive agents** ensures a broad comparison. For instance, a driver in Sacramento might find the cheapest quote from **Esurance (direct)**, a balanced option from **State Farm (captive)**, and personalized service from a **local independent agent**—each fulfilling different needs.
8. Navigating California-Specific Risks
California’s unique risks—wildfires, earthquakes, and high repair costs—demand specialized coverage considerations. An **auto insurance quote CA** may not fully address these hazards, requiring supplemental policies. For example, wildfires in Napa Valley can total vehicles, yet standard comprehensive coverage may exclude smoke damage. Adding **optional wildfire coverage** (via endorsements) can add **$100–$300 annually** but is essential in high-risk zones.
Earthquake damage is another gap. While not typically covered under auto policies, insurers like **State Farm** offer separate earthquake endorsements. A driver in Los Angeles might pay **$50–$150 extra** for this protection, but the cost of repairing a car damaged in a 6.0 quake (potentially **$10,000+**) justifies the expense. Additionally, California’s high labor and parts costs mean collision claims often exceed national averages. Opting for **mechanical breakdown insurance** (e.g., from AAA or Allstate) can provide peace of mind for older vehicles, adding **$100–$200 annually**.
Frequently Asked Questions
Auto insurance quotes in California raise specific questions for drivers seeking clarity and savings.
Question 1: How often should I update my auto insurance quote CA?
An **auto insurance quote CA** should be reviewed **annually** or after major life changes—moving, marriage, adding a driver, or purchasing a new vehicle. Insurers adjust rates based on updated risk profiles, and failing to review can result in overpaying by **$300–$800 yearly**. Use tools like Policygenius to compare quotes every 6–12 months.
Question 2: Can I get a lower quote by increasing my deductible?
Yes, increasing the deductible (e.g., from $500 to $1,500) can lower premiums by **10–30%**, but only if the policyholder can afford higher out-of-pocket costs. For example, a driver in Fresno might save **$400 annually** by raising their deductible, but a $1,500 repair after an accident would require full payment upfront.
Question 3: Do electric vehicles (EVs) get cheaper auto insurance quotes in California?
EVs often qualify for **lower collision and comprehensive rates** due to advanced safety features and lower repair costs. A Tesla Model 3 in Los Angeles might receive a quote **10–20% cheaper** than a comparable gas-powered car, thanks to lower theft rates and cheaper parts. However, charging infrastructure risks (e.g., theft of charging cables) may require additional endorsements.
Question 4: What happens if I cancel my policy and get a new auto insurance quote CA?
Canceling a policy to switch insurers may result in a **rate increase** if the new quote is higher or if the driver has a gap in coverage. California law requires insurers to provide a **30-day grace period** for cancellations, and drivers should ensure the new policy is active before dropping the old one to avoid non-compliance penalties.
Question 5: Are there discounts for hybrid or eco-friendly vehicles?
Yes, insurers like **GEICO and Farmers** offer **green car discounts** of **5–15%** for hybrids or EVs, recognizing their lower accident and repair risks. A Toyota Prius in San Francisco might qualify for **$200–$500 in annual savings**, and some insurers also provide **carpool or low-emission discounts** for drivers using public transit.
Question 6: How does my driving record affect my auto insurance quote CA?
A clean driving record (no accidents or tickets in the past 3–5 years) can lower quotes by **20–40%**, while a DUI or multiple at-fault accidents may increase them by **100% or more**. For example, a driver in San Diego with a speeding ticket might see their quote rise from **$1,500 to $2,200 annually**, but completing a defensive driving course could mitigate this increase.
15 Proven Tips to Optimize Your Auto Insurance Quote CA
Securing the best **auto insurance quote CA** requires proactive steps beyond basic comparisons. Here are 15 actionable strategies to maximize savings and coverage.
Tip 1: Compare at least 5 insurers. Prices vary widely—GEICO might offer the lowest quote, while State Farm provides superior claims service. Use comparison tools like **NerdWallet** to streamline the process.
Tip 2: Ask about bundling discounts. Combining auto with home or renters insurance can save **10–20%**. For example, a homeowner in Orange County bundling with Allstate might reduce their auto quote by **$350 annually**.
Tip 3: Request a credit check review. Errors on credit reports can inflate quotes. Obtain a free report from **AnnualCreditReport.com** and dispute inaccuracies to potentially lower premiums by **$200–$500**.
Tip 4: Enroll in a usage-based program. Telematics tools like **Progressive’s Snapshot** track driving habits and reward safe behavior with **10–30% discounts**. A driver in Sacramento improving their braking habits could save **$400 yearly**.
Tip 5: Choose the right deductible. A higher deductible (e.g., $1,000) lowers premiums but requires larger out-of-pocket payments. Balance this with an emergency fund—aim for a deductible you can cover without financial strain.
Tip 6: Install anti-theft devices. Systems like **LoJack** or **OnStar** can reduce quotes by **5–15%**. In theft-prone areas like Long Beach, this discount can translate to **$200–$400 in annual savings**.
Tip 7: Pay annually if possible. Monthly payments often include **2–5% fees**. A driver paying $1,200 annually might pay **$1,300+ monthly**, costing **$60 extra yearly**. Opt for annual payments when feasible.
Tip 8: Maintain continuous coverage. Gaps in coverage can spike new quotes by **50–100%**. Even if switching insurers, ensure the new policy activates before canceling the old one to avoid penalties.
Tip 9: Explore pay-per-mile options. Programs like **Metromile** charge based on actual miles driven, ideal for low-mileage drivers. A commuter in Palo Alto driving 8,000 miles/year might save **$500–$800 annually** compared to traditional policies.
Tip 10: Ask about loyalty discounts. Some insurers (e.g., **American Family**) offer **5–10% discounts** after 3–5 years of continuous coverage. A driver in Riverside with 4 years of service might qualify for **$150 in savings**.
Tip 11: Review coverage after major purchases. Buying a new car or home? Update your **auto insurance quote CA** to reflect changes in asset value. A driver upgrading from a Honda Civic to a BMW 3 Series might need **$50,000 in collision coverage**, increasing premiums but protecting their investment.
Tip 12: Check for employer discounts. Some companies (e.g., **UPS, Wells Fargo**) partner with insurers to offer employee discounts of **5–15%**. Verify with HR—this passive savings could reduce quotes by **$200–$500 yearly**.
Tip 13: Opt for paperless billing. Insurers like **Liberty Mutual** offer **2–5% discounts** for electronic statements. A driver saving $30/month in paper costs could translate to **$360 annually** in lower premiums.
Tip 14: Negotiate after a claim. If a claim is denied unfairly, politely request a review. Insurers like **State Farm** may adjust decisions if presented with new evidence, potentially avoiding a **$500–$2,000 out-of-pocket expense**.
Tip 15: Reassess after life changes. Marriage, divorce, or adding a teen driver can shift risk profiles. A newlywed in San Diego combining policies might save **$400**, while a parent adding a 16-year-old could see quotes rise by **$1,500+**—requiring adjustments like higher deductibles or usage-based programs.
Conclusion
An **auto insurance quote CA** is more than a price—it’s a reflection of risk management, legal compliance, and financial strategy. By understanding coverage types, leveraging discounts, and comparing insurers, drivers can optimize their policies without sacrificing protection. California’s unique challenges, from wildfires to high repair costs, underscore the need for proactive adjustments, whether through supplemental endorsements or usage-based programs.
As insurance markets evolve, staying informed ensures drivers remain protected while maximizing savings. Regular reviews, strategic discounts, and informed comparisons will continue to be the cornerstones of securing the best **auto insurance quote CA**—both today and in the future.

