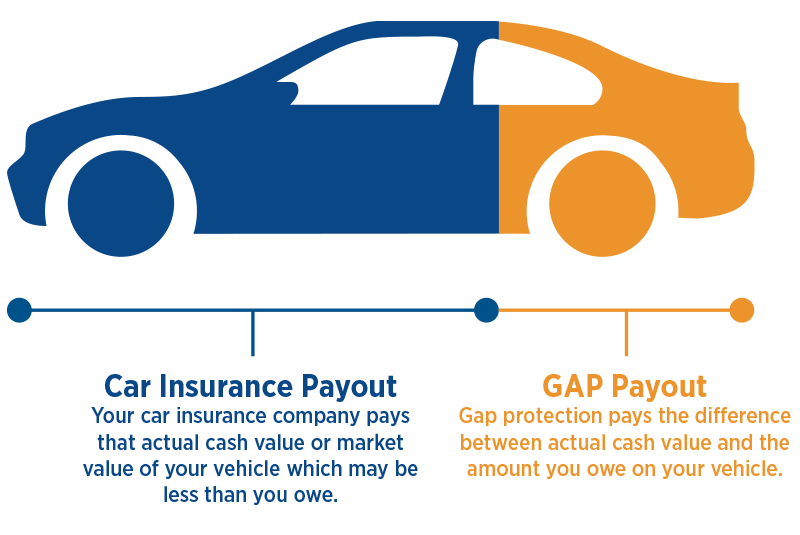
Auto insurance gap protection is a supplemental policy that covers the difference between a car’s actual cash value and the remaining loan or lease balance if the vehicle is totaled or stolen. For example, if a leased sedan is valued at $15,000 at the time of a total loss but the lease still requires $20,000, gap coverage would pay the $5,000 shortfall.
This coverage matters because depreciation can outpace loan repayment, leaving drivers financially exposed. Historically, gap protection emerged alongside the rise of long‑term financing and leasing options, providing a safety net for consumers who might otherwise face unexpected debt.
The following sections explore pricing dynamics, eligibility criteria, common misconceptions, claim processes, integration with primary insurance, and cost‑saving strategies, equipping readers with a comprehensive understanding of auto insurance gap protection.
1. Pricing Dynamics
- Premium Structure
Premiums are often a flat monthly fee or a percentage of the loan amount. For instance, a $30 monthly premium on a $20,000 loan yields a modest annual cost while shielding the borrower from a potential $10,000 gap.
- Risk Assessment
Insurers evaluate vehicle age, mileage, and loan term. A newer car with a short loan term typically incurs lower rates than an older vehicle financed over five years.
- Bundling Discounts
Many providers offer reduced rates when gap coverage is bundled with comprehensive auto insurance, creating savings of up to 15% compared to purchasing separately.
- State Regulations
Some states mandate disclosure of gap coverage costs, influencing price transparency and competition among carriers.
- Renewal Adjustments
Premiums may adjust at renewal based on changes in the loan balance or vehicle depreciation, requiring periodic review to maintain optimal coverage.
2. Eligibility Criteria
Eligibility typically hinges on the existence of an active auto loan or lease. Lenders may require proof of coverage before finalizing financing, especially for high‑value vehicles. Additionally, drivers must maintain a minimum level of primary liability or comprehensive coverage, as gap protection acts as a supplement rather than a standalone policy.
Some insurers impose credit score thresholds, reflecting perceived risk. For example, a borrower with a score above 700 may qualify for lower premiums, while lower scores could result in higher rates or limited options.
3. Common Misconceptions
- “It Replaces Comprehensive Insurance”
Gap coverage does not cover physical damage or liability; it only addresses the financial shortfall after a total loss.
- “All Loans Need Gap Coverage”
Drivers with short loan terms or high down payments may have minimal risk of a gap, making the coverage unnecessary.
- “It’s Always Expensive”
When bundled or purchased through the lender, the cost can be comparable to a modest monthly subscription, offering high value relative to potential loss.
- “Coverage Ends When Loan Ends”
Policy termination aligns with the loan payoff date, but early repayment may trigger a prorated refund of unused premium.
- “Only New Cars Qualify”
Used‑car leases and loans also qualify, provided the vehicle is under a financing agreement.
4. Claim Process
When a total loss occurs, the primary insurer first pays the vehicle’s actual cash value. The borrower then submits a gap claim, providing the loan statement, payoff amount, and the primary insurer’s settlement letter. The gap insurer reviews the documents and issues a payment to the lender, closing the financial gap.
Timely filing is crucial; most policies require claim submission within 30 days of loss notification. Delays can result in denied claims or reduced payouts.
5. Integration with Primary Insurance
Gap protection works hand‑in‑hand with comprehensive and collision coverage. While the primary policy addresses repair or replacement costs, gap coverage ensures that any remaining loan balance does not become the driver’s responsibility. Coordination of benefits prevents duplicate payments and streamlines the settlement.
Some insurers offer a single policy package that includes both primary and gap components, simplifying billing and reducing administrative overhead for the consumer.
6. Cost‑Saving Strategies
- Shop Around
Comparing quotes from multiple carriers can uncover lower premiums or better terms, especially for drivers with strong credit histories.
- Negotiate with Lender
Dealerships often add gap coverage at markup; negotiating removal or reduction can lower overall financing costs.
- Adjust Coverage Limits
Tailoring the gap amount to the exact loan balance avoids over‑insuring and reduces unnecessary expense.
- Utilize Employer Benefits
Some employers partner with insurers to offer discounted gap coverage as part of employee benefits.
- Review Annually
Reassessing the loan balance and vehicle depreciation each year ensures the coverage remains appropriate and cost‑effective.
Frequently Asked Questions
Quick answers to common queries about auto insurance gap protection.
Question 1: What exactly does gap coverage pay?
It pays the difference between the vehicle’s actual cash value, as determined by the primary insurer, and the remaining loan or lease balance, protecting the borrower from out‑of‑pocket debt after a total loss.
Question 2: Is gap protection required by law?
No federal mandate exists, but some states require lenders to disclose gap coverage options, and certain lease agreements may obligate the driver to maintain it.
Question 3: Can gap coverage be added after financing begins?
Yes, many insurers allow retroactive addition within a limited window, typically 30 days after the loan start date, though premiums may be higher.
Question 4: Does gap coverage cover theft?
If the vehicle is stolen and never recovered, the primary insurer pays the actual cash value, and gap coverage covers any remaining loan balance, similar to a total loss scenario.
Question 5: How does depreciation affect gap coverage?
Depreciation reduces the vehicle’s cash value faster than loan amortization, creating a potential gap; coverage accounts for this by paying the shortfall regardless of depreciation rate.
Question 6: What happens to the policy when the loan is paid off early?
The policy terminates on the payoff date, and any prepaid premium for the remaining term is typically refunded on a prorated basis.
Tips for Maximizing Gap Protection
Implement these 16 actionable steps to ensure optimal coverage and cost efficiency.
Tip 1: Verify loan balance. Regularly check the exact amount owed to align coverage limits accurately.
Tip 2: Compare carriers. Obtain at least three quotes to identify the best price‑performance ratio.
Tip 3: Bundle policies. Combine gap coverage with comprehensive auto insurance for discount opportunities.
Tip 4: Review credit impact. Improve credit score to qualify for lower premium tiers.
Tip 5: Ask about refunds. Inquire about prorated refunds if the loan is paid off ahead of schedule.
Tip 6: Confirm claim timeline. Know the 30‑day filing window to avoid denied payouts.
Tip 7: Check state regulations. Ensure compliance with local disclosure requirements and consumer protections.
Tip 8: Negotiate dealer add‑ons. Request removal of dealer‑marked‑up gap coverage during vehicle purchase.
Tip 9: Keep documentation. Store loan statements and primary insurance settlement letters for quick claim submission.
Tip 10: Update mileage. Report accurate mileage to insurers, as it influences depreciation calculations.
Tip 11: Assess lease terms. Short‑term leases may need less coverage; adjust accordingly.
Tip 12: Explore employer offers. Check if workplace benefits include discounted gap coverage.
Tip 13: Monitor policy renewals. Review changes in premium or coverage limits each year.
Tip 14: Understand exclusions. Read fine print for situations where gap coverage does not apply.
Tip 15: Use online portals. Manage policy details and claims digitally for faster processing.
Tip 16: Educate co‑borrowers. Ensure all parties on the loan understand the protection provided.
Conclusion
The key aspects of auto insurance gap protection—from pricing and eligibility to claim handling and cost‑saving tactics—form a cohesive safety net for financed or leased vehicles. By recognizing how depreciation creates financial exposure and leveraging strategic tips, drivers can maintain peace of mind without overspending.
Staying informed and periodically reviewing coverage ensures that gap protection continues to match evolving loan balances and market conditions, safeguarding against unexpected debt for years to come.

