Auto insurance for business vehicle is a specialized policy that protects cars, trucks, or vans used primarily for commercial purposes. For example, a delivery company that operates a fleet of refrigerated trucks must carry commercial auto insurance to cover accidents, cargo loss, and liability.
This type of coverage is crucial because business vehicles face higher mileage, heavier loads, and greater legal exposure than personal cars. Historically, insurers created separate commercial policies after the rise of corporate logistics in the mid‑20th century, recognizing the distinct risk profile and regulatory requirements.
The following sections explore pricing dynamics, coverage essentials, legal obligations, risk management, claim handling, and cost‑saving strategies, providing a comprehensive roadmap for fleet owners and small‑business operators.
1. Coverage Essentials
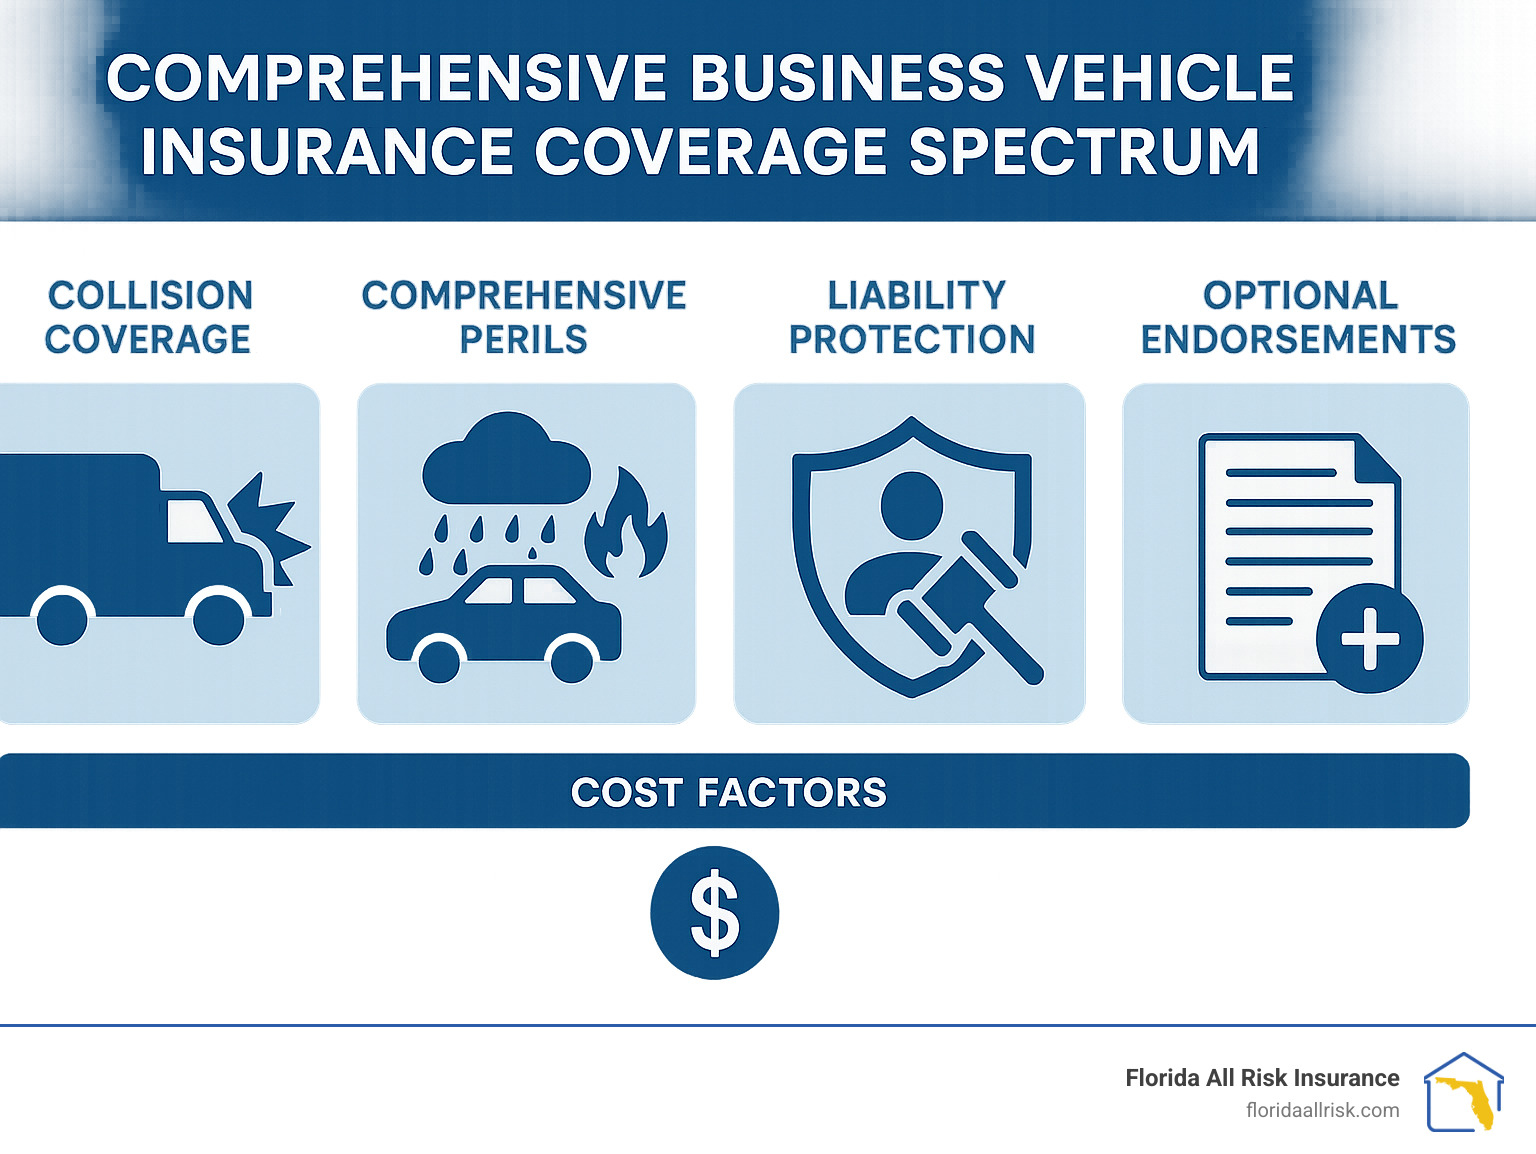
Understanding the core components of a commercial auto policy is the first step toward adequate protection. Liability coverage addresses bodily injury and property damage to third parties, while physical‑damage coverage (collision and comprehensive) repairs the insured vehicle. Uninsured/underinsured motorist coverage fills gaps when other drivers lack sufficient insurance.
Many policies also offer optional endorsements such as hired‑and‑non‑owned vehicle coverage, which protects employees driving personal cars for work, and cargo insurance for goods in transit.
- Liability Protection
Provides legal defense and settlement funds if the business vehicle causes injury or damage. A courier service faced a lawsuit after a delivery van struck a pedestrian; liability coverage covered the settlement and attorney fees.
- Physical‑Damage Coverage
Covers repair or replacement after a collision or theft. A construction firm’s dump truck was damaged in a site accident; comprehensive coverage paid for the rebuild, keeping the project on schedule.
- Hired‑and‑Non‑Owned Vehicles
Extends coverage to rented trucks or employee‑owned cars used for business. A sales rep using a personal sedan for client visits was protected when a rear‑end collision occurred.
2. Pricing Dynamics
Premiums for auto insurance for business vehicle depend on several risk factors. Vehicle type, usage patterns, driver history, and geographic location are primary determinants. Heavy‑duty trucks generally cost more than light‑duty vans due to higher repair costs and greater liability exposure.
Insurers also consider the business’s safety record, mileage, and any loss‑prevention programs. Implementing telematics or driver‑training can lower rates by demonstrating reduced risk.
- Vehicle Classification
Commercial trucks, especially those over 10,000 lbs, attract higher premiums. A logistics firm saved 12% by re‑evaluating its fleet and replacing older heavy trucks with newer, more efficient models.
- Driver Experience
Seasoned drivers with clean records reduce perceived risk. A courier company introduced a mentorship program, resulting in fewer accidents and a subsequent premium discount.
- Geographic Exposure
Urban areas with dense traffic increase claim frequency. A regional distributor shifted some deliveries to suburban routes, lowering its exposure and premium costs.
3. Legal and Regulatory Requirements
Each state mandates minimum liability limits for commercial vehicles, often higher than personal auto requirements. Federal regulations, such as the FMCSA’s rules for interstate trucking, add additional compliance layers, including mandatory insurance limits for cargo and bodily injury.
Failure to meet these standards can result in fines, license suspensions, or loss of business contracts. Companies that transport hazardous materials must also secure specialized coverage to meet EPA and DOT guidelines.
4. Risk Management Strategies
Proactive risk mitigation can significantly influence both safety outcomes and insurance costs. Regular vehicle maintenance, driver training, and route optimization reduce accident likelihood.
Technology tools like GPS tracking and dash‑cam systems provide real‑time monitoring, enabling quick corrective actions when risky behavior is detected.
- Scheduled Maintenance
Prevents mechanical failures that could lead to crashes. A delivery fleet that adhered to a strict service calendar reported a 20% drop in breakdown‑related incidents.
- Driver Training Programs
Focus on defensive driving and cargo securing techniques. After implementing a quarterly training module, a construction equipment rental firm saw fewer claim filings.
- Telematics Monitoring
Offers data on speed, harsh braking, and route deviation. An e‑commerce retailer used telematics insights to coach drivers, cutting mileage‑related claims by 15%.
5. Claims Process and Settlement
Efficient claims handling minimizes downtime and preserves cash flow. Prompt reporting, thorough documentation, and clear communication with the insurer are essential.
Many carriers now provide online portals for filing claims, uploading photos, and tracking status. Engaging a dedicated claims adjuster experienced with commercial fleets can expedite settlements and ensure appropriate coverage application.
6. Cost‑Saving Opportunities
Beyond basic risk mitigation, several tactics can lower premiums without sacrificing protection. Bundling multiple vehicles, leveraging group purchasing associations, and opting for higher deductibles are common approaches.
Reviewing policy limits annually ensures coverage aligns with current business needs, preventing over‑insuring and unnecessary expense.
- Policy Bundling
Combining commercial auto with general liability or property insurance often yields multi‑policy discounts. A boutique catering company saved 8% by bundling its fleet and premises coverage.
- Higher Deductibles
Choosing a larger deductible reduces the premium, provided the business can absorb the out‑of‑pocket cost. A landscaping firm increased its deductible from $500 to $2,000, resulting in a 10% premium reduction.
- Association Membership
Industry groups negotiate lower rates for members. A regional trucking association secured a favorable commercial auto program for its affiliates.
Frequently Asked Questions
Quick answers to common queries about commercial vehicle coverage.
Question 1: What distinguishes commercial auto insurance from personal auto policies?
Commercial policies address higher liability limits, business‑related use, and vehicle types such as trucks or vans, whereas personal policies focus on private, non‑business driving and lower exposure.
Question 2: Are employee‑owned cars covered when used for work?
Yes, through hired‑and‑non‑owned vehicle coverage, which extends liability protection to personal vehicles employed for business tasks, provided the policy includes this endorsement.
Question 3: How often should coverage be reviewed?
Annually or after any significant fleet change—such as adding or retiring vehicles, altering routes, or experiencing a claim—to ensure limits and premiums remain appropriate.
Question 4: Can telematics lower premiums?
Telematics data demonstrating safe driving habits often qualifies for usage‑based discounts, reducing premiums while encouraging better driver behavior.
Question 5: What is the minimum liability required?
State minimums vary, but commercial vehicles typically must meet higher thresholds than personal cars; for example, many states require at least $500,000 per incident for bodily injury.
Question 6: Does cargo insurance come automatically?
Cargo coverage is usually a separate endorsement; it must be added to protect goods in transit against loss, damage, or theft beyond the vehicle’s physical‑damage limits.
12 Practical Tips for Managing Auto Insurance for Business Vehicle
Implement these actions to optimize coverage and control costs.
Tip 1: Conduct a fleet audit. Identify each vehicle’s purpose, mileage, and risk profile to match appropriate coverage.
Tip 2: Compare multiple carriers. Use a broker or online marketplace to evaluate rates, discounts, and service quality.
Tip 3: Bundle policies. Combine commercial auto with general liability or property insurance for multi‑policy discounts.
Tip 4: Increase deductibles wisely. Choose a higher deductible only if cash flow can absorb potential out‑of‑pocket expenses.
Tip 5: Enroll in driver‑training programs. Regular education reduces accident frequency and may qualify for safety discounts.
Tip 6: Install telematics devices. Real‑time data on speed and braking supports usage‑based pricing.
Tip 7: Maintain vehicles meticulously. Scheduled service prevents breakdowns that could lead to claims.
Tip 8: Review coverage limits annually. Adjust limits to reflect current vehicle values and business exposure.
Tip 9: Add hired‑and‑non‑owned endorsement. Protect employee‑owned cars used for business tasks.
Tip 10: Secure cargo insurance. Protect goods in transit with a dedicated endorsement.
Tip 11: Leverage industry associations. Membership can unlock group discounts and risk‑management resources.
Tip 12: Document every incident. Detailed records streamline claims and improve future underwriting.
Conclusion
Auto insurance for business vehicle blends liability, physical‑damage, and optional coverages to safeguard commercial fleets against a range of risks. By understanding coverage essentials, pricing factors, legal mandates, and proactive risk‑management tactics, businesses can secure appropriate protection while controlling costs.
Staying vigilant—through regular policy reviews, technology adoption, and disciplined driver practices—ensures that insurance remains a strategic asset, supporting growth and resilience in an ever‑evolving transportation landscape.

