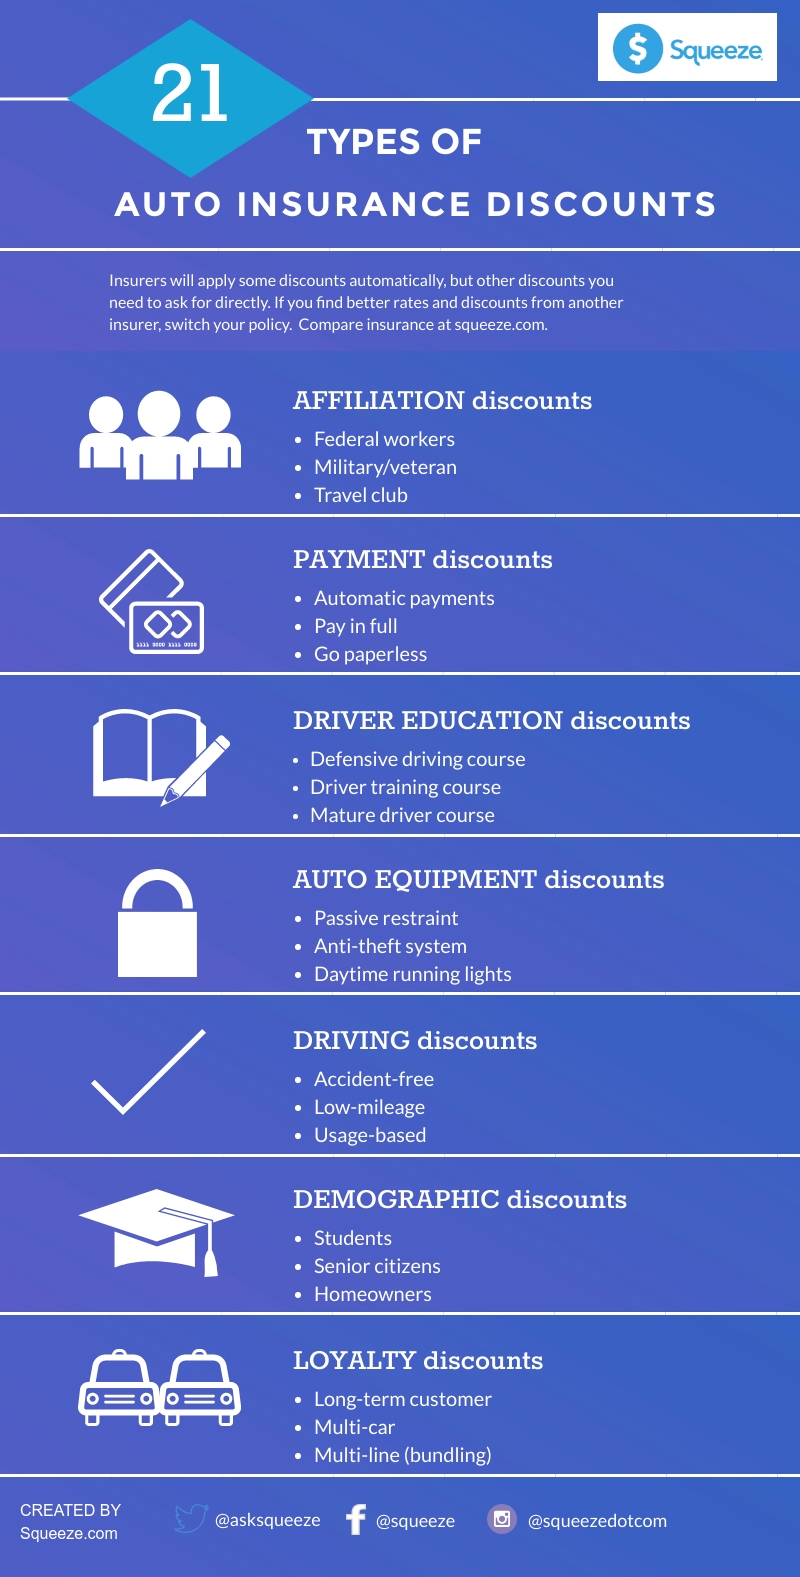
Auto insurance discounts to ask for can dramatically lower monthly premiums for responsible drivers. By identifying eligible programs, policyholders can reduce costs without sacrificing coverage quality. A typical example is a safe‑driver discount that rewards individuals with a clean record for three years.
Understanding these discounts matters because insurance represents a sizable household expense. Historically, insurers introduced incentive programs to attract low‑risk customers, creating a competitive market where discounts became a key differentiator. Modern carriers use data analytics and telematics to refine eligibility, making the landscape richer for savvy shoppers.
This article outlines the most common discount categories, explains qualification criteria, and offers actionable tips for maximizing savings. Readers will learn how to ask for each benefit, avoid common pitfalls, and leverage technology to secure the lowest possible rate.
1. Auto Insurance Discounts to Ask For
- Safe Driver
Insurers often reduce rates for drivers who have avoided accidents for a defined period, typically three years. For instance, State Farm offers up to a 15% discount for accident‑free records, encouraging continued cautious behavior.
- Multi‑Vehicle
Covering more than one vehicle on a single policy can yield a 10%‑20% reduction. A family with two cars saved $200 annually by consolidating coverage with Allstate.
- Good Student
Students maintaining a GPA of 3.0 or higher may receive a discount, recognizing lower risk associated with academic diligence. GEICO provides a 5% reduction for qualifying students.
- Low Mileage
Driving fewer than 7,500 miles per year signals reduced exposure, prompting discounts of up to 12%. Progressive’s low‑mileage program exemplifies this approach.
- Defensive Driving Course
Completing an accredited defensive driving course can shave 5%‑10% off premiums. In California, drivers who passed the DMV‑approved course saved $150 on their annual policy.
2. Eligibility Criteria
Eligibility hinges on objective factors such as age, driving history, vehicle type, and credit score. Younger drivers may qualify for good‑student discounts, while senior motorists often benefit from loyalty incentives. Insurers also evaluate claim frequency; a low claim count signals reduced risk, prompting favorable pricing adjustments.
Policyholders should request a detailed eligibility review before finalizing a quote. By presenting recent driving records and proof of vehicle safety features, carriers can verify qualification for multiple discounts simultaneously.
3. Bundling Strategies
- Home & Auto Bundle
Combining homeowners and auto policies with the same insurer frequently produces a 10%‑25% aggregate discount. Nationwide’s bundle saved a homeowner $350 per year.
- Renters & Auto Bundle
Tenants who also insure a vehicle can secure a 5%‑15% reduction. A renter in New York saved $120 by bundling with Liberty Mutual.
- Life & Auto Bundle
Life‑insurance providers often extend auto‑policy discounts to existing customers, rewarding long‑term relationships. MetLife offered a 7% discount to a policyholder who added auto coverage.
- Umbrella & Auto Bundle
Adding an umbrella policy can lower the underlying auto premium by up to 10%, as seen with Farmers Insurance.
- Business & Fleet Bundle
Small business owners who insure company vehicles alongside personal cars may receive a combined discount, exemplified by a Chicago firm saving $500 annually.
4. Loyalty and Retention Perks
Long‑term policyholders often enjoy incremental discounts for staying with the same insurer. These loyalty rewards may increase each renewal year, sometimes reaching 5% after five consecutive years. Some carriers also offer a “no‑claims‑bonus” that escalates with each claim‑free year, reinforcing risk‑averse behavior.
Retention incentives can include free roadside assistance or accident forgiveness, where the first accident does not affect the premium. Such benefits add value beyond pure price reductions.
5. Technology‑Driven Savings
- Telematics Programs
Devices that monitor driving habits enable insurers to price based on actual behavior. Progressive’s Snapshot program awarded a 12% discount to a driver who consistently obeyed speed limits.
- Usage‑Based Insurance
Pay‑as‑you‑drive models calculate premiums from mileage and time of day. Root Insurance granted a 20% discount to a commuter who drove primarily during off‑peak hours.
- Smartphone Apps
Apps that track acceleration, braking, and cornering provide data for personalized rates. Allstate’s Drivewise app helped a driver reduce premiums by 8% after six months of safe driving.
- Vehicle Safety Tech
Cars equipped with automatic emergency braking, lane‑keep assist, and blind‑spot monitoring qualify for equipment discounts, often ranging from 5% to 15%.
- Connected Car Discounts
Manufacturers that integrate telematics directly into the vehicle, such as Tesla’s safety suite, enable insurers to offer lower rates without separate hardware.
6. Professional and Membership Discounts
Employers, alumni associations, and professional societies frequently negotiate group rates with insurers. Teachers, military personnel, and members of the AAA organization can each expect a 5%‑12% discount, reflecting the perceived reliability of these groups.
Proof of affiliation, such as a badge number or membership card, is typically required. Negotiating through a union or corporate benefits portal often yields better terms than individual inquiries.
7. Seasonal and Situational Offers
Insurers may introduce limited‑time promotions tied to holidays, new vehicle purchases, or policy renewals. For example, a “Back‑to‑School” campaign in August offered a 10% discount to families adding a teen driver.
Situational discounts also arise after installing anti‑theft devices or after moving to a low‑crime neighborhood. Monitoring local insurer newsletters can reveal these fleeting opportunities.
Frequently Asked Questions
Quick answers to common queries about discount eligibility and application.
Question 1: Which discount provides the highest average savings?
Bundling home and auto policies typically yields the greatest aggregate reduction, often reaching 25% when combined with loyalty benefits.
Question 2: Can telematics discounts be applied without a device?
Some insurers accept smartphone‑based apps that replicate device functionality, allowing drivers to qualify for usage‑based savings without installing separate hardware.
Question 3: Are professional discounts available to freelancers?
Freelancers can often join professional associations that negotiate group rates; eligibility depends on proof of membership rather than employment status.
Question 4: How long does a good‑student discount last?
Most carriers apply the discount for each academic year a qualifying GPA is maintained, typically requiring annual verification through transcripts.
Question 5: Do low‑mileage discounts require a tracking device?
Insurers may request odometer readings at policy inception and renewal; some also accept annual mileage estimates submitted online.
Question 6: What is accident forgiveness?
Accident forgiveness prevents the first at‑fault claim from increasing the premium, encouraging policyholders to maintain coverage after an isolated incident.
Tips for Maximizing Discounts
Implement these strategies to secure the most favorable rate.
Tip 1: Review policy annually. Reassess coverage needs each renewal to eliminate unnecessary add‑ons.
Tip 2: Request a discount audit. Ask the insurer to evaluate all possible reductions based on current circumstances.
Tip 3: Combine safe‑driver and telematics programs. Layering incentives amplifies overall savings.
Tip 4: Keep a clean claims record. Fewer claims sustain eligibility for loyalty and no‑claims bonuses.
Tip 5: Maintain vehicle safety features. Up‑to‑date airbags and braking systems qualify for equipment discounts.
Tip 6: Leverage professional affiliations. Submit proof of membership to obtain group rates.
Tip 7: Explore multi‑policy bundles. Pair auto coverage with home, renters, or life insurance for combined discounts.
Tip 8: Use mileage tracking for low‑usage vehicles. Document annual miles to qualify for low‑mileage reductions.
Tip 9: Enroll in defensive‑driving courses. Certification often unlocks a 5%‑10% discount.
Tip 10: Update address after moving. Relocating to a lower‑risk area can automatically lower rates.
Tip 11: Install anti‑theft devices. Alarms and tracking systems signal reduced theft risk.
Tip 12: Ask about seasonal promotions. Holiday or back‑to‑school offers may provide temporary rate cuts.
Tip 13: Negotiate at renewal. Use competing quotes as leverage to secure better terms.
Tip 14: Review credit‑based pricing. Improving credit scores can indirectly lower insurance premiums.
Conclusion
The landscape of auto insurance discounts to ask for is extensive, ranging from traditional safe‑driver incentives to sophisticated telematics programs. By understanding eligibility criteria, bundling opportunities, and technology‑driven options, policyholders can strategically lower costs while maintaining robust coverage.
Continual vigilance, regular policy reviews, and proactive communication with insurers ensure that every applicable discount is captured, turning routine insurance expenses into a more manageable financial commitment.

