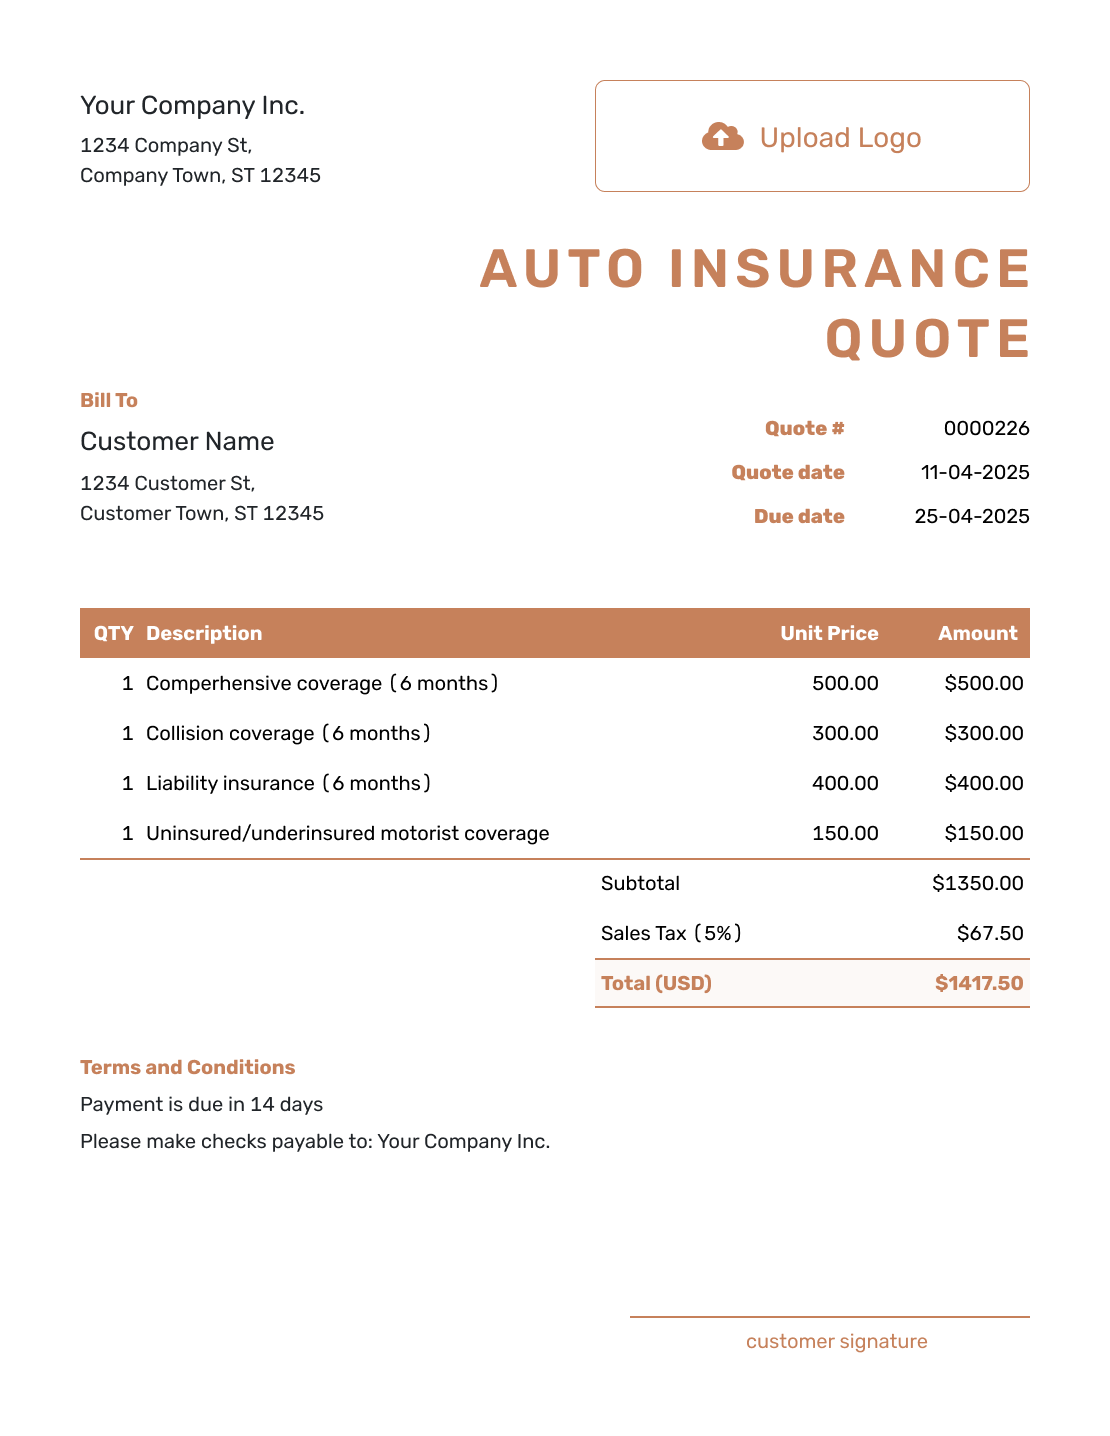
Auto insurance company quotes are estimates provided by insurers that outline the cost of covering a vehicle based on personal and driving factors. For instance, a 30‑year‑old driver in Ohio with a clean record might receive a quote of $1,150 annually from State Farm, reflecting risk assessments and policy options.
Understanding these quotes matters because they influence budgeting, risk management, and legal compliance. Historically, insurance pricing evolved from flat fees to sophisticated algorithms that consider mileage, credit scores, and vehicle safety features, offering drivers more tailored protection.
This article explores how quotes are generated, what to watch for, common pitfalls, and actionable steps to secure the most competitive rates, empowering informed decisions when shopping for auto coverage.
1. Pricing Dynamics
Insurance premiums stem from actuarial data, underwriting guidelines, and market competition. Companies balance risk exposure with profit goals, resulting in varied quote structures across providers.
- Risk Scoring
Insurers assign scores based on driving history, age, and location. A driver with multiple tickets may see a 20% surcharge, illustrating how personal risk directly inflates the quote.
- Vehicle Profile
Make, model, and safety ratings affect cost. A 2022 Subaru Outback, equipped with advanced driver‑assist systems, often earns lower quotes than a comparable sports car.
- Coverage Limits
Higher liability limits increase premiums. Selecting $100,000 bodily injury coverage instead of $50,000 can raise the quote by several hundred dollars annually.
- Discounts
Bundling home and auto policies, maintaining a clean driving record, or completing defensive‑driving courses can shave off 10‑15% from the quoted price.
- Regional Factors
Urban areas with higher accident rates typically generate higher quotes than rural regions, reflecting localized claim frequencies.
2. Data Collection Process
Gathering accurate personal and vehicle information is essential for reliable quotes. Errors such as misspelled names or incorrect VIN numbers can trigger inflated estimates or delayed policy issuance.
Most insurers now use online portals that pull credit scores, driving records, and DMV data instantly, streamlining the quote generation timeline from days to minutes.
3. Comparison Techniques
- Side‑by‑Side Grids
Creating a spreadsheet that lists premiums, deductibles, and coverage options enables quick visual comparison, highlighting value beyond price alone.
- Standardized Scenarios
Applying the same driver profile across multiple insurers ensures apples‑to‑apples comparisons, revealing hidden cost drivers such as fees or surcharges.
- Third‑Party Aggregators
Websites like NerdWallet or The Zebra aggregate quotes, but users should verify the final numbers directly with the insurer to account for potential updates.
- Policy Reviews
Reading the fine print uncovers exclusions or limited coverage areas that could affect overall cost effectiveness.
- Customer Service Ratings
Higher‑rated support teams can reduce claim settlement times, adding intangible value to the quoted price.
4. Common Mistakes to Avoid
Relying solely on the lowest headline price often leads to inadequate coverage. Skipping questions about mileage or intended use can produce quotes that later require costly adjustments.
Another frequent error is neglecting to update personal information after major life changes, such as moving or adding a teen driver, which can cause quote discrepancies.
5. Role of Discounts and Incentives
- Good Driver Discount
Maintaining a claim‑free record for three years can earn a 5% reduction, encouraging safe driving habits.
- Multi‑Car Discount
Insuring two or more vehicles under the same policy often yields a 10% savings per car, making family coverage more affordable.
- Telematics Programs
Devices like Progressive’s Snapshot track real‑time driving behavior; safe drivers may see premiums drop by up to 30%.
- Loyalty Credits
Long‑term customers sometimes receive renewal credits, though these can be offset by market rate increases.
- Affiliation Savings
Membership in professional organizations or alumni groups can unlock exclusive discount codes, adding modest but valuable savings.
\n
6. Impact of Credit Scores
In most states, insurers use credit-based insurance scores to predict risk. A strong credit history can lower quotes by 10‑20%, while poor scores may inflate them significantly.
Consumers should review credit reports annually, dispute inaccuracies, and consider credit‑building strategies before requesting new auto insurance company quotes.
7. Regulatory Considerations
State insurance departments enforce minimum liability limits and rate filing requirements, ensuring quotes remain within legal boundaries. Understanding local regulations helps avoid surprise surcharges.
Some states prohibit the use of gender or marital status in pricing; awareness of these rules can guide expectations when comparing quotes across state lines.
8. Timing and Market Trends
Quote amounts fluctuate with seasonal patterns, such as higher rates in winter due to increased accident risk. Monitoring market trends, like rising repair costs for electric vehicles, can inform optimal purchase timing.
Securing quotes during promotional periods, often at the start of the year, can capture temporary discounts before rates stabilize.
Frequently Asked Questions
Quick answers to common queries about auto insurance company quotes.
Question 1: How are auto insurance company quotes calculated?
Quotes are derived from actuarial data, personal risk factors, vehicle details, coverage limits, and regional statistics. Insurers input this information into proprietary algorithms, producing an estimate that reflects both risk exposure and profit targets.
Question 2: Do credit scores affect auto insurance quotes?
In most jurisdictions, credit-based insurance scores influence premium estimates. Higher credit scores generally lead to lower quotes, while lower scores can increase costs by up to 20 percent, depending on the insurer’s weighting system.
Question 3: Can bundling policies lower the quote?
Bundling auto with home or renters insurance often yields discounts ranging from 5 to 15 percent. Insurers reward multiple policies under one account, reducing administrative overhead and risk exposure.
Question 4: What is the best way to compare quotes?
Use a side‑by‑side spreadsheet that lists premiums, deductibles, coverage limits, and discounts. Ensure each quote reflects the same driver profile and vehicle information to achieve an apples‑to‑apples comparison.
Question 5: Are online quote tools reliable?
Online tools provide fast estimates and are generally accurate when data is entered correctly. However, final quotes may adjust after verification of driving records or additional underwriting review.
Question 6: How often should new quotes be requested?
Reviewing quotes annually, or after major life events such as moving or adding a driver, helps capture potential savings and ensures coverage remains aligned with current needs.
15 Actionable Tips for Better Auto Insurance Company Quotes
Tip 1: Verify personal details before requesting a quote to avoid unnecessary mark‑ups.
Tip 2: Use the same driver profile across all insurers for accurate side‑by‑side comparison.
Tip 3: Check for available discounts, such as safe driver, multi‑car, or telematics programs.
Tip 4: Review credit reports and improve scores prior to quote requests.
Tip 5: Consider higher deductibles if financially feasible to lower premium estimates.
Tip 6: Bundle home or renters insurance with auto coverage for bundled discounts.
Tip 7: Update policy information promptly after life changes like relocation or adding a teen driver.
Tip 8: Explore regional rate differences; moving to a lower‑risk area can reduce quotes.
Tip 9: Leverage telematics devices to demonstrate safe driving habits.
Tip 10: Compare not only price but also coverage limits, exclusions, and claim handling reputation.
Tip 11: Request quotes during off‑peak seasons when insurers may offer promotional rates.
Tip 12: Read fine print for hidden fees, such as policy‑administration charges.
Tip 13: Use reputable aggregator sites but confirm final numbers directly with the insurer.
Tip 14: Maintain a clean driving record to qualify for good‑driver discounts.
Tip 15: Re‑evaluate quotes annually to capture market‑driven savings and adjust coverage as needed.
Conclusion
Auto insurance company quotes encapsulate a complex blend of risk assessment, personal data, and market forces. By understanding pricing dynamics, data collection, discount opportunities, and regulatory influences, drivers can navigate the quote landscape with confidence.
Applying the outlined tips and comparison strategies positions consumers to secure optimal coverage at competitive rates, ensuring financial protection and peace of mind for years ahead.

