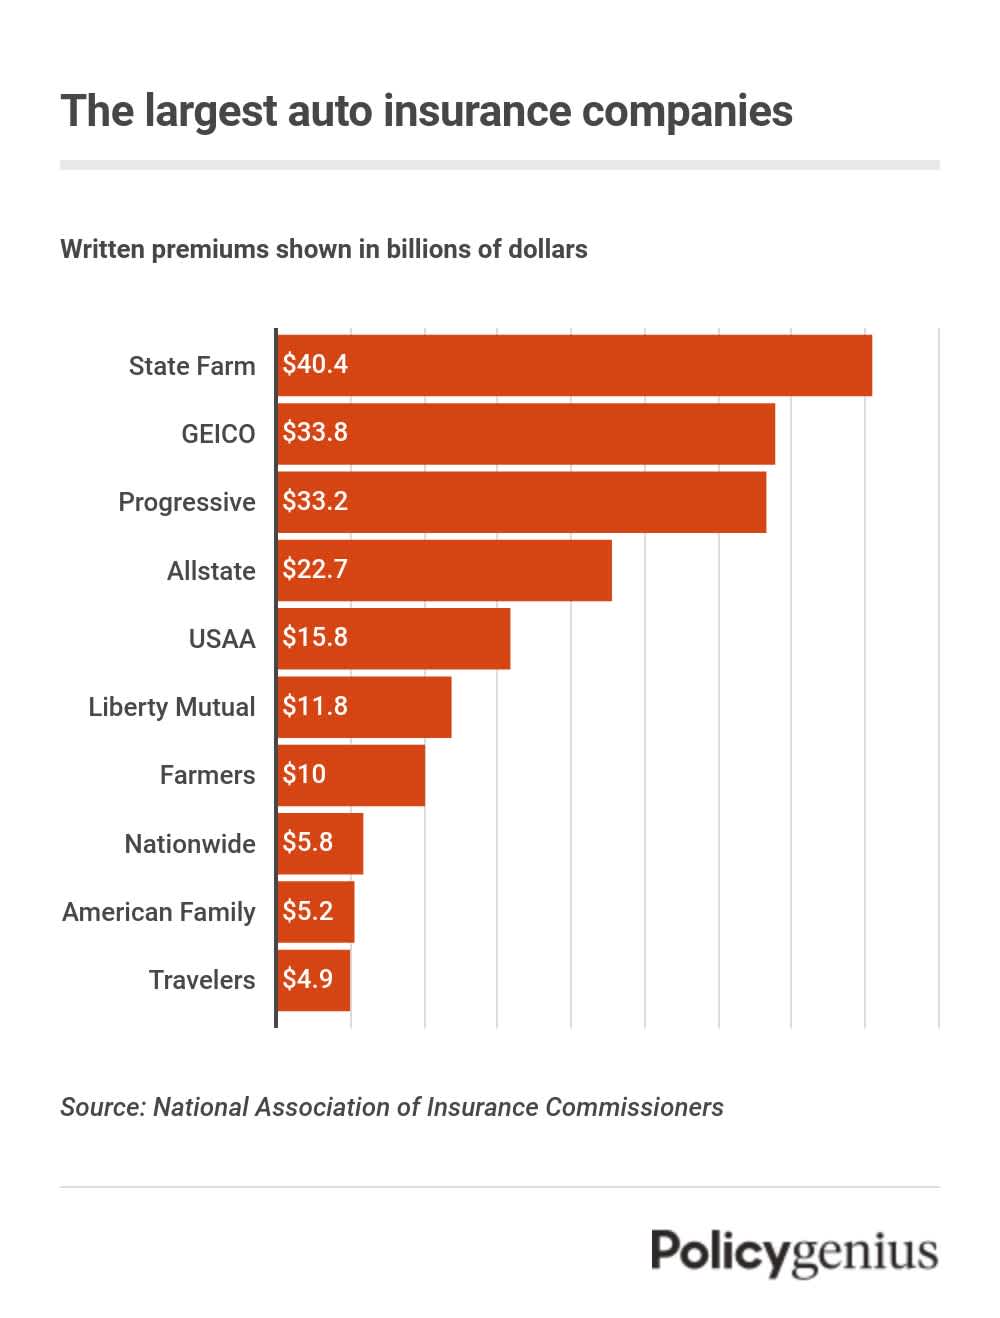
Auto insurance companies in the US form a critical part of the transportation ecosystem, offering protection against loss, liability, and unforeseen expenses. For example, State Farm provides a range of personal auto policies that combine liability, collision, and comprehensive coverage under a single contract.
The importance of these insurers lies in the legal requirement to maintain minimum liability coverage, the financial safety net they provide after accidents, and the broader economic stability they support by underwriting risk. Historically, the industry evolved from mutual fire insurance societies in the early 1900s to sophisticated, data‑driven underwriting firms today.
This article examines the major players, pricing dynamics, coverage nuances, regulatory environment, digital transformation, and consumer strategies. Readers will gain a clear roadmap for evaluating options and securing optimal protection.
1. Auto Insurance Companies in the US Overview
Understanding the landscape begins with recognizing the market leaders—State Farm, GEICO, Progressive, Allstate, and USAA—each catering to distinct demographics and risk profiles. Their market share reflects a blend of brand trust, pricing algorithms, and distribution channels such as agents, online platforms, and partnerships with automotive manufacturers.
These firms differ not only in premium rates but also in ancillary services like roadside assistance, rental car reimbursement, and usage‑based insurance (UBI) programs that adjust rates based on telematics data.
2. Pricing Dynamics
- Risk Assessment
Insurers evaluate driver history, vehicle type, location, and credit score to calculate risk. A 35‑year‑old driver with a clean record in Ohio typically enjoys lower premiums than a younger driver in California.
- Discount Structures
Multi‑policy, safe‑driver, and anti‑theft device discounts can shave 10‑20% off the base rate. For instance, bundling home and auto policies with Allstate often yields a combined discount.
- Regulatory Caps
State insurance departments impose limits on premium increases, influencing how quickly companies can adjust rates after loss events. California’s Proposition 103, for example, requires prior approval for rate hikes.
- Seasonal Variations
Winter storms increase claim frequency in northern states, prompting temporary premium adjustments. GEICO reported a modest rise in Midwest premiums during the 2022 snow season.
- Usage‑Based Pricing
Telematics devices track mileage and driving behavior, allowing companies like Progressive’s Snapshot to reward low‑risk drivers with lower rates.
3. Coverage Options and Add‑Ons
Standard policies include liability, collision, and comprehensive coverage. Liability protects against third‑party injuries and property damage, while collision covers damages to the insured vehicle after a crash. Comprehensive adds protection for non‑collision events such as theft, fire, or natural disasters.
Add‑ons enhance the base policy: uninsured motorist coverage shields against drivers without insurance; medical payments cover occupants’ medical expenses; and gap insurance bridges the difference between loan balance and actual cash value after a total loss.
4. Regulatory Environment
Each state sets minimum liability limits, dictates claim‑handling procedures, and enforces consumer protection rules. The NAIC (National Association of Insurance Commissioners) provides a uniform framework, but state variations create a complex compliance matrix for insurers.
Recent trends include the adoption of “no‑fault” statutes in states like Florida, which shift claim payments from at‑fault drivers to the insured’s own policy, influencing premium calculations and underwriting strategies.
5. Digital Transformation
Online quoting tools, mobile apps, and AI‑driven claim processing have reshaped the customer experience. Companies such as Lemonade, though primarily a renters insurer, illustrate how chat‑based onboarding can reduce acquisition costs for auto lines.
Telematics integration, predictive analytics, and blockchain for secure policy records are accelerating efficiency, enabling faster settlements and personalized pricing.
6. Consumer Decision‑Making
Choosing the right provider involves comparing premium quotes, reviewing financial strength ratings from agencies like AM Best, and assessing customer service metrics such as Net Promoter Score.
Consumers should also examine claim satisfaction reports; for example, J.D. Power’s annual study consistently ranks USAA high for claim handling, reflecting its veteran‑focused service model.
Frequently Asked Questions
Below are common inquiries about auto insurance companies in the US.
Question 1: How are auto insurance premiums calculated?
Premiums are based on risk factors such as driving record, age, vehicle model, location, and credit history. Insurers apply actuarial models to estimate expected losses and add administrative costs, resulting in the final price presented to the consumer.
Question 2: What is the minimum required coverage in most states?
Most states require liability coverage for bodily injury and property damage, typically expressed as a three‑number series (e.g., 25/50/25). Some states also mandate personal injury protection or uninsured motorist coverage.
Question 3: Can I bundle auto with other insurance policies?
Bundling home, renters, or life insurance with an auto policy often yields discounts ranging from 5% to 25%, depending on the insurer’s promotional structure and the combined risk profile.
Question 4: What are usage‑based insurance programs?
Usage‑based insurance (UBI) uses telematics to monitor mileage, speed, braking, and time of day. Drivers who demonstrate safe habits receive lower rates, while risky behavior may increase premiums.
Question 5: How does a claim affect future premiums?
Filing a claim can lead to a surcharge, often called a “loss cost multiplier,” which raises renewal premiums. The impact varies by insurer, claim frequency, and severity of loss.
Question 6: Are there any discounts for safe drivers?
Yes, most insurers offer safe‑driver discounts for clean records, defensive‑driving course completion, and low annual mileage. These discounts are typically applied automatically after verifying eligibility.
Tips for Choosing and Managing Auto Insurance
These ten actionable tips help navigate the market and maintain optimal coverage.
Tip 1: Compare at least three quotes. Gathering multiple estimates reveals price variations and uncovers hidden fees.
Tip 2: Review insurer’s financial strength. Strong ratings indicate the ability to pay claims promptly.
Tip 3: Assess discount eligibility. Check for multi‑policy, good‑student, and telematics discounts before finalizing.
Tip 4: Understand policy limits. Ensure liability limits exceed state minimums to protect assets.
Tip 5: Evaluate deductible impact. Higher deductibles lower premiums but increase out‑of‑pocket costs after a loss.
Tip 6: Keep a clean driving record. Safe driving directly reduces risk scores and premium rates.
Tip 7: Utilize usage‑based programs. Enroll in telematics if daily mileage is low or driving habits are conservative.
Tip 8: Re‑evaluate annually. Life changes such as moving or buying a new car may affect coverage needs.
Tip 9: Read the fine print. Look for exclusions, claim filing timelines, and cancellation policies.
Tip 10: Maintain documentation. Keep receipts, photos, and police reports organized to expedite future claims.
Conclusion
The auto insurance companies in the US landscape is shaped by pricing dynamics, diverse coverage options, regulatory frameworks, and rapid digital innovation. By understanding these key aspects, consumers can make informed decisions, secure appropriate protection, and potentially lower costs.
As technology continues to refine risk assessment and customer interaction, the next generation of policies will likely offer even greater personalization, rewarding safe drivers with unprecedented savings and convenience.

