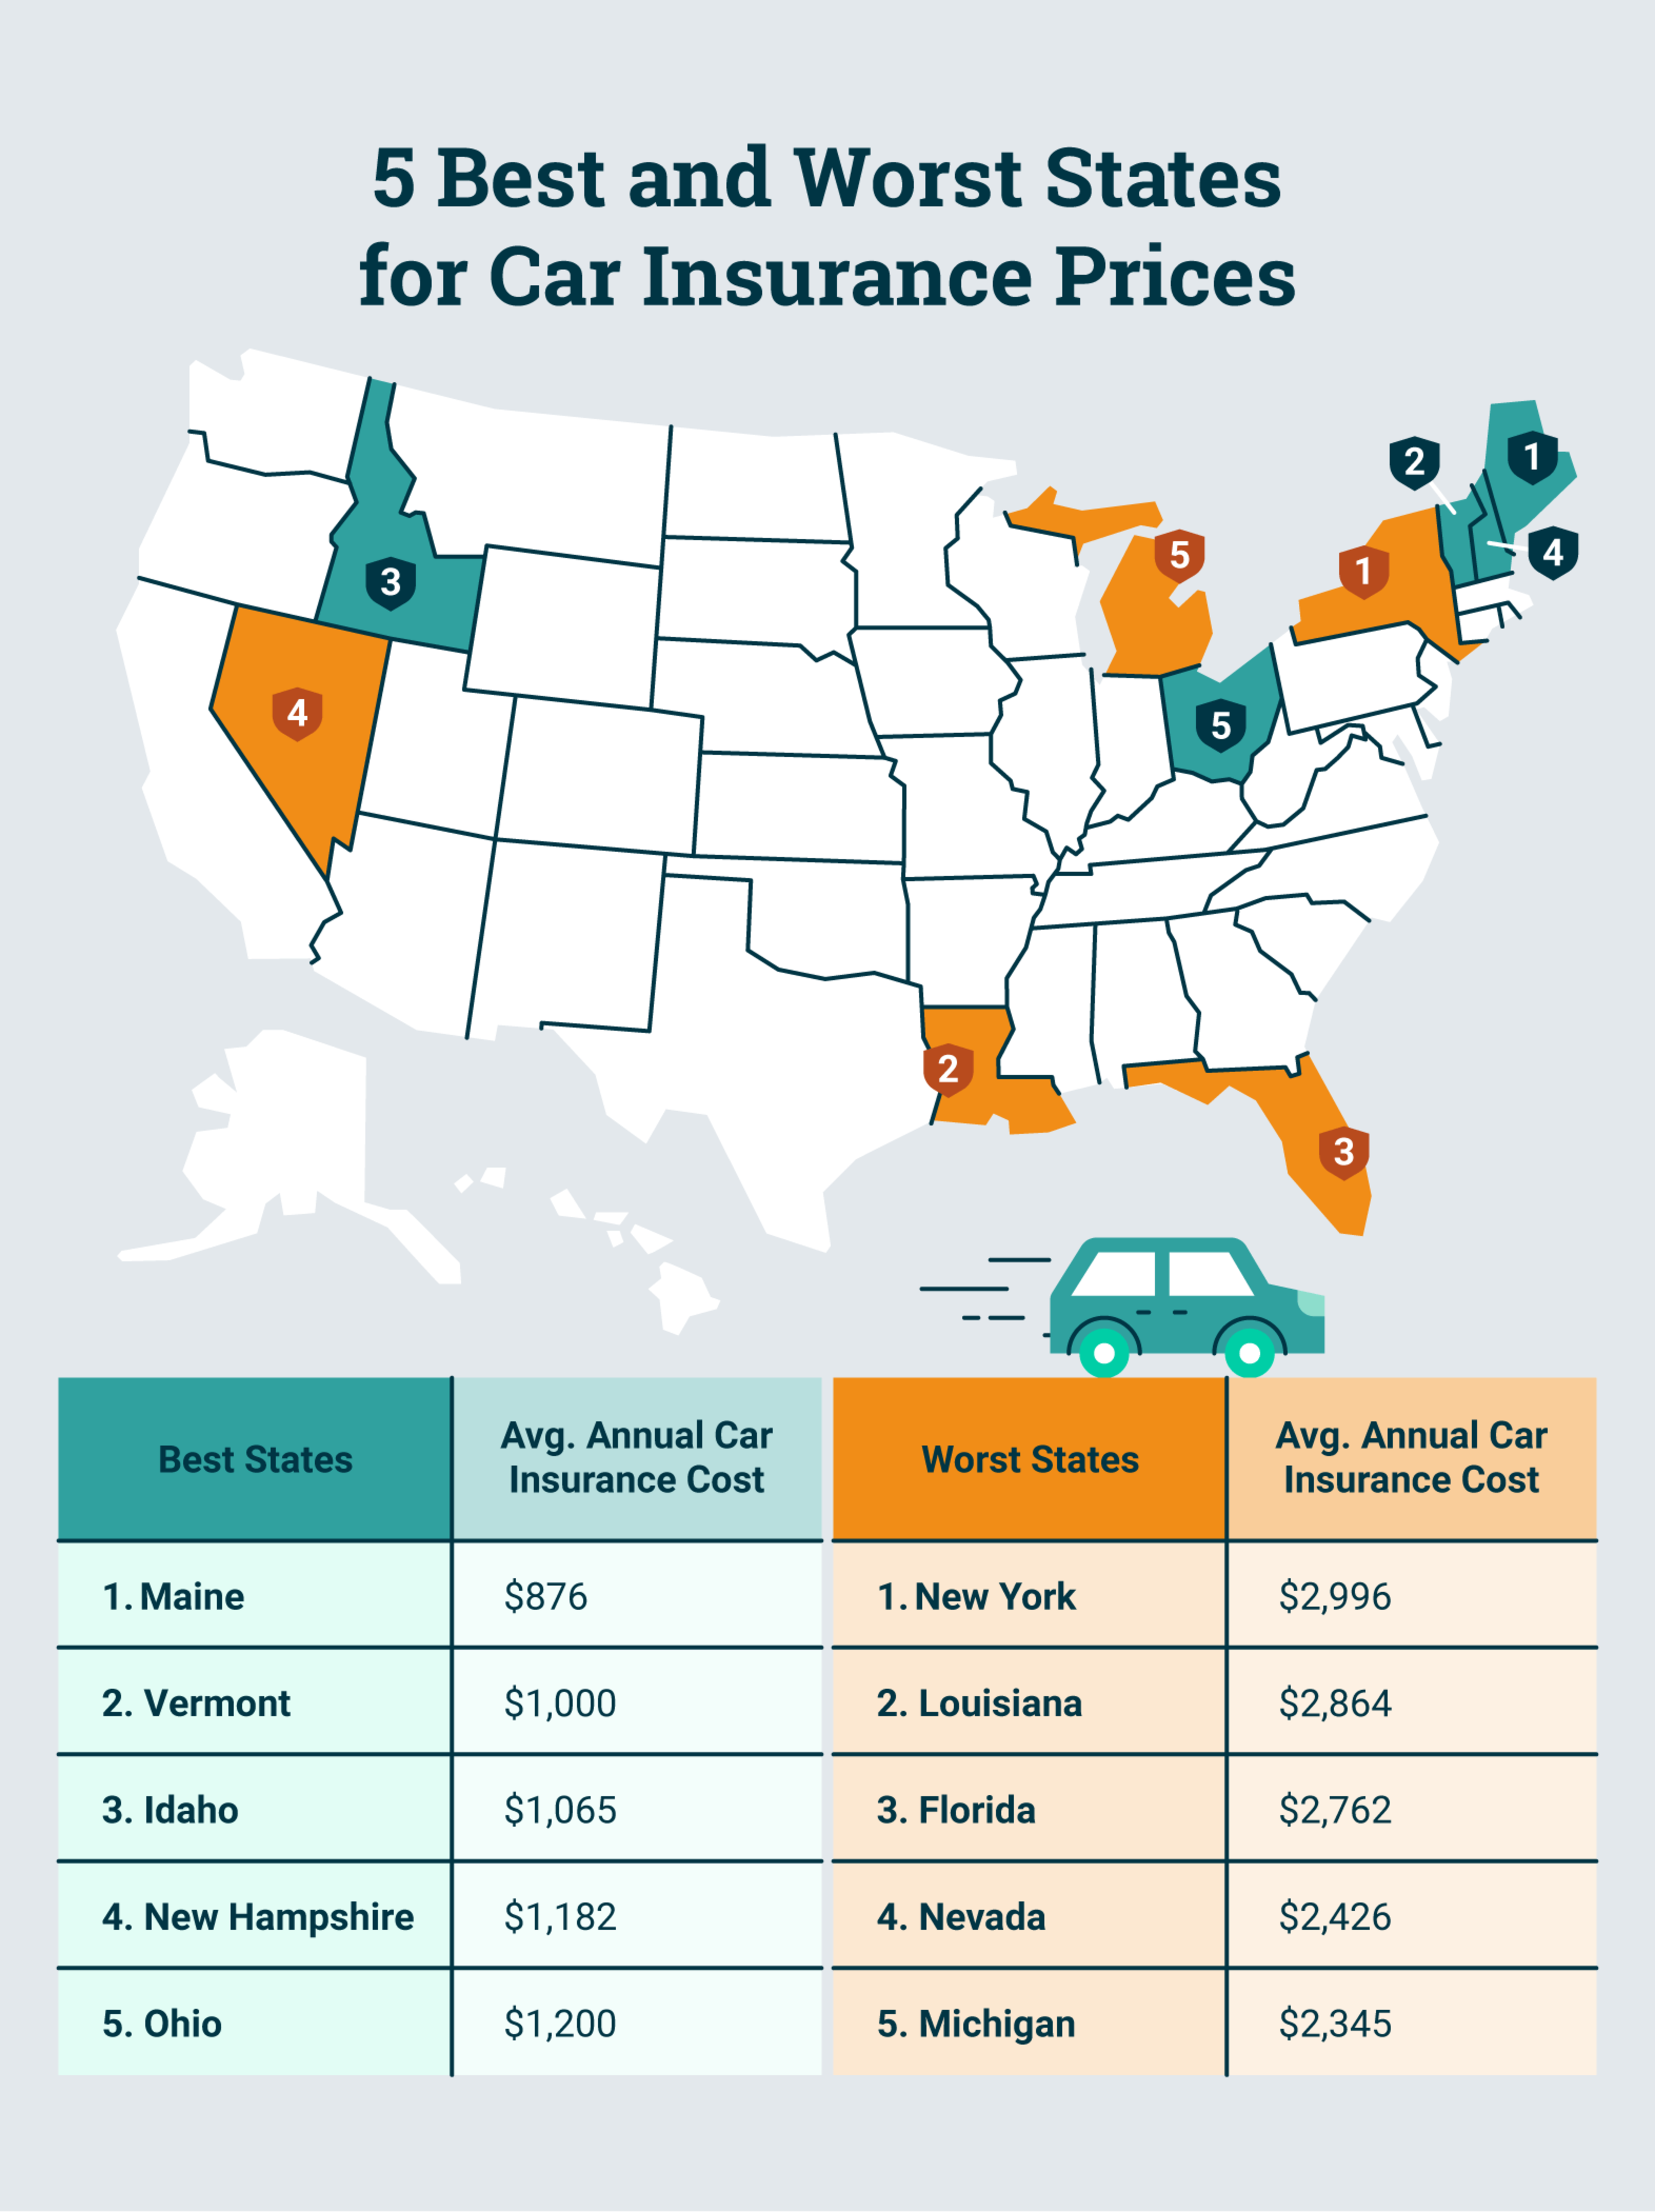
Finding **auto insurance best prices** means securing reliable coverage while maximizing savings—like a driver in Texas paying $1,200 annually instead of $1,800 for identical protection. The difference often hinges on understanding how insurers price policies, spotting overlooked discounts, and timing purchases strategically. Without this knowledge, drivers risk overpaying by 20–30% or more, a cost that compounds over time.
Auto insurance premiums reflect a blend of risk assessment, regional costs, and provider competition. For example, urban areas with higher theft rates or accident frequencies typically see higher rates, while rural regions benefit from lower exposure. Historically, insurance pricing evolved from basic actuarial tables to dynamic algorithms analyzing driving behavior via telematics. Today, the **auto insurance best prices** market is more transparent than ever, with tools like comparison sites and usage-based programs democratizing access to savings.
This guide explores the key factors influencing **auto insurance best prices**, common pitfalls to avoid, and actionable steps to secure competitive rates. Whether adjusting coverage limits or leveraging lesser-known discounts, small adjustments can yield significant returns.
1. How Insurers Calculate Auto Insurance Best Prices
Premiums aren’t arbitrary; they’re calculated using risk factors like driving record, vehicle type, and location. A clean record with a mid-range sedan in a low-crime area will always yield better rates than a sports car in a congested city. For instance, a 25-year-old driver in Los Angeles might pay $2,500 annually for full coverage, while the same policy in Omaha could cost $1,500—despite identical coverage.
Insurers also factor in claims history, credit scores (in most states), and even education level. A driver with a 750+ credit score could save 15–25% compared to someone with a 600 score. Understanding these variables helps drivers negotiate or switch providers to access **auto insurance best prices**.
2. Top 5 Factors That Slash Premiums
- Vehicle Safety Ratings
Cars with top safety scores (e.g., Subaru Outback or Honda Accord) qualify for lower premiums due to reduced claim likelihood. A vehicle earning a

