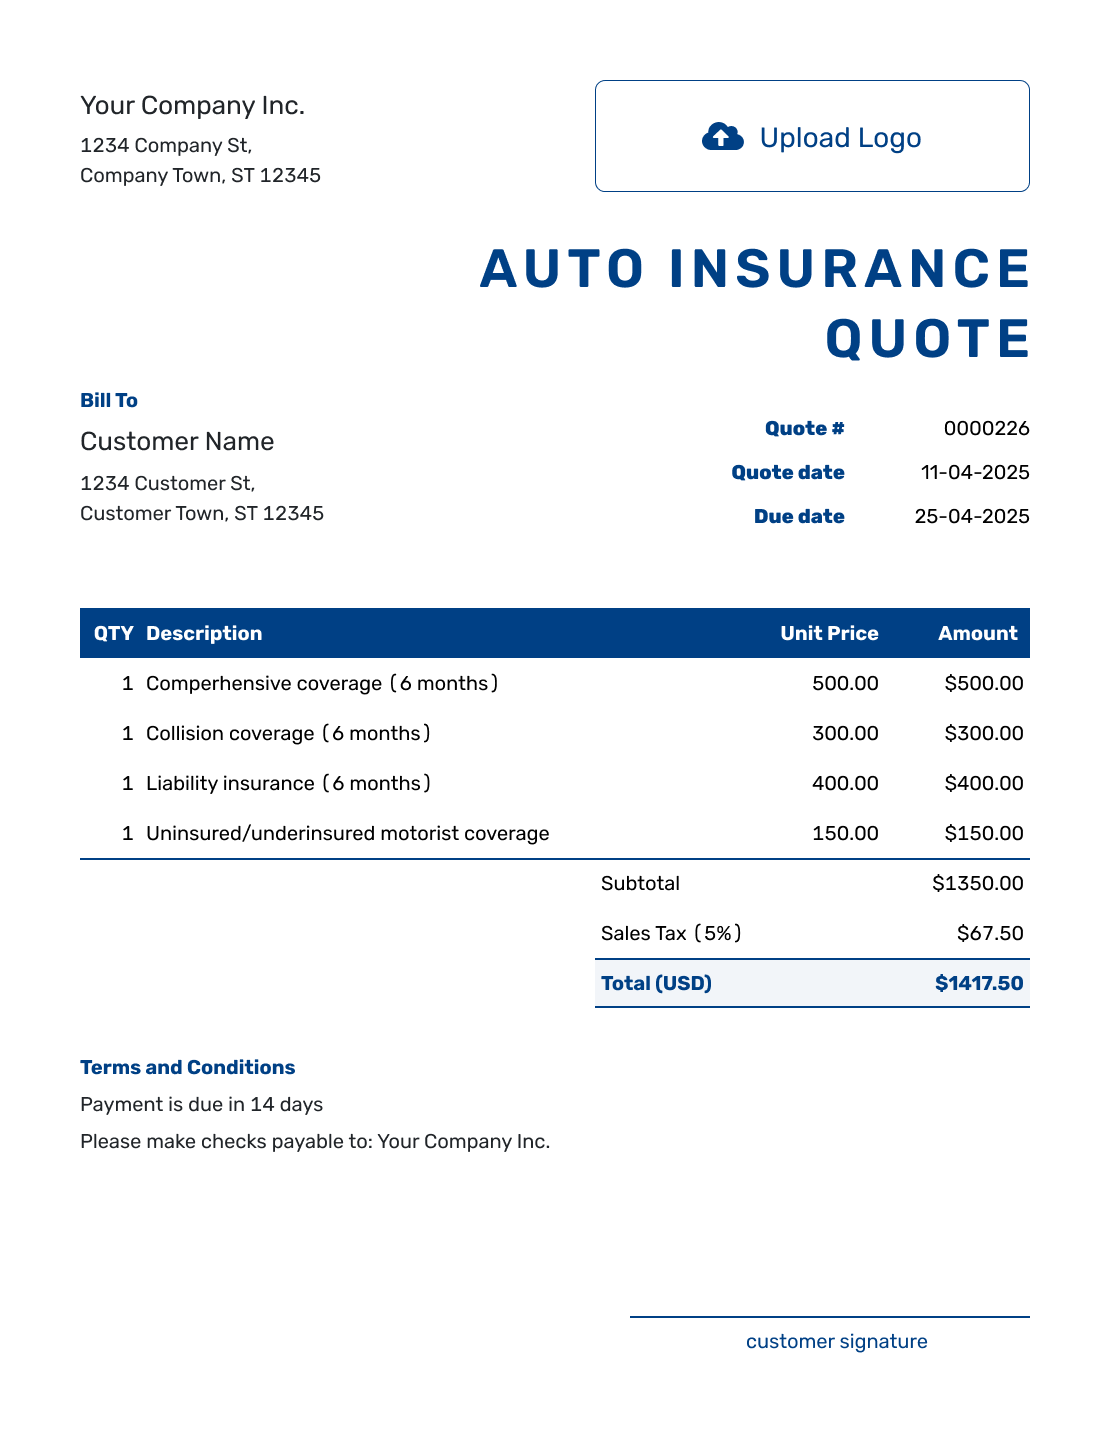
The term auto car cheap insurance quote refers to a low‑cost estimate provided by insurers for coverage of a motor vehicle. For instance, a 30‑year‑old driver in Ohio receives an $850 annual quote from XYZ Insurance after entering vehicle details online.
Understanding this estimate matters because it influences budgeting, risk management, and long‑term financial planning. Historically, the rise of digital aggregators in the early 2000s transformed how drivers access affordable rates, shifting the market from phone‑based negotiations to instant online calculations.
This article breaks down the mechanics behind low‑price estimates, highlights common pitfalls, outlines discount avenues, and equips readers with actionable steps to secure the best possible rate.
1. Pricing Dynamics
Premiums are calculated from a blend of actuarial data, driver profile, vehicle type, and regional risk factors. Younger drivers typically face higher base rates, yet a clean record can offset that increase. Additionally, state regulations dictate minimum coverage levels, which shape the floor of any quote.
Insurance companies also apply mileage‑based adjustments; lower annual mileage often translates to reduced exposure and thus cheaper quotes. Seasonal promotions, such as “safe driver month,” temporarily lower pricing algorithms, creating windows of opportunity for cost‑savvy shoppers.
2. Common Mistakes
- Skipping coverage comparison
Relying on a single provider’s offer ignores market variability. A driver in Texas who compared three insurers saved roughly $200 annually by switching to a carrier with a better multi‑policy discount.
- Over‑insuring a vehicle
Selecting collision coverage for a 10‑year‑old car with low market value adds unnecessary expense. Opting for liability‑only protection in such cases can halve the premium.
- Ignoring credit‑score impact
Many states factor credit history into premium calculations. Improving a moderate credit score by a few points can shave 5‑10% off the quote.
- Neglecting discount eligibility
Bundling home and auto policies, maintaining a defensive‑driving course certificate, or installing anti‑theft devices each trigger distinct discounts that many drivers overlook.
3. Discount Opportunities
- Multi‑Vehicle Bundle
Insuring two or more cars under a single policy often yields a 15% reduction. A family with a sedan and an SUV experienced a combined saving of $300 per year.
- Safe Driver Programs
Telematics devices monitor braking and acceleration patterns. Drivers who maintain smooth habits receive up to a 20% premium cut.
- Loyalty and Longevity
Some carriers reward ten‑year policyholders with a modest discount, encouraging retention while lowering the quote for long‑standing customers.
- Affiliation Discounts
Membership in professional organizations, alumni groups, or credit unions frequently unlocks exclusive rate reductions.
4. Comparison Tools
Online aggregators compile data from dozens of insurers, presenting side‑by‑side quotes based on identical input parameters. These platforms accelerate the research phase, allowing drivers to pinpoint the lowest auto car cheap insurance quote within minutes.
However, not all carriers participate in every aggregator, so supplementing digital searches with direct insurer inquiries ensures a comprehensive view of the market.
5. Auto Car Cheap Insurance Quote
When the keyword appears in a headline, it signals to readers that the section will directly address how to obtain that specific estimate. The process begins with accurate vehicle information: VIN, mileage, and primary use. Next, inputting driver details—age, driving history, and residence—feeds the underwriting engine.
Precision matters; a typo in the ZIP code can inflate the quote by 10% due to differing regional risk scores. After submitting the data, most platforms generate an instant estimate, allowing immediate comparison against alternative offers.
Finally, contacting the insurer to verify the quoted amount and explore optional endorsements can further refine the final cost, ensuring the quoted figure reflects the true coverage needs.
6. Policy Customization
- Deductible Adjustment
Raising the deductible from $500 to $1,000 typically reduces the premium by 5‑10%, appealing to drivers comfortable with higher out‑of‑pocket costs after a claim.
- Liability Limit Selection
Choosing state‑minimum liability limits lowers the quote but may expose the driver to financial risk in severe accidents. Balancing affordability with adequate protection is essential.
- Add‑On Riders
Roadside assistance, rental reimbursement, and glass‑break coverage are optional. Adding only the most needed riders prevents unnecessary premium inflation.
- Usage‑Based Policies
Pay‑per‑mile plans calculate rates based on actual driving distance, offering a cost‑effective solution for infrequent drivers.
Frequently Asked Questions
Quick answers to the most common queries about securing low‑cost auto coverage.
Question 1: How does age affect an auto car cheap insurance quote?
Age remains a primary risk indicator; younger drivers face higher base rates, while drivers over 25 typically receive more favorable pricing. Insurers adjust premiums based on statistical accident frequency for each age bracket.
Question 2: Can a clean driving record eliminate all extra fees?
A spotless record removes many surcharge categories, yet other factors—such as location, vehicle model, and credit score—still influence the final estimate. Eliminating all fees is rare, but the overall cost can drop significantly.
Question 3: Are online quotes as reliable as phone quotes?
Online quotes use the same actuarial formulas as traditional methods, provided the entered data matches the insurer’s records. For complex situations, a brief phone call may clarify nuances, but digital estimates are generally accurate.
Question 4: What role does credit history play in pricing?
In most states, insurers incorporate credit‑based insurance scores into premium calculations. Better credit can lower the quote by up to 15%, while poor credit may increase costs substantially.
Question 5: How often should drivers request a new quote?
Renewal periods and major life changes—such as moving, buying a new car, or adding a driver—are optimal times to request fresh estimates. Annual checks help capture emerging discounts.
Question 6: Do discounts stack?
Many carriers allow multiple discounts to apply simultaneously, such as bundling, safe‑driver, and affiliation offers. Reviewing the policy’s discount matrix ensures maximum savings without overlapping restrictions.
Tips
Tip 1: Shop Early. Initiate the quote process before the policy renewal date to leverage promotional pricing.
Tip 2: Verify Vehicle Data. Double‑check the VIN and mileage entries to avoid inflated estimates.
Tip 3: Adjust Deductibles. Increase the deductible where financially feasible to reduce the premium.
Tip 4: Bundle Policies. Combine auto with home or renters insurance to unlock multi‑policy discounts.
Tip 5: Explore Telemetry. Install a usage‑based device to qualify for safe‑driving discounts.
Tip 6: Review Credit. Improve the credit score before requesting a quote to benefit from lower rates.
Tip 7: Ask About Affiliation. Inquire about discounts tied to professional groups or alumni associations.
Tip 8: Limit Unnecessary Add‑Ons. Select only essential riders to keep the quote lean.
Tip 9: Compare Regional Rates. Check neighboring state quotes if relocation is planned, as premiums can vary widely.
Tip 10: Update Driving Record. Report any recent ticket dismissals to ensure the record reflects current risk.
Tip 11: Consider Pay‑Per‑Mile. For low‑usage drivers, mileage‑based plans often produce the cheapest quote.
Tip 12: Re‑evaluate Annually. Conduct a yearly review to capture new discount opportunities.
Tip 13: Leverage Loyalty. Long‑term customers may receive retention discounts; ask the insurer directly.
Tip 14: Use Multiple Aggregators. Different platforms may feature exclusive carrier partnerships.
Tip 15: Confirm Coverage Limits. Align liability limits with personal risk tolerance to avoid overpaying.
Tip 16: Document Safety Features. Highlight anti‑theft devices and advanced driver‑assist systems to reduce the quote.
Conclusion
The examined aspects—from pricing dynamics and common errors to discount avenues and policy customization—provide a comprehensive roadmap for obtaining an auto car cheap insurance quote without compromising essential protection.
By applying the outlined strategies and regularly revisiting the coverage landscape, drivers position themselves to secure sustainable savings while maintaining robust vehicle protection for the road ahead.

