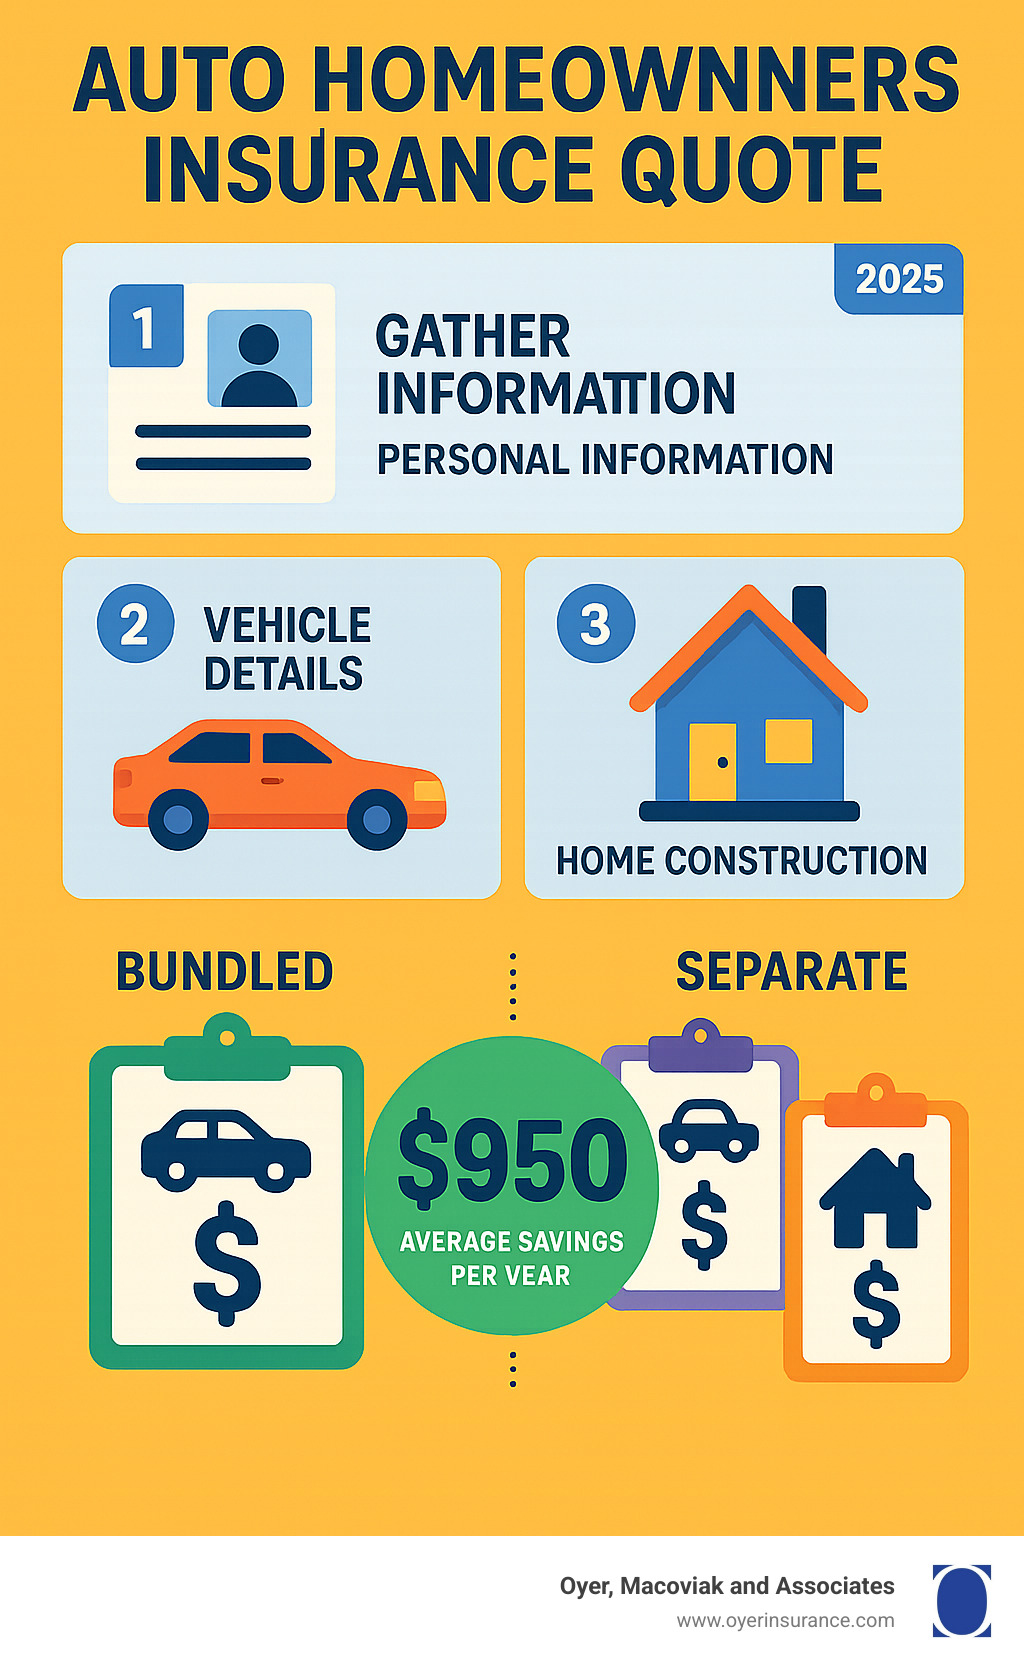
Getting an auto and homeowners insurance quote is the first step toward protecting both a vehicle and a residence with a single, coordinated financial plan. For example, a family in Austin might request a combined quote that shows $1,200 annually for auto coverage and $950 for homeowners, revealing a bundled discount.
Understanding this quote matters because it influences budgeting, risk management, and long‑term financial stability. Historically, insurers began offering bundled policies in the early 1990s to reward customers who trusted a single carrier with multiple assets, leading to lower premiums and simplified paperwork.
This article breaks down the mechanics of combined quotes, highlights common pitfalls, and provides a roadmap for comparing offers, so readers can secure optimal coverage without overpaying.
1. Understanding auto and homeowners insurance quote
At its core, a combined quote aggregates data from two distinct lines of insurance—auto and homeowners—into a single premium estimate. The process starts with personal details, vehicle specifications, property characteristics, and claims history. Insurers then apply underwriting algorithms to calculate risk and potential discounts.
Because each line has its own rating factors, the final figure reflects the interplay between them. For instance, a clean driving record may offset a higher‑risk property location, resulting in a balanced overall price.
2. Pricing dynamics
- Risk weighting
Each policy line receives a risk score; higher scores raise the combined premium. A homeowner in a flood zone sees that factor added to the auto portion, illustrating how geographic risk influences overall cost.
- Bundling discounts
Insurers often shave 5‑15% off the total when both policies are purchased together. A real‑life example: a driver saved $180 annually by bundling with the same carrier that also insured their condo.
- Deductible choices
Higher deductibles lower the quote but increase out‑of‑pocket expenses after a loss. A family opting for a $1,500 auto deductible and $2,000 home deductible reduced their combined quote by roughly $120 per year.
These dynamics interact, meaning a small change in one area can ripple through the total price. Understanding them empowers shoppers to tweak variables strategically.
3. Coverage gaps to watch
- Liability limits
Separate limits for auto and home may leave exposure if a single event triggers both claims. A homeowner whose car hits a neighbor’s fence might face insufficient liability on the auto policy alone.
- Personal property overlap
Duplicate coverage of personal belongings can inflate costs without added protection. For example, valuable jewelry insured under both policies creates redundancy.
- Uninsured motorist vs. windstorm
Auto policies cover uninsured drivers, while homeowners handle windstorm damage. Missing either leaves a homeowner vulnerable during a hurricane‑related incident.
Identifying and eliminating these gaps ensures the combined quote delivers true value rather than superficial savings.
4. Common mistakes when requesting quotes
Many consumers provide incomplete vehicle or property details, leading to inaccurate estimates that require later adjustments. Others compare only the headline premium, ignoring differences in deductibles, limits, and endorsements, which can skew perceived savings.
Another frequent error is neglecting to update information annually. A new garage addition or a recent traffic violation can significantly affect the quote, yet many let the original numbers linger.
5. How to compare multiple quotes effectively
- Standardized spreadsheets
Enter each quote’s premium, deductible, limits, and discounts into a table. A family in Denver used this method to spot a $250 annual saving after adjusting deductibles.
- Coverage equivalence check
Ensure each quote offers comparable protection levels. A lower price that drops comprehensive coverage may cost more in the long run.
- Financial strength ratings
Review A.M. Best or Moody’s scores; a cheaper carrier with a weak rating could struggle to pay claims.
- Customer service reviews
Online forums reveal how insurers handle claims. Positive experiences often outweigh a modest premium difference.
- Policy endorsements
Look for optional add‑ons like roadside assistance or water backup coverage that may be essential for specific households.
Applying this systematic approach transforms a confusing array of numbers into a clear decision matrix.
6. Leveraging technology for faster quotes
Modern insurers offer instant online calculators that pull data from DMV records and property tax databases. A pilot program in Seattle demonstrated a 30% reduction in quote turnaround time when users allowed API access.
Mobile apps also let policyholders upload photos of damages, speeding up adjustments and reinforcing the value of a combined policy that shares claim histories across lines.
7. Future trends in combined insurance quoting
Telematics devices will increasingly inform auto risk scores, while smart home sensors will feed real‑time property data to underwriters. These innovations promise more personalized premiums and potentially greater bundling incentives.
Regulatory shifts toward greater data transparency may require insurers to disclose how each factor influences the final quote, helping consumers make even more informed choices.
Frequently Asked Questions
Below are concise answers to the most common queries about combined insurance quoting.
Question 1: How does bundling affect the overall premium?
Bundling typically reduces the total cost by 5‑15% because insurers reward customers for consolidating risk. The discount applies to both lines, but exact savings depend on the carrier’s pricing model and the individual risk profiles.
Question 2: Can a single deductible be applied to both policies?
No. Each line maintains its own deductible structure. However, selecting higher deductibles on both policies can amplify overall savings, as each deductible reduction directly lowers its respective premium.
Question 3: What factors most heavily influence an auto and homeowners insurance quote?
Key drivers include driving record, vehicle age, property location, construction type, claims history, and chosen coverage limits. External elements such as local weather patterns or traffic density also play significant roles.
Question 4: Is it better to get quotes from the same insurer or multiple carriers?
Starting with the current insurer can reveal bundling discounts, but comparing multiple carriers ensures competitive pricing. A balanced approach—requesting quotes from both the existing carrier and at least two new ones—offers the most comprehensive view.
Question 5: How often should the combined quote be refreshed?
Review the quote annually or after major life events—such as buying a new car, renovating a home, or adding a teenage driver. Regular updates capture changes in risk and preserve potential savings.
Question 6: Do discounts for safety devices apply to both policies?
Many insurers extend discounts for home security systems and vehicle safety features, but they are evaluated separately. Installing a smart lock may lower the homeowners portion, while a car’s collision avoidance system reduces the auto segment.
9 actionable tips for mastering your auto and homeowners insurance quote
Follow these precise steps to optimize coverage and cost.
Tip 1: Gather accurate data. Collect VIN, mileage, property square footage, and recent renovation details before requesting quotes.
Tip 2: Align coverage limits. Ensure liability, dwelling, and personal property limits match across all quotes for fair comparison.
Tip 3: Adjust deductibles wisely. Raise deductibles only if comfortable with the out‑of‑pocket amount after a loss.
Tip 4: Verify discount eligibility. Ask about bundling, safe driver, multi‑policy, and loyalty discounts specific to each carrier.
Tip 5: Review endorsements. Add optional coverages like flood, earthquake, or roadside assistance only when risk exposure justifies the cost.
Tip 6: Check insurer ratings. Prioritize carriers with strong financial stability scores to guarantee claim payment.
Tip 7: Use comparison tools. Input quotes into a spreadsheet to visualize premium, deductible, and coverage differences.
Tip 8: Update annually. Re‑request quotes each year or after major life changes to capture new discounts.
Tip 9: Read the fine print. Confirm exclusions, claim filing procedures, and renewal terms before signing.
Conclusion
The auto and homeowners insurance quote serves as a comprehensive snapshot of risk and cost for two of the most valuable assets. By dissecting pricing dynamics, avoiding common pitfalls, and leveraging technology, shoppers can secure balanced protection while maximizing savings.
Armed with the outlined strategies and actionable tips, the next quote request will be a confident, informed step toward lasting financial security.

