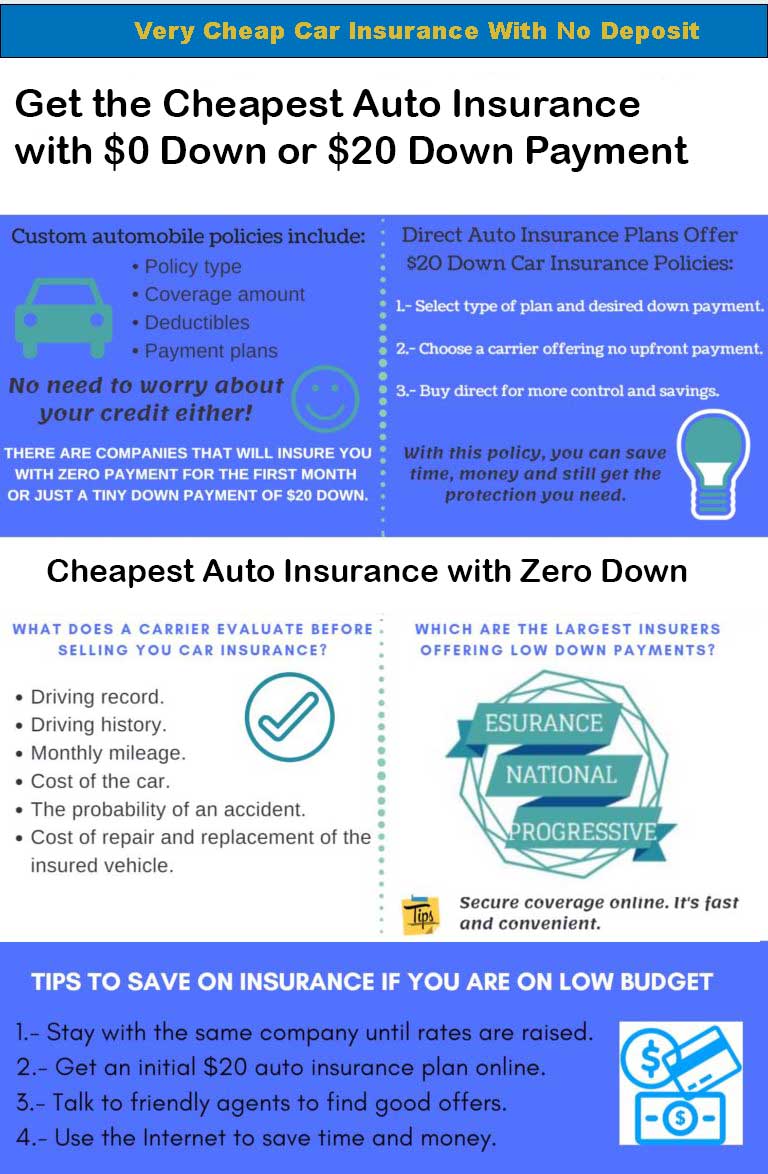
a affordable car insurance provides budget‑friendly protection for drivers seeking reliable coverage without excessive premiums. For instance, a policy from GEICO that combines a $500 deductible with a $800 annual premium illustrates how affordability and adequate protection can coexist.
The importance of a affordable car insurance lies in its ability to balance financial safety with everyday mobility. Historically, auto insurance costs surged after the 1970s oil crises, prompting insurers to develop tiered products that address varying budget constraints while maintaining essential liability coverage.
This article examines pricing dynamics, discount opportunities, essential coverage components, claim handling, provider reputation, and regulatory considerations, offering a comprehensive roadmap for selecting cost‑effective protection.
1. Understanding a affordable car insurance
Understanding a affordable car insurance begins with recognizing that affordability does not imply neglect of critical risk exposures. It involves evaluating the trade‑off between premium amount and the breadth of coverage, ensuring that minimum legal requirements are met while seeking additional value.
Key metrics include the loss‑ratio, underwriting standards, and the insurer’s expense load. By scrutinizing these factors, drivers can identify policies that deliver solid protection at a reasonable price point.
2. Pricing dynamics
- Base Premium
The base premium reflects the core cost of coverage before adjustments. A driver in Ohio may pay $1,200 annually for a standard liability‑only plan, illustrating the baseline expense.
- Risk Scores
Insurers assign risk scores based on driving history, age, and credit. A high score can reduce the premium by up to 15%, directly influencing affordability.
- Geographic Factors
Urban areas with higher accident rates typically command higher rates. For example, a policy in Los Angeles often costs 20% more than a comparable one in rural Kansas.
- Policy Bundling
Combining auto with home or renters insurance can yield bundled discounts, sometimes exceeding $300 per year, reinforcing the overall cost‑saving strategy.
3. Discount opportunities
- Safe Driver
Maintaining a clean record for three consecutive years can unlock a 10% safe‑driver discount, as demonstrated by State Farm’s reward program.
- Multi‑Vehicle
Insuring two or more vehicles under one policy often reduces each vehicle’s premium by 5‑12%, a common practice among large carriers.
- Good Student
Full‑time students with a GPA of 3.5 or higher may qualify for a 5% discount, a benefit frequently offered by Progressive.
- Pay‑In‑Full
Paying the annual premium upfront eliminates financing fees, saving roughly 2‑4% compared with monthly installments.
- Telematics
Usage‑based programs that monitor mileage and driving behavior can cut premiums by up to 30% for low‑risk drivers, as seen with Allstate’s Drivewise.
4. Coverage essentials
- Liability
Liability coverage satisfies legal minimums and protects against third‑party claims. A $25,000 bodily injury limit is a common entry point.
- Collision
Collision covers damages to the insured vehicle after an accident, regardless of fault. Adding a $500 deductible can lower the premium while preserving essential protection.
- Comprehensive
Comprehensive addresses non‑collision events such as theft or natural disasters. Drivers in flood‑prone regions often prioritize this component.
- Uninsured Motorist
This coverage compensates for injuries caused by drivers lacking insurance, a critical safeguard in states with high uninsured rates.
5. Claim experience
The claim experience influences long‑term affordability because frequent claims can trigger premium hikes. Efficient claim processing, as exemplified by USAA’s average settlement time of 48 hours, reduces stress and indirect costs.
Documenting incidents with photos, police reports, and timely communication accelerates resolution. Policyholders who follow insurer guidelines often benefit from lower deductible waivers on subsequent claims.
6. Provider reputation
Provider reputation encompasses financial stability, customer satisfaction, and claims handling speed. Ratings from A.M. Best and J.D. Power serve as reliable indicators.
Insurers with strong reputations tend to retain policyholders longer, which can translate into loyalty discounts and more favorable renewal terms, reinforcing the overall affordability equation.
7. State regulations
State regulations dictate minimum coverage limits, rating factors, and discount eligibility. For example, California mandates uninsured motorist coverage, while Texas permits credit‑based pricing.
Understanding local statutes enables drivers to avoid unnecessary add‑ons and focus on required protections, thereby streamlining costs.
Frequently Asked Questions
Below are common inquiries regarding a affordable car insurance and practical answers.
Question 1: How does a affordable car insurance differ from standard policies?
Affordable options prioritize lower premiums while meeting legal minimums, often by limiting optional coverages or increasing deductibles, yet they still provide essential liability protection.
Question 2: Which factors most affect the cost of a affordable car insurance?
Key factors include driving record, age, location, vehicle type, credit score, and selected discounts; each element can raise or lower the final premium.
Question 3: Are telematics programs worth the potential privacy trade‑off?
For low‑risk drivers, telematics can reduce premiums by up to 30%, making the cost savings often outweigh privacy concerns, especially when data is limited to driving behavior.
Question 4: Can bundling policies guarantee the lowest price?
Bundling typically yields discounts, but the overall lowest price depends on individual carrier offers; comparing bundled versus separate quotes remains essential.
Question 5: How often should coverage be reviewed?
Reviewing coverage annually or after major life events—such as moving, purchasing a new vehicle, or changing employment—helps maintain affordability and adequacy.
Question 6: What steps improve claim outcomes?
Promptly reporting incidents, providing thorough documentation, and cooperating with adjusters increase the likelihood of fair settlements and may prevent premium spikes.
Tips for Getting a Affordable Car Insurance
Implementing strategic actions can enhance affordability without sacrificing protection.
Tip 1: Compare multiple quotes. Gathering estimates from at least three carriers reveals pricing variations and hidden discounts.
Tip 2: Increase deductibles wisely. Raising the deductible to $1,000 can lower premiums, provided sufficient emergency funds exist.
Tip 3: Maintain a clean driving record. Avoiding violations preserves safe‑driver discounts that directly reduce costs.
Tip 4: Leverage telematics programs. Enrolling in usage‑based insurance offers data‑driven savings for disciplined drivers.
Tip 5: Bundle with other policies. Combining auto with home or renters insurance often unlocks multi‑policy discounts.
Tip 6: Review coverage limits annually. Adjusting limits to reflect current needs prevents over‑insuring.
Tip 7: Shop during renewal windows. Insurers frequently launch promotional rates at renewal periods.
Tip 8: Ask about loyalty discounts. Long‑term customers may qualify for reduced rates without switching carriers.
Tip 9: Verify eligibility for group plans. Employer or alumni associations sometimes offer exclusive group pricing.
Tip 10: Pay the premium in full. Eliminating installment fees can shave a few percent off the total cost.
Tip 11: Keep credit health strong. In states allowing credit‑based pricing, a higher score translates to lower premiums.
Tip 12: Limit optional add‑ons. Evaluate the necessity of roadside assistance or rental reimbursements before inclusion.
Tip 13: Reassess after major life changes. Marital status, relocation, or vehicle upgrades often trigger new discount opportunities.
Conclusion
The exploration of pricing dynamics, discount mechanisms, essential coverages, claim processes, provider reputation, and regulatory frameworks equips drivers with the knowledge to secure a affordable car insurance that balances cost and protection.
By applying the outlined strategies and staying vigilant about market shifts, policyholders can continuously optimize their auto insurance spend while safeguarding their financial wellbeing.

