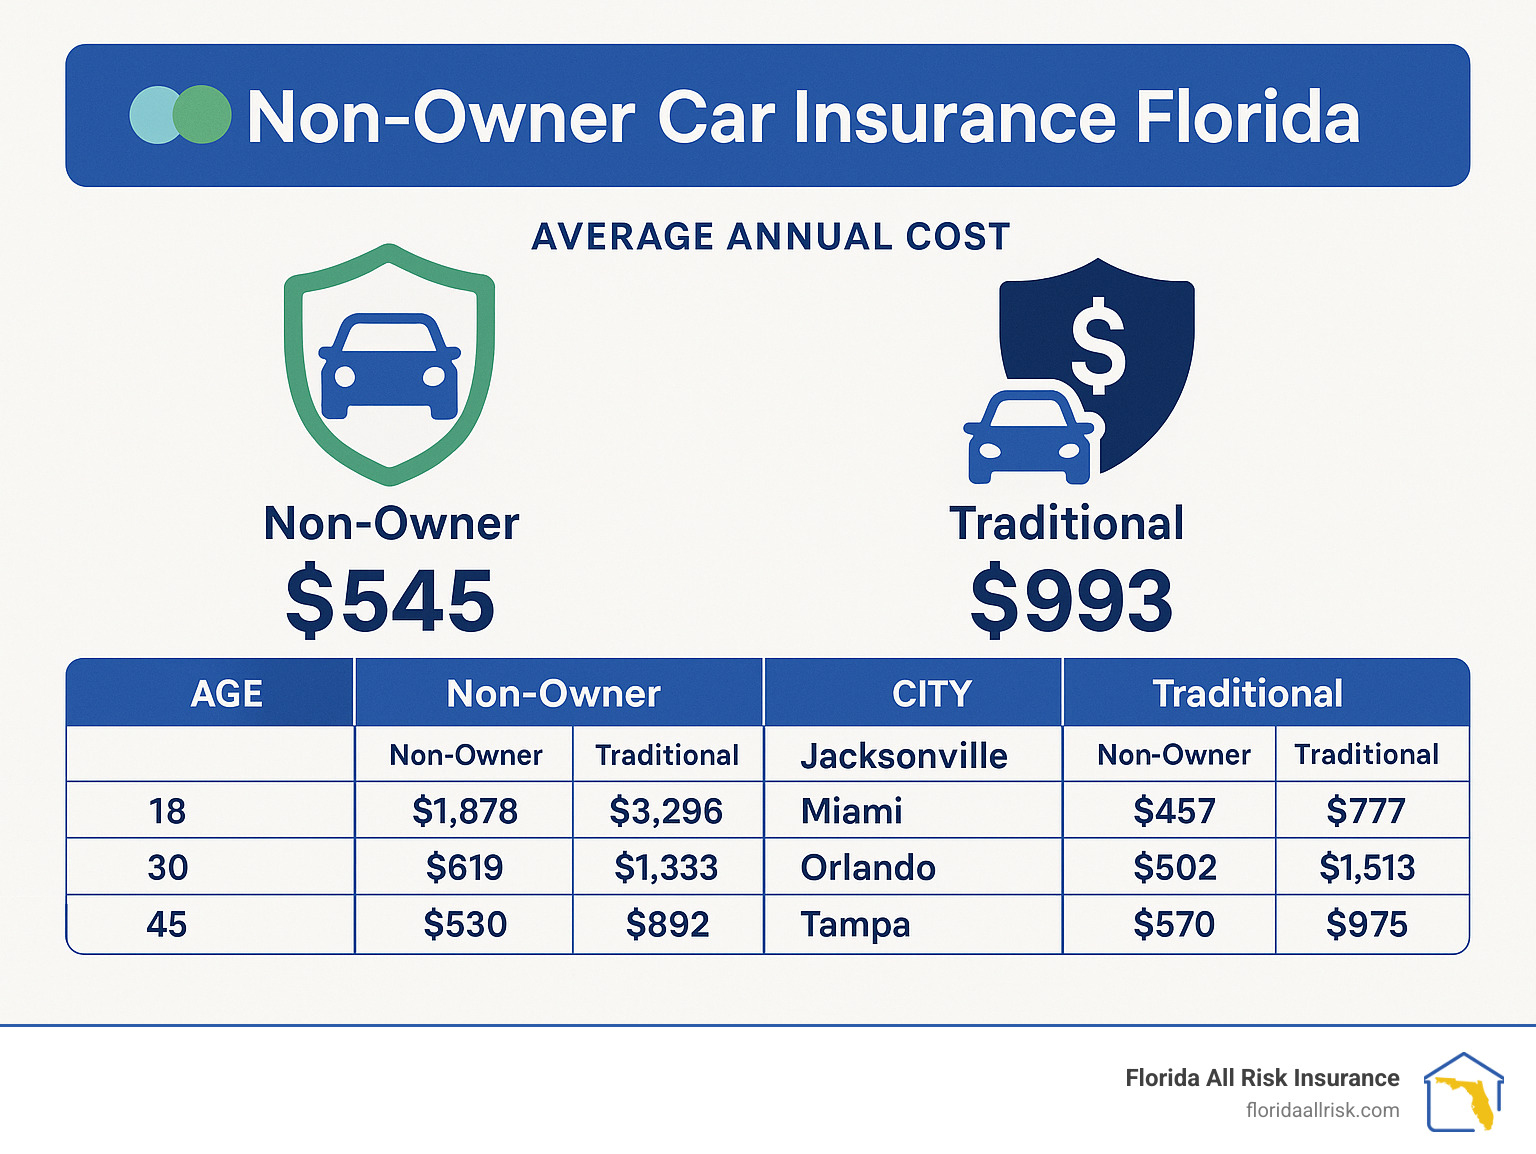
auto insurance quotes florida refer to the price estimates provided by insurers for motorists residing in the Sunshine State, based on personal driving records, vehicle type, and coverage preferences. For example, a 30‑year‑old driver with a 2018 Toyota Camry in Miami might receive three distinct quotes ranging from $1,200 to $1,650 annually, reflecting differences in liability limits and deductible choices.
Understanding these estimates is crucial because auto insurance is mandatory in Florida, and the state’s unique no‑fault system influences premium calculations. Access to multiple quotes enables drivers to identify competitive rates, evaluate insurer financial strength, and select policies that align with budgeting goals while maintaining adequate protection.
This article explores the mechanics behind auto insurance quotes florida, outlines factors that affect pricing, highlights common pitfalls, and provides actionable steps for securing the best possible coverage. Readers will gain insight into comparison tools, discount opportunities, and regulatory considerations that shape the quoting process.
1. Auto Insurance Quotes Florida Overview
Florida’s insurance market features a blend of regional carriers and national firms, each employing distinct underwriting algorithms. The state’s no‑fault law requires Personal Injury Protection (PIP) coverage, which adds a baseline cost to every quote. Additionally, hurricane‑prone coastal areas often experience higher premiums due to increased risk of total loss.
- State‑Specific Regulations
Regulations mandate minimum liability limits of $10,000 per person and $20,000 per accident, influencing the base price of every quote. Drivers in Jacksonville must meet these standards, which can raise premiums compared to states with lower minimums.
- Risk Assessment Models
Insurers evaluate driving history, credit score, and vehicle usage patterns. A Miami resident with a clean record and high credit score may see a 12% discount, illustrating how personal factors directly affect quote amounts.
- Geographic Variations
Urban centers like Tampa often have higher accident frequencies, leading to elevated rates. Conversely, rural counties such as Levy may benefit from lower claim frequencies, resulting in more affordable quotes.
2. Pricing Dynamics
Premiums fluctuate due to a combination of actuarial data and market competition. When a major carrier introduces a promotional discount, rival companies may adjust their rates to remain attractive, creating a ripple effect across the market. Seasonal factors, such as increased travel during winter months, can also cause temporary spikes in claim activity, prompting insurers to raise prices for new policies.
Understanding these dynamics helps drivers anticipate when to shop for quotes. For instance, purchasing a policy in late summer, after the peak travel season, often yields lower rates because insurers experience reduced claim volumes.
3. Discount Opportunities
- Multi‑Policy Bundling
Combining auto and homeowners insurance with the same provider can shave 10% or more off the total premium. A family in Orlando who bundles both policies saved $250 annually.
- Safe Driver Programs
Telematics devices monitor driving habits; safe braking and consistent speeds can unlock discounts up to 15%. A senior driver in Sarasota who enrolled in a usage‑based program saw a $180 reduction.
- Affiliation Discounts
Membership in professional organizations, alumni groups, or employer networks often yields special rates. A teacher in Tallahassee receiving a 5% educator discount lowered the yearly cost to $1,350.
4. Common Mistakes to Avoid
Choosing the lowest quoted price without reviewing coverage limits can leave drivers under‑insured during a major accident. Skipping the optional uninsured motorist coverage, especially in Florida where uninsured drivers are prevalent, may result in out‑of‑pocket expenses exceeding the original savings.
Another frequent error is neglecting to update personal information after major life changes, such as moving to a different ZIP code or adding a teen driver. Failure to inform the insurer can invalidate discounts and trigger higher renewal rates.
5. Comparison Tools and Resources
- State‑Run Consumer Portals
The Florida Office of Insurance Regulation provides an online lookup tool that lists licensed carriers and complaint histories, aiding informed decision‑making.
- Independent Quote Aggregators
Websites like NerdWallet and The Zebra aggregate quotes from multiple insurers, allowing side‑by‑side comparison of price, coverage, and customer ratings.
- Agent Consultations
Local agents possess knowledge of regional risk factors and can tailor quotes to specific needs, such as flood‑prone vehicle storage solutions.
6. Impact of Credit Scores
Florida permits insurers to factor credit-based insurance scores into premium calculations. A driver with a score above 750 may receive a 5‑10% discount compared to a peer with a score of 620. Maintaining a strong credit profile, therefore, directly contributes to more favorable auto insurance quotes florida.
Credit improvement strategies, such as timely bill payments and reduced credit utilization, can gradually lower insurance costs, demonstrating the long‑term financial benefits of responsible credit management.
7. Renewal Strategies
When a policy term ends, reviewing the renewal notice is essential. Insurers often increase rates by 5‑15% based on inflation or claim trends. Proactively requesting a new quote before the renewal date can uncover better offers from competing carriers.
Setting a reminder to reassess coverage limits and deductible amounts during renewal can also optimize cost‑benefit balance. Raising the deductible from $500 to $1,000 typically reduces the premium by 7‑12%, provided the driver can afford the higher out‑of‑pocket expense in the event of a claim.
Frequently Asked Questions
Below are answers to common queries about auto insurance quotes florida.
Question 1: How many quotes should be obtained before deciding?
Gathering at least three distinct quotes provides a solid benchmark for price comparison, revealing variations in coverage options and insurer reputation. This range balances thoroughness with practicality, ensuring an informed choice without excessive time investment.
Question 2: Does Florida require specific minimum coverage?
Yes, the state mandates a minimum of $10,000 bodily injury per person, $20,000 per accident, and $10,000 property damage, plus Personal Injury Protection (PIP) of $10,000. Meeting these standards is essential for legal compliance and financial protection.
Question 3: Can a driver’s age affect auto insurance quotes florida?
Age influences risk assessment; younger drivers typically face higher premiums due to statistically higher accident rates, while senior drivers may receive discounts for experience but could see increased rates if age‑related health concerns arise.
Question 4: Are there discounts for electric vehicles?
Many insurers offer reduced rates for electric or hybrid vehicles, recognizing lower emissions and often lower repair costs. Eligibility varies, so checking with each provider ensures the discount is applied correctly.
Question 5: How does a clean driving record impact premiums?
A spotless record can lower premiums by up to 15%, as insurers view the driver as low risk. Maintaining defensive driving habits and avoiding traffic violations directly contributes to more favorable quotes.
Question 6: What role does vehicle mileage play in pricing?
Lower annual mileage typically results in reduced premiums because the vehicle spends less time on the road, decreasing exposure to accidents. Insurers may request odometer readings to adjust rates accordingly.
Tips
Implementing these actions can enhance the auto insurance quoting experience.
Tip 1: Review coverage annually. Reassessing limits and deductibles each year ensures alignment with changing needs and market conditions.
Tip 2: Maintain a high credit score. Consistent bill payments and low utilization improve credit‑based insurance scores, leading to lower quotes.
Tip 3: Bundle policies. Combining auto with home or renters insurance often yields multi‑policy discounts.
Tip 4: Use telematics wisely. Safe driving data from usage‑based programs can unlock significant savings.
Tip 5: Shop during off‑peak seasons. Purchasing after the summer travel surge may result in reduced rates.
Tip 6: Verify insurer’s financial strength. Selecting carriers with strong ratings ensures claim reliability.
Tip 7: Update address promptly. Relocating to a lower‑risk ZIP code can lower premiums immediately.
Tip 8: Inquire about affiliation discounts. Memberships in professional or alumni groups often qualify for special rates.
Tip 9: Consider higher deductibles. Raising deductibles can cut premiums, provided sufficient emergency funds exist.
Tip 10: Avoid unnecessary coverage. Removing duplicate or seldom‑used add‑ons reduces overall cost.
Tip 11: Ask about safe driver programs. Many insurers reward low‑incident records with discounts.
Tip 12: Compare quotes online. Aggregator platforms streamline side‑by‑side analysis of multiple carriers.
Tip 13: Check for loyalty incentives. Long‑term customers may receive renewal credits or reduced fees.
Tip 14: Review claim history. A clean claim record often translates to lower renewal premiums.
Tip 15: Consult a local agent. Regional expertise helps navigate state‑specific regulations and risk factors.
Conclusion
Exploring the intricacies of auto insurance quotes florida reveals a landscape shaped by state regulations, personal risk factors, and market competition. By understanding pricing dynamics, leveraging discounts, and avoiding common pitfalls, drivers can secure coverage that balances affordability with robust protection.
Continual monitoring of policy terms, credit health, and emerging discount programs ensures that future renewals remain cost‑effective, positioning motorists to adapt confidently to evolving insurance trends.

