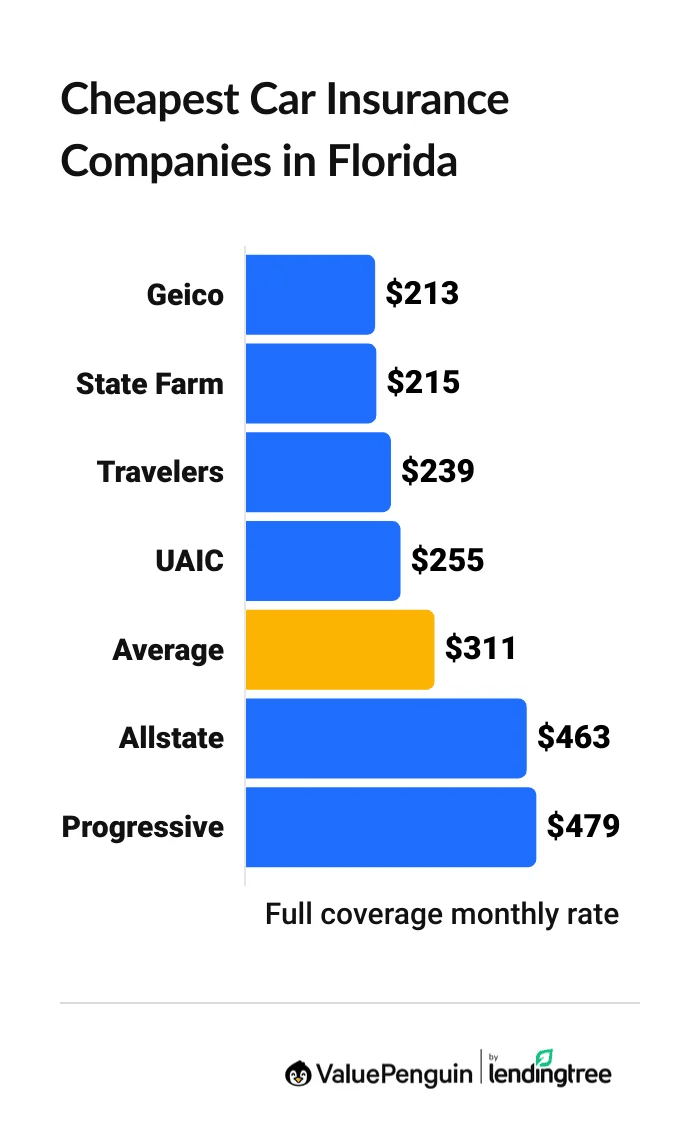
Getting an auto insurance quote fl is the first step toward affordable and reliable vehicle protection for Florida drivers. An auto insurance quote fl provides a personalized estimate of premium costs based on factors such as driving history, vehicle type, and coverage preferences. For example, a 30‑year‑old Miami resident with a 2018 Honda Civic might receive a quote of $1,150 annually after entering basic information online.
Understanding an auto insurance quote fl matters because it influences budgeting, legal compliance, and risk management. Florida law requires minimum bodily injury and property damage liability, yet many drivers overlook additional coverages that could save them from out‑of‑pocket expenses after a crash. Historically, Florida’s unique no‑fault system and frequent severe weather have shaped premium structures, making accurate quotes essential for financial planning.
This article breaks down the mechanics of obtaining a quote, the variables that affect pricing, common mistakes to avoid, and practical steps to secure the best rate. Readers will gain a clear roadmap for comparing providers, leveraging discounts, and optimizing coverage without overpaying.
1. Getting an auto insurance quote fl
Most insurers offer online tools that ask for zip code, vehicle details, driving record, and desired coverage limits. Inputting accurate data ensures the quote reflects real risk. After submission, a preliminary estimate appears, often within minutes, allowing quick comparison across multiple carriers.
2. Pricing dynamics
- Risk assessment
Insurers evaluate crash frequency, claim severity, and local weather patterns. In Tampa, higher hurricane exposure can raise premiums compared to inland areas. Understanding this helps drivers anticipate regional cost differences.
- Credit score impact
Florida regulators permit credit‑based insurance scoring. A driver with a strong credit history may see a 10‑15% discount, while poor credit can add hundreds to the quote. Monitoring credit reports can directly affect quote outcomes.
- Vehicle model
Safety features, repair costs, and theft rates influence rates. A 2022 Subaru Outback equipped with advanced driver‑assist systems often receives lower quotes than a high‑performance sports car.
- Driving habits
Mileage, usage type (commuting vs. leisure), and past violations shape the risk profile. A driver logging 8,000 miles annually with a clean record typically receives a more favorable quote than a high‑mileage driver with recent tickets.
- Policy bundling
Combining auto with homeowners or renters insurance can produce multi‑policy discounts, sometimes exceeding 20%. Many Florida families leverage this to lower overall insurance costs.
3. Common mistakes
Skipping the fine‑print on coverage limits often leads to underinsured situations. Selecting only the state‑mandated minimum may save money upfront but can expose drivers to substantial liability after a severe accident. Another frequent error is neglecting to disclose a vehicle’s safety upgrades, which can forfeit potential discounts.
Relying on a single quote instead of shopping around also hurts savings. Florida’s market is competitive; rates can vary dramatically between carriers like State Farm, GEICO, and local insurers such as Florida Farm Bureau. Regularly revisiting quotes each renewal cycle helps capture new discounts or market shifts.
4. Discounts and savings opportunities
- Safe driver programs
Many insurers reward drivers with a clean record over three years with a safe driver discount, often 5‑10% off the premium. For instance, a Jacksonville driver who avoided accidents for three consecutive years saw a $120 annual reduction.
- Defensive driving courses
Completing a state‑approved defensive driving course can shave 5% off the quote. The Florida Department of Highway Safety lists approved providers, and insurers typically verify completion electronically.
- Low mileage discounts
Driving fewer than 7,500 miles per year may qualify for a low‑mileage discount, reflecting reduced exposure to accidents. A Tallahassee commuter who switched to remote work earned a $80 discount.
- Vehicle safety tech
Features like automatic emergency braking, lane‑keep assist, and anti‑theft devices often trigger manufacturer‑specific discounts, sometimes up to 15%.
- Loyalty rewards
Long‑term policyholders may receive loyalty credits, though these should be weighed against potentially better rates from new providers.
\n
5. How to compare quotes effectively
Beyond price, evaluate coverage limits, deductibles, and exclusions. A lower premium may accompany higher deductibles, which could strain finances after a claim. Use a comparison spreadsheet to track each insurer’s total cost, discount stack, and customer service ratings from J.D. Power or the Better Business Bureau.
Consider the insurer’s claims handling reputation. Florida’s hurricane season often triggers surge claims; carriers with robust claims infrastructure, such as Allstate’s “Claims Fast Track,” can provide faster settlements, reducing stress for policyholders.
6. Role of agents and digital platforms
Independent agents can access multiple carrier rates, offering a broader view than single‑company websites. They also assist with nuanced questions about Florida’s no‑fault law and personal injury protection (PIP) requirements. Digital platforms, however, deliver instant quotes and allow quick policy adjustments, appealing to tech‑savvy consumers.
Choosing between an agent and an online portal depends on personal preference. Drivers seeking customized advice may benefit from a licensed Florida agent, while those comfortable with self‑service can save time with platforms like The Zebra or Insurify.
7. Renewal and policy adjustments
At renewal, insurers often propose new rates based on recent claim history and market trends. Reviewing the auto insurance quote fl before accepting the renewal can reveal opportunities to switch carriers or negotiate better terms. Adjusting coverage limits, adding new discounts, or updating vehicle information are common tactics to lower the next year’s premium.
Life changes—such as moving to a different county, adding a teen driver, or purchasing a new car—necessitate a fresh quote. Proactively requesting an updated estimate ensures the policy stays aligned with risk exposure and budget constraints.
Frequently Asked Questions
Below are common inquiries about obtaining and optimizing an auto insurance quote fl.
Question 1: How does Florida’s no‑fault law affect my quote?
Florida’s no‑fault system requires Personal Injury Protection (PIP) coverage, which adds to the base premium. Insurers factor the mandatory $10,000 PIP minimum when calculating rates, so higher PIP limits will increase the quote proportionally.
Question 2: Can I get a lower quote by increasing my deductible?
Yes, raising the deductible reduces the insurer’s risk, often lowering the premium by 5‑15%. However, the higher out‑of‑pocket expense during a claim must be affordable for the driver.
Question 3: Are there specific discounts for senior drivers in Florida?
Many carriers offer senior discounts for drivers over 65 with clean records, typically ranging from 5% to 10%. Additional savings may apply for low mileage or bundled policies.
Question 4: How often should I request a new auto insurance quote fl?
Requesting a fresh quote annually, especially before renewal, helps capture new discounts, market changes, and personal life updates that could affect pricing.
Question 5: Does my credit score really impact the quote?
In Florida, insurers may use credit‑based insurance scores. A higher credit rating can reduce premiums, while a lower score may add several hundred dollars to the annual cost.
Question 6: What is the best way to verify an insurer’s claim handling reputation?
Consult independent ratings from J.D. Power, Consumer Reports, and the Better Business Bureau. Reading recent customer reviews also provides insight into claim processing speed and satisfaction.
9 actionable tips for auto insurance quote fl
Tip 1: Verify vehicle details. Ensure make, model, VIN, and safety features are entered accurately to avoid inflated premiums.
Tip 2: Update mileage. Report current annual mileage; lower usage often yields discounts.
Tip 3: Check credit reports. Clean up errors and improve scores before requesting a quote.
Tip 4: Bundle policies. Combine auto with home or renters insurance to unlock multi‑policy savings.
Tip 5: Leverage safe driver programs. Enroll in insurer‑offered programs that reward accident‑free years.
Tip 6: Complete a defensive driving course. Obtain certification and submit proof for an immediate discount.
Tip 7: Review coverage limits. Adjust liability and PIP amounts to match personal risk tolerance without overpaying.
Tip 8: Compare at least three carriers. Use comparison sites and agents to gather a broad range of quotes.
Tip 9: Re‑quote after major life changes. Update your policy after moving, adding drivers, or purchasing a new vehicle.
Conclusion
The auto insurance quote fl process hinges on accurate data, understanding of Florida’s unique insurance landscape, and strategic use of discounts. By dissecting pricing dynamics, avoiding common pitfalls, and comparing offers methodically, drivers can secure comprehensive coverage at competitive rates.
Staying proactive—regularly re‑quoting, monitoring credit, and adjusting coverage—ensures long‑term savings and peace of mind as Florida’s roads and weather evolve.

