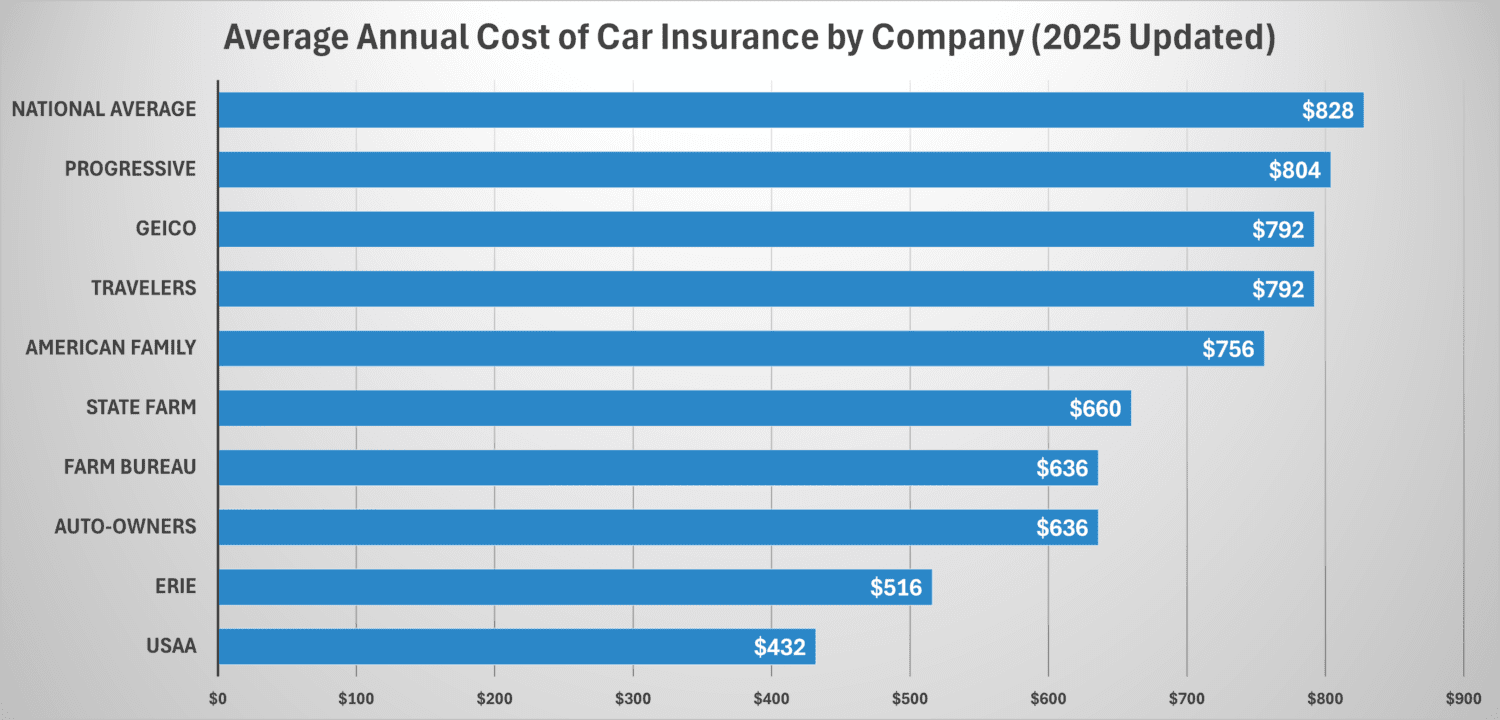
auto insurance price compare refers to the systematic process of evaluating multiple auto insurance policies to determine the most cost‑effective option for a specific driver profile. For instance, a 30‑year‑old driver in Ohio might obtain three quotes from State Farm, Geico, and Progressive, then analyze premiums, deductibles, and coverage limits to select the optimal plan.
This practice holds significant importance because automobile insurance represents a substantial recurring expense, and even modest premium differences can translate into considerable annual savings. Historically, the rise of online aggregators in the early 2000s democratized access to quote data, enabling consumers to move beyond reliance on single‑agent recommendations.
The following sections explore key factors influencing pricing, common pitfalls, effective comparison techniques, and actionable strategies that empower drivers to make informed decisions without overspending.
1. Understanding Pricing Dynamics
Premium calculations blend actuarial data with personal risk indicators such as driving history, vehicle type, and geographic location. A higher accident frequency typically raises rates, while low‑mileage usage can lower them. Insurers also adjust prices based on broader market trends, including fuel price volatility and legislative changes affecting claim costs.
Recognizing these cause‑and‑effect relationships helps drivers anticipate how lifestyle adjustments—like enrolling in a defensive driving course—might reduce future premiums.
2. Using Comparison Tools Effectively
- Tool Selection
Choosing a reputable aggregator, such as NerdWallet or The Zebra, ensures accurate quote retrieval. These platforms pull data directly from carrier databases, reducing manual entry errors. A driver who previously relied on a single insurer’s portal discovered a 12% lower rate after switching to an aggregator.
- Input Consistency
Maintaining identical information across all quote requests—same vehicle identification number, mileage, and coverage limits—produces comparable results. Inconsistent inputs can distort apparent price differences, leading to misguided conclusions.
- Filter Application
Applying filters for desired coverage types (liability, collision, comprehensive) narrows results to relevant options. A driver seeking only liability coverage avoided unnecessary premium inflation by excluding optional add‑ons during the search.
- Review of Exclusions
Examining policy exclusions, such as rental reimbursement limits, reveals hidden cost drivers. One example involved a policy that excluded roadside assistance, prompting the driver to add a separate service for a modest extra fee.
- Rating Comparison
Beyond price, evaluating insurer ratings from agencies like AM Best or J.D. Power provides insight into claim satisfaction and financial stability. A lower‑priced policy from a poorly rated carrier may pose higher long‑term risk.
3. Discount Opportunities
- Multi‑Policy Bundle
Combining auto and home insurance with the same carrier often yields a 10‑15% discount. A family in Texas saved $200 annually by bundling policies with Allstate.
- Safe Driver Programs
Telematics devices that monitor driving behavior can unlock safe driver discounts up to 20%. A teenager’s gradual improvement in braking patterns resulted in a substantial premium reduction after six months.
- Affiliation Savings
Membership in professional organizations, alumni associations, or credit unions frequently grants exclusive rate reductions. An accountant affiliated with a state bar association received a 7% discount from a regional insurer.
- Low Mileage Credits
Driving fewer than 7,500 miles per year can qualify for mileage‑based discounts. A remote worker commuting only on weekends benefited from a $150 annual credit.
- Loyalty Rebates
Long‑term policyholders sometimes receive loyalty rebates, though these may be offset by higher base rates. A driver who remained with the same insurer for ten years negotiated a modest rebate after reviewing competitor offers.
4. Coverage Levels and Their Impact
Choosing appropriate coverage limits directly influences premium amounts. Higher liability limits protect against costly lawsuits but increase the price tag. Conversely, minimal coverage may satisfy legal minimums yet expose drivers to financial vulnerability.
Balancing deductible amounts also affects cost; a higher deductible reduces monthly premiums but raises out‑of‑pocket expense in the event of a claim. Drivers must assess risk tolerance when adjusting these parameters.
5. State Regulations and Market Variations
- Mandatory Minimums
Each state enforces distinct minimum liability requirements. In California, the 15/30/5 rule differs from Michigan’s no‑fault system, leading to varying baseline premiums across jurisdictions.
- Rating Factors
Regulatory bodies dictate permissible rating factors; some states prohibit gender or credit‑score usage. This restriction can narrow price differentials, as observed in Florida where credit‑based pricing is limited.
- Market Competition
States with multiple carriers, such as Pennsylvania, often experience tighter pricing competition, resulting in lower average premiums compared to monopolistic markets like Hawaii.
- Regional Risk Pools
Areas prone to natural disasters—e.g., tornado‑heavy Oklahoma—incur higher comprehensive rates due to increased claim likelihood. Drivers in such regions should weigh additional coverage against elevated costs.
- Legislative Changes
New legislation, such as mandatory uninsured motorist coverage, can shift pricing structures overnight. Monitoring state insurance department releases helps anticipate upcoming premium adjustments.
6. Timing and Renewal Strategies
Premiums fluctuate throughout the year, often peaking during renewal windows. Initiating a price compare process 30‑45 days before policy expiration maximizes bargaining power and allows ample time to secure better rates.
Some insurers offer “early‑bird” discounts for renewing ahead of schedule, while others provide “loyalty lock” rates for long‑term customers. Evaluating these options alongside competitor quotes ensures the most advantageous outcome.
7. auto insurance price compare Best Practices
Adopting a disciplined approach to auto insurance price compare yields consistent savings. Maintaining an up‑to‑date driving record, regularly reviewing coverage needs, and leveraging technology-driven discount programs form the foundation of a successful strategy.
Periodic reassessment—at least annually—captures market shifts and life‑event changes such as vehicle upgrades or relocation, preventing over‑paying for unnecessary coverage.
Frequently Asked Questions
Quick answers to common inquiries about comparing auto insurance prices.
Question 1: How often should drivers review auto insurance quotes?
Annual reviews align with policy renewal cycles and capture market fluctuations, while major life changes—such as moving or purchasing a new vehicle—warrant immediate re‑evaluation to ensure continued cost‑effectiveness.
Question 2: Do online aggregators guarantee the lowest possible price?
Aggregators provide extensive market visibility but may exclude niche carriers or exclusive discounts offered directly by insurers. Cross‑checking a few carrier‑specific quotes can uncover additional savings.
Question 3: Which factors most heavily influence premium calculations?
Driving record, vehicle model, geographic location, age, and selected coverage limits dominate premium formulas. Secondary influences include credit scores (where permitted) and mileage patterns.
Question 4: Can bundling policies always reduce overall costs?
Bundling frequently yields discounts, yet the combined total may still exceed the sum of individually optimized policies. Conducting a side‑by‑side price compare determines the true financial benefit.
Question 5: Are higher deductibles always a better way to lower premiums?
Higher deductibles reduce monthly payments but increase out‑of‑pocket risk during claims. Drivers with sufficient emergency funds may benefit, whereas those on tight budgets might prefer lower deductibles despite higher premiums.
Question 6: How do state regulations affect auto insurance price compare?
State‑mandated minimums, permissible rating factors, and regional risk assessments shape baseline pricing. Understanding local legal requirements prevents inaccurate comparisons and ensures compliance.
Tips for Smarter Auto Insurance Price Compare
Effective guidelines help maximize savings and coverage quality.
Tip 1: Gather Complete Vehicle Data. Accurate VIN, mileage, and usage details ensure comparable quotes across carriers.
Tip 2: Standardize Coverage Limits. Use identical liability and comprehensive limits when requesting estimates to avoid skewed results.
Tip 3: Update Driving Record Annually. Removing old violations can lower risk scores and improve premium offers.
Tip 4: Leverage Telematics Programs. Enroll in usage‑based insurance to qualify for behavior‑driven discounts.
Tip 5: Explore Multi‑Policy Bundles. Combine auto with home or renters insurance to unlock bundled rate reductions.
Tip 6: Check Affiliation Discounts. Memberships in professional groups or alumni networks often provide exclusive pricing.
Tip 7: Review State Minimum Requirements. Ensure selected coverage meets legal standards while avoiding unnecessary excess.
Tip 8: Compare Deductible Options. Model premium impacts across several deductible levels before finalizing.
Tip 9: Assess Insurer Financial Strength. Favor carriers with strong ratings to safeguard claim reliability.
Tip 10: Read Policy Exclusions Carefully. Identify any omitted coverages that could lead to unexpected out‑of‑pocket costs.
Tip 11: Time Renewal Requests Strategically. Initiate price compare 30‑45 days before policy expiration for optimal leverage.
Tip 12: Monitor Legislative Changes. Stay informed on new insurance mandates that may affect premium structures.
Tip 13: Use Multiple Comparison Platforms. Cross‑reference results from at least two aggregators to capture the full market spectrum.
Tip 14: Negotiate Directly with Carriers. Armed with competitor quotes, request personalized discounts from preferred insurers.
Tip 15: Document Savings Decisions. Keep a record of chosen policies, discounts applied, and renewal dates for future reference.
Conclusion
Understanding pricing dynamics, leveraging comparison tools, and capitalizing on discount opportunities constitute the core of effective auto insurance price compare practices. By aligning coverage needs with market realities, drivers can secure financially sound protection without overpaying.
Continual monitoring of regulatory shifts, renewal timing, and emerging discount programs ensures that future insurance decisions remain both strategic and economical.

