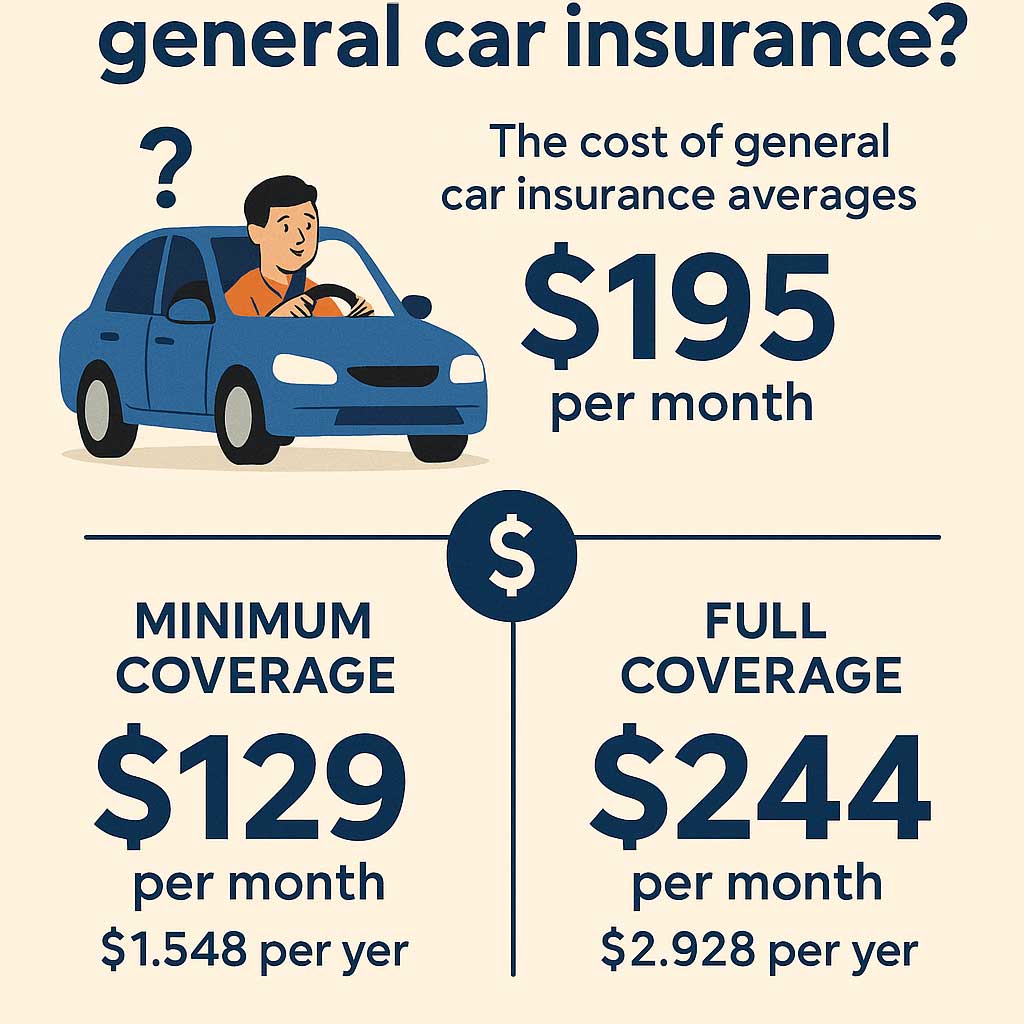
auto insurance how much is a question that surfaces whenever a driver evaluates financial protection for a vehicle. For example, a 30‑year‑old commuter in Chicago might see a quoted premium of $1,200 per year for a standard liability policy with collision coverage.
Understanding the cost of auto insurance matters because it directly influences household budgeting, risk management, and compliance with state law. Historically, premiums have shifted with legislation, accident trends, and advances in telematics, making the pricing landscape both dynamic and personal.
This article breaks down the components that shape auto insurance costs, highlights common pricing pitfalls, outlines discount opportunities, and provides forward‑looking insights to help readers make informed decisions.
1. auto insurance how much Explained
At its core, auto insurance cost reflects a blend of actuarial data, personal risk factors, and regulatory requirements. Insurers assess the probability of a claim based on driving history, vehicle characteristics, and geographic risk zones. The resulting premium aims to cover expected losses while providing a profit margin.
Factors such as age, credit score, and mileage further refine the estimate. For instance, a driver with a clean record but high annual mileage may pay more than a low‑mileage driver with a minor accident on record.
2. Pricing Dynamics
- Base Rate
The foundational price set by the insurer, derived from industry loss data. A driver in a low‑claim region may start with a lower base rate, reducing overall cost.
- Risk Profile
Individual driving behavior, including ticket history and claims frequency. A recent speeding ticket can increase the premium by 10‑15 percent.
- Location
Urban areas typically generate higher premiums due to congestion and theft rates. A resident of Los Angeles often pays more than a rural counterpart.
- Vehicle Type
Cars with advanced safety features or lower repair costs attract discounts, whereas sports cars command higher rates.
- Coverage Level
Choosing higher liability limits or adding comprehensive coverage raises the premium but expands protection.
3. Common Mistakes
- Underinsuring
Selecting minimum liability limits to save money can lead to substantial out‑of‑pocket expenses after a severe accident.
- Ignoring Discounts
Many drivers overlook multi‑policy, safe driver, or low‑mileage discounts, missing potential savings of up to 25 percent.
- Letting Lapses Occur
Allowing a policy to lapse and then reinstating it often results in higher rates due to perceived risk.
- Failing to Update Information
Neglecting to report a new vehicle or a change in address can keep the premium higher than necessary.
4. Discount Opportunities
Insurers reward behaviors that reduce risk. Installing an anti‑theft device, completing a defensive driving course, or maintaining a high credit score can each shave a notable percentage from the quoted amount. Bundling auto coverage with homeowners or renters insurance also creates a multi‑policy discount, often ranging between 5 and 15 percent.
Paying the annual premium in full rather than monthly installments eliminates administrative fees, further lowering the total expense.
5. State Regulations Impact
- Minimum Liability Requirements
Each state mandates a baseline coverage level, influencing the floor price for policies.
- No‑Fault Laws
States with no‑fault statutes may see higher premiums due to broader claim eligibility.
- Rating Factors
Some jurisdictions prohibit the use of credit scores or gender in pricing, altering the premium composition.
- Surge Pricing Zones
Areas designated as high‑risk zones, such as flood‑prone coastal regions, often carry additional surcharge clauses.
6. Choosing the Right Policy
Balancing cost against coverage depth requires a clear assessment of personal risk tolerance. A driver who frequently travels long distances may prioritize collision and comprehensive coverage, while a short‑commute driver might lean toward liability‑only plans.
Comparing quotes from multiple carriers, reviewing policy exclusions, and evaluating the insurer’s claim handling reputation are essential steps to ensure value aligns with expense.
7. Future Trends in Pricing
Telematics and usage‑based insurance are reshaping how premiums are calculated. Real‑time driving data, such as hard braking frequency, allows insurers to reward safe habits with dynamic discounts.
Artificial intelligence models are also improving loss prediction accuracy, potentially stabilizing rates across market cycles. Staying informed about these innovations can help drivers anticipate shifts in auto insurance how much may be charged in the coming years.
Frequently Asked Questions
Quick answers to common queries about auto insurance cost.
Question 1: What determines the base price of an auto insurance policy?
Base price is set by the insurer using industry loss data, adjusted for regional risk factors, vehicle type, and overall market conditions. It serves as the starting point before personal risk modifiers are applied.
Question 2: How can mileage affect auto insurance premiums?
Higher annual mileage increases exposure to accidents, prompting insurers to raise premiums proportionally. Low‑mileage drivers often qualify for discounts ranging from 5 to 15 percent.
Question 3: Are there benefits to bundling auto and home insurance?
Bundling typically yields a multi‑policy discount, reducing the combined cost by 5‑15 percent. It also simplifies management by consolidating billing and policy renewal dates.
Question 4: Does a clean driving record guarantee the lowest rates?
A clean record is a strong factor, but premiums also depend on credit score, vehicle model, location, and selected coverage limits. Comprehensive evaluation yields the most accurate quote.
Question 5: What impact do state regulations have on premium amounts?
State‑mandated minimum coverage, no‑fault rules, and restrictions on rating factors directly influence the floor and ceiling of premiums, causing regional price variations.
Question 6: How does usage‑based insurance work?
Usage‑based programs install a telematics device or app that monitors driving behavior. Safe driving habits generate discounts, while risky patterns can increase the premium for the covered period.
Tips
Tip 1: Review policy annually. Market rates shift, and a yearly audit can reveal cheaper alternatives.
Tip 2: Increase deductibles. Raising the deductible lowers the premium, but ensures sufficient emergency funds are available.
Tip 3: Maintain a high credit score. Creditworthiness remains a key pricing factor in many states.
Tip 4: Install safety technology. Anti‑theft devices and advanced driver‑assist systems often qualify for discounts.
Tip 5: Consolidate policies. Bundling with home or renters insurance streamlines billing and reduces overall cost.
Tip 6: Ask about loyalty rewards. Long‑term customers may receive rate reductions or added benefits.
Tip 7: Compare at least three quotes. Competitive shopping uncovers hidden savings across carriers.
Tip 8: Opt for electronic statements. Some insurers lower premiums for paper‑free communication.
Conclusion
Auto insurance cost is shaped by a complex interplay of personal risk factors, vehicle attributes, geographic considerations, and regulatory environments. By dissecting pricing dynamics, avoiding common errors, and leveraging discounts, drivers can achieve a balanced blend of coverage and affordability.
Staying attuned to emerging telematics trends and regularly revisiting policy choices ensures that future auto insurance how much remains manageable and aligned with evolving needs.

