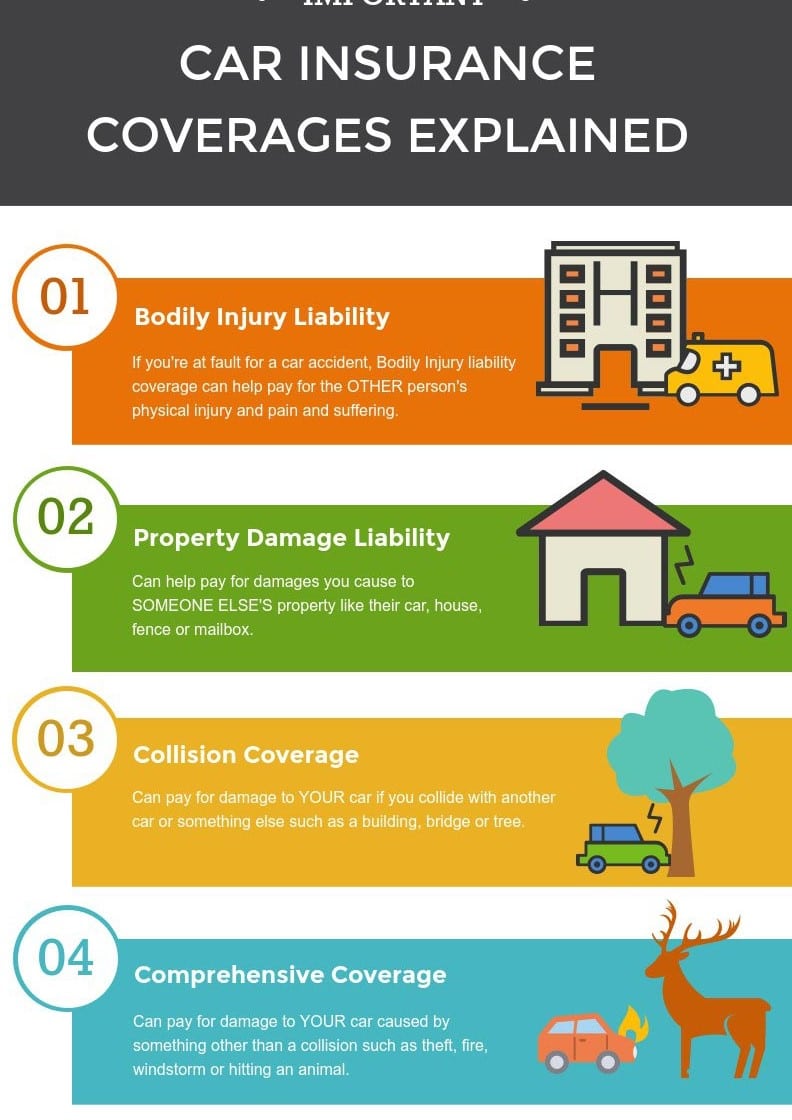
Auto insurance coverages explained help drivers understand the specific protections their policies provide, such as a collision clause that pays for repairs after a fender‑bender. For instance, a driver in Texas who crashes into a parked car can claim under the collision coverage to cover repair costs, while the other driver’s liability coverage handles their damages.
Understanding these coverages is crucial because it determines financial security after accidents, theft, or natural disasters, and influences premium costs. Historically, auto insurance evolved from simple liability policies in the early 1900s to today’s multi‑layered packages that address a wide range of risks.
This article breaks down the core components of auto insurance, compares optional add‑ons, and offers actionable advice for selecting the best mix of protection.
1. Auto Insurance Coverages Explained
This section outlines the foundational policies that appear on most declarations pages, clarifying their purpose and typical limits.
- Liability Coverage
Protects against bodily injury and property damage claims from other parties. Example: A driver at a stoplight runs a red light, causing injury; liability pays the medical bills. It’s mandatory in most states and forms the backbone of any policy.
- Collision Coverage
Covers repair or replacement of the insured vehicle after a crash, regardless of fault. Example: A rear‑end collision on the highway triggers a claim to fix the bumper. It reduces out‑of‑pocket expenses for accident repairs.
- Comprehensive Coverage
Handles non‑collision events like theft, fire, or hail. Example: A car stolen from a parking garage is reimbursed up to its actual cash value. It broadens protection beyond road accidents.
- Uninsured/Underinsured Motorist
Provides compensation when the at‑fault driver lacks sufficient insurance. Example: An uninsured driver hits a cyclist; this coverage pays for medical costs. It safeguards against gaps in others’ policies.
- Medical Payments (MedPay)
Covers medical expenses for the driver and passengers, regardless of fault. Example: A passenger suffers a whiplash injury; MedPay covers the ER visit. It offers quick, low‑deductible reimbursement.
2. Policy Limits and Deductibles
Limits define the maximum payout an insurer will make for a claim, while deductibles are the out‑of‑pocket amount the policyholder must pay before coverage kicks in. Higher limits provide greater financial protection but raise premiums; lower deductibles reduce immediate costs after a claim but can increase the overall price of the policy. Balancing these factors depends on vehicle value, driving habits, and risk tolerance.
For example, a high‑value sports car often warrants a $250,000 bodily injury limit and a $1,000 deductible on collision to protect against costly repairs while keeping monthly costs manageable.
3. Optional Add‑Ons and Riders
- Roadside Assistance
Offers services like towing, lockout help, and fuel delivery. Example: A driver stranded on a rural road receives a tow to the nearest garage, avoiding a costly private tow.
- Rental Reimbursement
Covers the cost of a rental car while the insured vehicle is repaired. Example: After a collision, the policy pays for a week’s rental, preventing disruption to daily routines.
- Gap Insurance
Pays the difference between the car’s actual cash value and the remaining loan balance if the vehicle is totaled. Example: A driver with a $20,000 loan on a $15,000 car receives the $5,000 shortfall from the insurer.
These riders enhance convenience and financial safety but add to the premium, so evaluating their relevance to personal circumstances is essential.
4. State Regulations and Minimum Requirements
Each state sets its own minimum liability thresholds, influencing the baseline coverage a driver must carry. For instance, California requires $15,000 per person for bodily injury, whereas Florida mandates $10,000 for property damage only. Understanding local statutes prevents legal penalties and ensures compliance.
Drivers who frequently travel across state lines should consider purchasing higher limits than the minimum to avoid gaps when crossing into jurisdictions with stricter requirements.
5. Factors Influencing Premiums
- Driving Record
Clean records typically earn discounts; accidents or tickets raise rates. Example: A driver with no tickets for three years may receive a 10% safe driver discount.
- Vehicle Type
Sports cars and luxury models attract higher premiums due to repair costs and theft risk. Example: Insuring a Tesla Model S costs more than a Toyota Corolla.
- Geographic Location
Urban areas with higher traffic density often have elevated rates. Example: A driver in Manhattan pays more than one in a rural Midwest town.
- Credit Score
Many insurers use credit-based insurance scores to assess risk. Example: A strong credit rating can shave 5‑15% off the premium.
Understanding these variables enables drivers to make informed choices, such as opting for a higher deductible to lower the overall premium.
6. Claims Process Overview
When a loss occurs, the claims process typically begins with reporting the incident to the insurer, providing documentation (photos, police reports), and cooperating with an adjuster. Prompt filing can accelerate settlement and reduce the chance of disputes.
For example, after a minor fender‑bender, a driver submits photos of the damage via the insurer’s mobile app, receives an adjuster’s estimate within 48 hours, and gets the repair authorized, minimizing vehicle downtime.
Frequently Asked Questions
Quick answers to common queries about auto insurance coverages.
Question 1: What is the difference between liability and collision coverage?
Liability covers damages you cause to others, while collision pays for repairs to your own vehicle after an accident, regardless of fault. Both serve distinct purposes and are often required together for comprehensive protection.
Question 2: Is comprehensive coverage necessary for a new car?
Comprehensive protects against non‑collision events like theft, fire, or natural disasters. For a new car with a high market value, it is advisable to maintain comprehensive to safeguard the investment against a broader range of risks.
Question 3: How does a deductible affect my premium?
Higher deductibles lower the premium because the insurer assumes more risk. Conversely, a low deductible raises the premium but reduces out‑of‑pocket costs when a claim is filed. Balance based on financial comfort.
Question 4: Can I add roadside assistance to any policy?
Most insurers offer roadside assistance as an optional rider on standard auto policies. Availability and cost vary, so review the provider’s options to determine if it fits the driver’s needs.
Question 5: What is gap insurance and when is it useful?
Gap insurance covers the difference between a vehicle’s actual cash value and the remaining loan balance if the car is totaled. It is especially useful for financed or leased vehicles where the loan exceeds the car’s depreciation.
Question 6: How often should coverage limits be reviewed?
Review limits at major life events—such as buying a new car, moving states, or changes in household income—at least annually. Adjusting limits ensures adequate protection and can optimize premium costs.
Tips for Maximizing Your Auto Insurance
Practical steps to get the most out of coverage.
Tip 1: Compare multiple quotes. Use online aggregators to evaluate rates from at least three insurers before deciding.
Tip 2: Bundle policies. Combine auto with home or renters insurance for multi‑policy discounts.
Tip 3: Maintain a clean driving record. Safe driving habits directly lower premium calculations.
Tip 4: Increase your deductible. Raising it by $200‑$500 can reduce the monthly cost substantially.
Tip 5: Ask about loyalty discounts. Long‑term customers often qualify for reduced rates.
Tip 6: Review annual mileage. Lower mileage can qualify for usage‑based discounts.
Tip 7: Install safety devices. Anti‑theft alarms and driver‑assist tech may lower premiums.
Tip 8: Keep credit healthy. A strong credit score can shave off a noticeable percentage of the premium.
Tip 9: Opt for electronic statements. Some insurers reward paperless billing with small discounts.
Tip 10: Reassess after major purchases. New vehicles or added drivers warrant a coverage review.
Tip 11: Utilize usage‑based programs. Telemetry apps can reward low‑risk driving patterns.
Tip 12: Eliminate unnecessary riders. Remove coverage you don’t need, like rental reimbursement if you rarely rent.
Tip 13: Check for group rates. Employer or alumni associations sometimes offer special pricing.
Tip 14: Update address promptly. Relocating can affect rates; ensure the insurer has the correct location.
Tip 15: Review claim history. Frequent claims may increase premiums; consider self‑pay for minor incidents.
Tip 16: Ask about accident forgiveness. Some carriers waive the first at‑fault accident’s impact on premiums.
Conclusion
Auto insurance coverages explained reveal a layered system of mandatory and optional protections that together safeguard drivers, passengers, and assets. By understanding liability, collision, comprehensive, and additional riders, and by managing limits, deductibles, and premium influencers, informed decisions lead to optimal coverage and cost efficiency.
Staying proactive—regularly reviewing policies, leveraging discounts, and adapting to life changes—ensures that protection evolves alongside driving needs, keeping both the vehicle and the driver secure for the road ahead.

