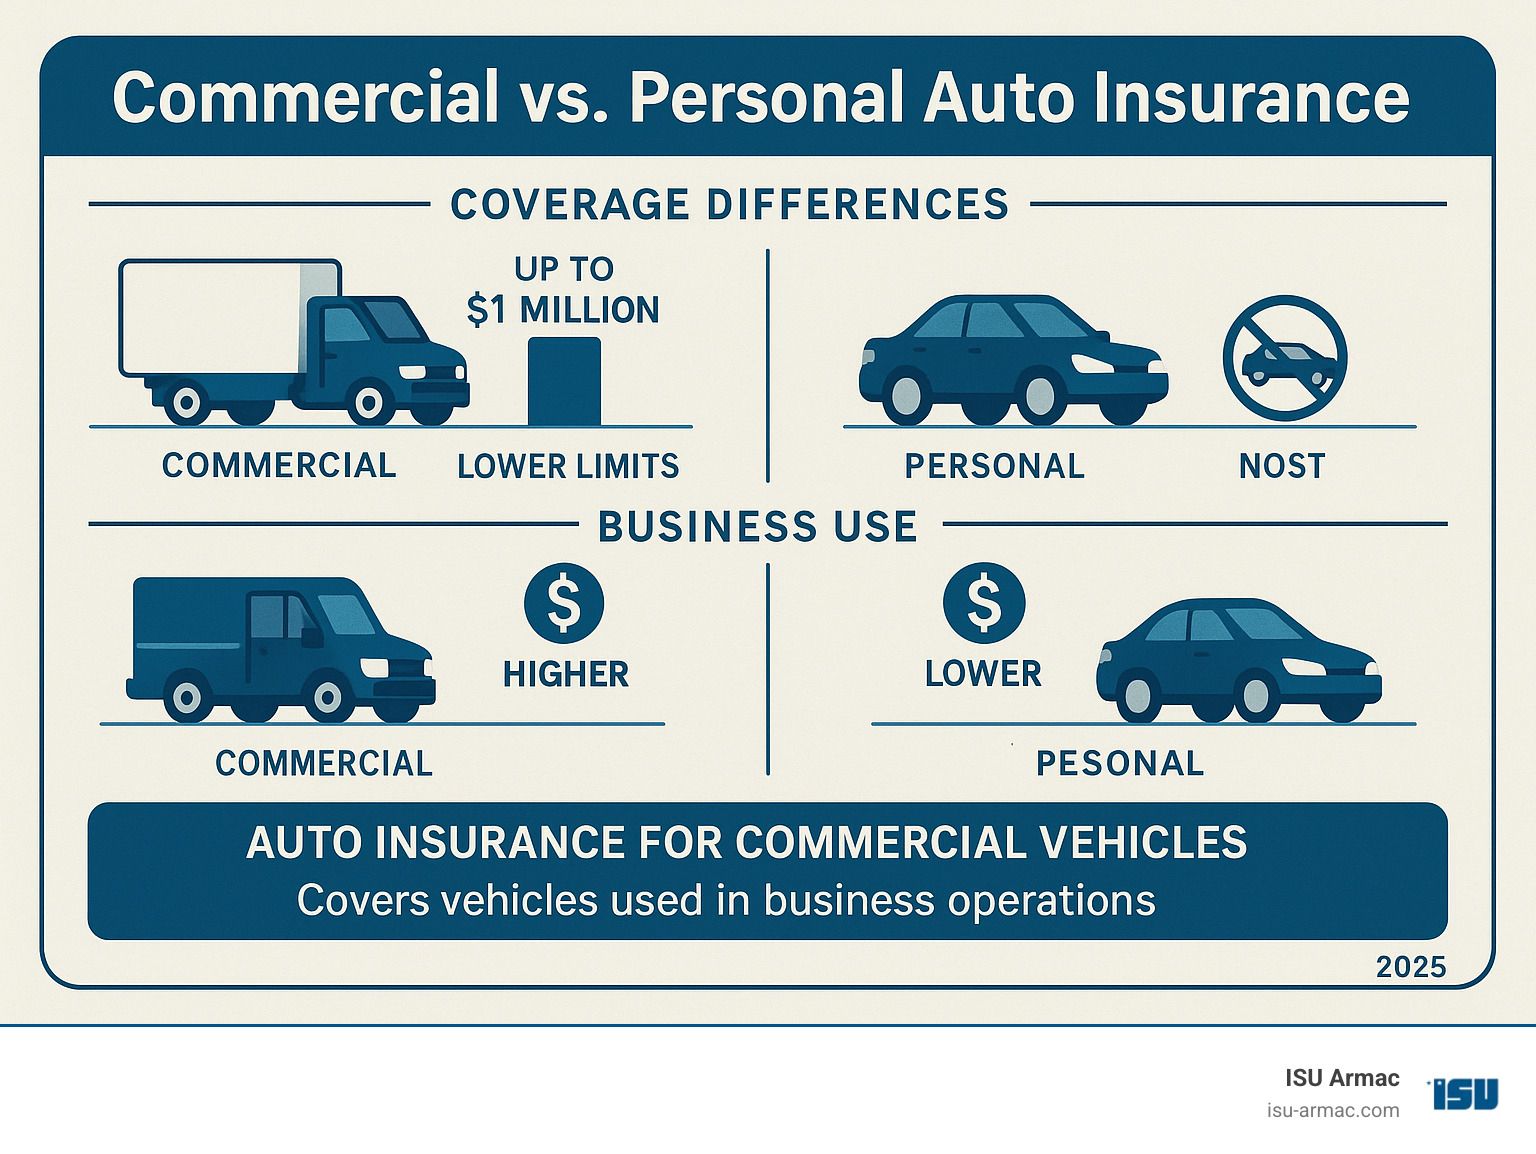
Auto insurance commercial vehicles is a specialized form of coverage that protects business‑owned automobiles against liability, physical damage, and operational interruptions. For example, a delivery company that operates a fleet of refrigerated trucks relies on this policy to safeguard each vehicle, its drivers, and the cargo they transport.
Such insurance is vital because commercial vehicles face higher exposure to accidents, cargo loss, and regulatory scrutiny than personal cars. Historically, the growth of logistics and ride‑sharing services has driven insurers to develop tailored products that address the unique risk profile of business fleets.
The following sections explore pricing dynamics, coverage nuances, regulatory requirements, claim handling, risk mitigation, and emerging trends, providing a comprehensive roadmap for fleet managers and owners.
1. Pricing Dynamics
Premiums for auto insurance commercial vehicles are influenced by vehicle type, usage patterns, driver records, and geographic exposure. Heavy‑duty trucks in urban centers typically command higher rates due to congestion and theft risk.
- Vehicle Classification
Insurers categorize trucks, vans, and specialty rigs differently; a box truck hauling furniture may be priced lower than a refrigerated trailer because of cargo value considerations.
- Mileage and Routes
Higher annual mileage and routes that cross state lines increase exposure, prompting carriers like UPS to negotiate volume discounts based on predictable routing.
- Driver Experience
Companies that implement rigorous driver training see reduced accident frequencies, leading to lower per‑vehicle rates, as demonstrated by a regional plumbing firm that cut premiums by 15% after adopting a defensive‑driving program.
- Safety Technology
Installation of telematics, collision‑avoidance systems, and dash cams provides real‑time data, allowing insurers to reward safe behavior with usage‑based discounts.
- Claims History
A clean loss record over three years can unlock multi‑policy discounts, encouraging businesses to adopt proactive risk‑management practices.
2. Coverage Types and Limits
Auto insurance commercial vehicles typically bundles liability, physical‑damage, and cargo protection. Liability covers bodily injury and property damage to third parties, while physical‑damage includes collision and comprehensive coverage for the insured vehicle.
Cargo insurance is optional but essential for high‑value freight; a florist delivering bouquets across state lines may add a $100,000 cargo endorsement to protect against spoilage or theft.
Limits are set per incident and aggregate annually; larger fleets often select higher aggregate limits to avoid caps that could leave the business exposed during a series of claims.
3. Regulatory and Legal Requirements
State statutes dictate minimum liability limits for commercial auto operations. For instance, California requires $750,000 per accident for bodily injury, while Texas mandates $100,000 per person and $300,000 per accident.
Federal regulations, such as the FMCSA’s hazardous‑material rules, impose additional insurance thresholds for carriers transporting dangerous goods. Failure to meet these mandates can result in fines, license suspensions, or loss of contracts.
4. Claims Process and Management
Efficient claims handling minimizes downtime and financial loss. Companies that employ a dedicated claims coordinator can streamline documentation, negotiate repair estimates, and expedite settlements.Real‑world example: A construction firm experienced a multi‑vehicle accident on a job site; their insurer’s 24‑hour hotline facilitated immediate tow services and arranged temporary replacements, reducing operational disruption by three days.
Key steps include prompt incident reporting, accurate police reports, photographic evidence, and thorough driver statements. Insurers may also request maintenance logs to verify that the vehicle was properly serviced.
5. Risk Mitigation Strategies
- Driver Training Programs
Structured curricula covering defensive driving, load securement, and fatigue management lower accident rates, as evidenced by a logistics carrier that achieved a 22% reduction in claim frequency after implementing quarterly workshops.
- Vehicle Maintenance Schedules
Adhering to OEM service intervals prevents mechanical failures; a municipal fleet that switched to predictive maintenance saw a 30% drop in breakdown‑related claims.
- Telematics Monitoring
Real‑time tracking of speed, harsh braking, and route deviation enables managers to intervene before risky behavior escalates, improving overall safety scores.
- Load Securement Practices
Properly fastening cargo reduces shift‑related accidents; a beverage distributor that introduced standardized tie‑down protocols reported fewer cargo‑damage claims.
- Insurance Audits
Annual policy reviews identify coverage gaps and ensure limits align with fleet growth, preventing under‑insurance scenarios.
6. Emerging Trends and Technologies
Autonomous vehicle pilots are reshaping commercial auto insurance, shifting focus from driver liability to system malfunction risk. Early adopters like Amazon’s delivery fleet are working with insurers to develop cyber‑risk endorsements for autonomous software failures.
Electric trucks introduce new considerations, such as battery coverage and charging‑station liability. Insurers are crafting specialized endorsements to address fire risk and depreciation of high‑cost battery packs.
Usage‑based insurance (UBI) models leverage big data to price policies more accurately, rewarding low‑risk driving patterns and offering dynamic premium adjustments throughout the policy term.
Frequently Asked Questions
Common queries about auto insurance commercial vehicles are addressed below.
Question 1: What distinguishes commercial auto insurance from personal auto policies?
Commercial policies cover business‑related risks, higher liability limits, and cargo protection, whereas personal policies focus on private use, lower limits, and exclude business activities.
Question 2: Are all business vehicles required to have commercial insurance?
Regulations vary by jurisdiction, but most states mandate commercial coverage for vehicles used to generate income, transport goods, or carry passengers for hire.
Question 3: How does driver experience affect premium costs?
Insurers assess driving records, training certifications, and years of experience; safer drivers typically earn lower rates due to reduced claim probability.
Question 4: Can a single policy cover multiple vehicle types?
Yes, multi‑vehicle policies can bundle trucks, vans, and specialty rigs, offering consolidated billing and potential volume discounts.
Question 5: What is the role of cargo insurance within a commercial auto policy?
Cargo insurance protects the value of goods in transit against loss, damage, or theft, and is often added as a separate endorsement to the primary auto policy.
Question 6: How often should a commercial fleet review its insurance coverage?
Annual reviews are recommended to align limits with fleet expansion, regulatory updates, and emerging risk factors, ensuring adequate protection.
Tips for Optimizing Commercial Auto Coverage
Implementing these eight actions can enhance protection and control costs.
Tip 1: Conduct a comprehensive risk audit. Identify exposure points, such as high‑value cargo or hazardous routes, to tailor coverage accordingly.
Tip 2: Leverage telematics data. Use real‑time metrics to negotiate usage‑based discounts and monitor driver behavior.
Tip 3: Bundle policies. Combine liability, physical‑damage, and cargo insurance under a single carrier for streamlined administration and potential savings.
Tip 4: Invest in driver training. Regular defensive‑driving courses reduce accident frequency and improve premium eligibility.
Tip 5: Maintain detailed vehicle logs. Accurate service records support claim validity and demonstrate proactive maintenance.
Tip 6: Review limits annually. Adjust per‑vehicle and aggregate limits to reflect fleet growth and evolving regulatory requirements.
Tip 7: Explore emerging endorsements. Consider cyber‑risk or electric‑vehicle coverage as technology adoption expands.
Tip 8: Engage a specialist broker. Expertise in commercial fleets can uncover hidden discounts and ensure comprehensive protection.
Conclusion
The landscape of auto insurance commercial vehicles encompasses pricing mechanisms, diverse coverage options, legal mandates, claim efficiency, risk mitigation, and forward‑looking technologies. Understanding each facet equips businesses to select appropriate limits, manage costs, and safeguard operational continuity.
As fleets become more connected and autonomous, ongoing evaluation of policies will remain essential, ensuring that protection evolves in step with innovation and regulatory change.

