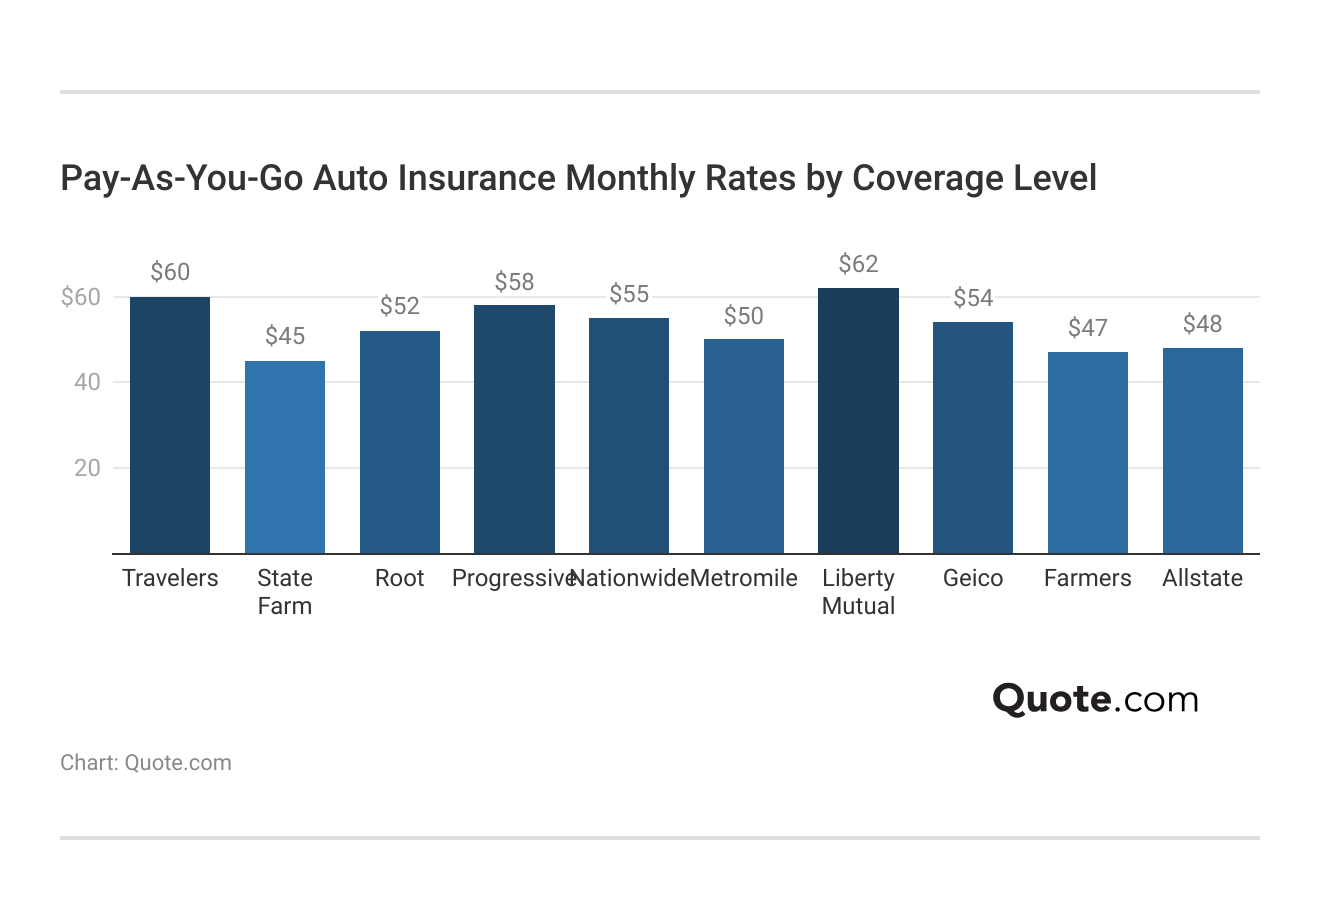
An **auto rate insurance quote** is a customized estimate provided by insurers to reflect the cost of insuring a vehicle and its driver based on risk factors, coverage levels, and market conditions. For example, a 30-year-old driver with a clean record seeking $50,000 in liability coverage and a collision deductible of $1,000 might receive a quote of $1,200 annually for a 2018 Honda Civic in a low-crash urban area. This figure isn’t arbitrary—it’s derived from actuarial data, regional claim frequencies, and the insurer’s profit margins.
The importance of an accurate **auto rate insurance quote** cannot be overstated. It serves as the foundation for financial planning, helping drivers budget for one of the largest annual expenses after housing. A miscalculated quote—whether inflated by hidden fees or underestimated due to overlooked discounts—can lead to overpaying by hundreds or thousands annually. Historically, insurance quotes were static documents adjusted only at renewal, but today’s dynamic underwriting models update rates in real time based on telematics, mileage tracking, and even weather patterns in specific zones.
Understanding how **auto rate insurance quotes** are structured, what influences them, and how to compare them effectively empowers drivers to secure fair pricing. This article examines the core components of insurance quotes, common pitfalls in interpretation, and actionable strategies to leverage quotes for maximum savings—without compromising coverage quality.
1. Pricing Dynamics Behind Quotes
An **auto rate insurance quote** is not a fixed number but a dynamic calculation incorporating dozens of variables. At its core, insurers assess risk: the likelihood of a claim being filed and its potential cost. For instance, a quote for a Tesla Model 3 in San Francisco will differ significantly from one for a Toyota Corolla in rural Kansas due to differences in theft rates, accident frequency, and repair costs. Even within the same city, a driver with a history of at-fault accidents will face higher premiums than someone with a five-year claim-free record.
Key factors include the vehicle’s make, model, and year (newer cars with advanced safety features often qualify for discounts), the driver’s age and gender (young male drivers typically pay more due to higher accident statistics), and location (urban areas with dense traffic and higher crime rates inflate quotes). Additionally, coverage limits—such as liability, collision, and comprehensive—directly impact the quote. A driver opting for the state minimum liability coverage will receive a lower quote than one selecting full coverage with a $500 deductible.
2. Coverage Tiers and Quote Impact
The structure of an **auto rate insurance quote** is heavily influenced by the tiers of coverage selected. Most quotes break down into three primary categories: liability, collision, and comprehensive. Liability coverage, which pays for damages to others in an at-fault accident, is legally required in most states but varies in limits (e.g., 25/50/25 in many states means $25,000 per person/$50,000 per accident for bodily injury and $25,000 for property damage). Opting for higher liability limits—such as 100/300/100—will increase the quote but provide greater financial protection in lawsuits.
- Liability Coverage
This is the most basic requirement and the largest factor in state-minimum quotes. For example, a driver in Texas with only the state-mandated $30,000 bodily injury limit per person may pay $800 annually, while increasing to $100,000 could add $300–$500 to the quote. The trade-off is critical: underinsured motorist coverage, which protects against drivers with insufficient insurance, can add $200–$400 but is often overlooked.
- Collision Coverage
This covers damage to the policyholder’s vehicle in an accident, regardless of fault. A quote for collision will depend on the car’s repair cost and the chosen deductible. A $500 deductible might reduce the annual premium by $400 compared to a $250 deductible, but the out-of-pocket expense in a claim rises proportionally. For a luxury vehicle like a BMW 5 Series, collision coverage could add $1,200–$1,800 to the quote annually.
- Comprehensive Coverage
Protecting against non-collision events like theft, vandalism, or hail, comprehensive coverage is often bundled with collision. A driver in a high-theft area (e.g., parts of California or Florida) may see comprehensive add $600–$900 to their quote, while in a low-risk zone, the addition might be as little as $300. Real-world example: A 2020 Jeep Wrangler in Phoenix, where monsoon-related hail storms are common, could see comprehensive rates spike by 15% during storm season.
- Uninsured/Underinsured Motorist
This coverage, often excluded or limited in quotes, can be a lifesaver. In states like Mississippi, where 1 in 5 drivers lacks insurance, adding uninsured motorist bodily injury coverage might increase a quote by $250 but prevent catastrophic medical bills if hit by an uninsured driver.
- Medical Payments (MedPay)
A lesser-known tier, MedPay covers medical expenses for the policyholder and passengers, regardless of fault. It’s particularly valuable in no-fault states like New York or Pennsylvania, where quotes might rise by $100–$300 for $5,000 in MedPay coverage, but it can offset high copays or deductibles in a medical emergency.
3. Vehicle-Specific Rate Factors
The make, model, year, and even the color of a vehicle play a surprising role in shaping an **auto rate insurance quote**. Insurers categorize cars by risk profiles, which are determined by crash test ratings, repair costs, theft vulnerability, and parts availability. For example, a 2023 Ford F-150 with a high safety rating (e.g., Top Safety Pick+) may qualify for a 5–10% discount on collision coverage, while a 2015 Nissan Versa with a history of airbag recalls could see rates inflated by 15–20% due to higher repair risks.
Vehicle age is another critical factor. Newer cars (under 3 years old) often have higher comprehensive and collision quotes because replacement costs are higher, but they may also qualify for anti-theft discounts if equipped with tracking devices. Older vehicles (over 10 years) might see lower quotes for collision but higher comprehensive rates if they’re desirable targets for thieves (e.g., classic cars or high-end sedans). Real-world data shows that a 2019 Toyota Camry in excellent condition could receive a 10% lower quote than a similarly priced 2018 Honda Accord with a reported hail-damaged frame.
4. Driver Demographics and Quote Variability
Driver demographics—age, gender, marital status, and even credit score—are among the most contentious yet influential factors in an **auto rate insurance quote**. While some states like California and Massachusetts restrict the use of gender or marital status in pricing, most insurers still adjust rates based on these variables. For instance, a 17-year-old male driver in Florida might pay triple the rate of a 50-year-old female driver for the same coverage on the same vehicle. This disparity stems from historical claim data: younger male drivers statistically file more claims, particularly for speeding-related accidents.
Credit-based insurance scores, used by 95% of insurers, further complicate quotes. A driver with a credit score below 580 could see their premiums inflated by 30–50% compared to someone with a score above 720. The rationale is that creditworthiness correlates with financial responsibility, though this practice remains controversial. For example, a driver in Georgia with a 650 credit score might pay $1,500 annually for full coverage on a 2017 Mazda CX-5, while a driver with a 780 score could secure the same coverage for $1,100—saving $400 annually.
5. Geographic and Environmental Influences
Location is one of the most significant variables in an **auto rate insurance quote**, often overshadowing even vehicle or driver factors. Insurers analyze ZIP codes for claim frequencies, traffic density, weather risks, and crime rates. A driver in Miami, where hurricanes and flooding are common, will see higher comprehensive quotes due to storm damage risks, while a driver in Fargo, North Dakota, might face higher collision rates in winter due to icy road conditions. Urban areas like Los Angeles or Chicago typically have higher quotes because of congestion-related accidents and higher repair costs, whereas rural areas may offer lower rates but could lack local insurer support.
- Urban vs. Rural Divide
In New York City, the average full-coverage quote for a 2020 Honda Civic is $2,200 annually, compared to $1,400 in rural Upstate New York. The difference stems from higher traffic density, increased theft risks, and more expensive repair shops in cities. Conversely, rural drivers might pay more for medical payments due to limited healthcare access.
- Weather-Related Adjustments
Florida drivers see quotes spike during hurricane season (June–November) as insurers anticipate higher comprehensive claims. For example, a driver in Fort Lauderdale might receive a 10% higher quote in September than in February. Similarly, drivers in states like Colorado or Utah face higher winter collision rates due to snow and ice, leading to temporary premium adjustments.
- State Regulations and Taxes
States with high insurance taxes (e.g., Louisiana, Ohio) add 10–20% to quotes through mandatory fees. For instance, a $1,000 premium in Louisiana could become $1,150 after state taxes. Conversely, states like Maine or Vermont, with lower taxes and fewer insurers, may offer more competitive rates but less coverage variety.
- Local Crime Rates
Vehicles in high-theft areas (e.g., parts of Oakland, CA, or Detroit, MI) see comprehensive quotes inflated by 20–30%. A 2021 Toyota RAV4 in Detroit might cost $800 more annually for comprehensive coverage than the same vehicle in a low-theft suburb like Ann Arbor, MI.
- Insurer Market Penetration
In states like Texas or Florida, where insurers compete fiercely, quotes can vary by 40% between providers for the same coverage. However, in markets with fewer insurers (e.g., Vermont or Wyoming), drivers have less negotiating power, leading to higher average quotes.
6. Discounts and How They Modify Quotes
Discounts are the most overlooked leverage point in an **auto rate insurance quote**, yet they can reduce premiums by 20–50% when applied correctly. Insurers offer discounts for bundling policies (e.g., combining auto with home or renters insurance), maintaining a clean driving record, enrolling in defensive driving courses, or installing anti-theft devices. For example, a driver in Illinois who bundles their auto policy with a homeowners policy might save $300 annually, while adding a dashcam to record accidents could yield a 10% discount on collision coverage. Even lesser-known discounts, like those for being a student with a B average or belonging to certain professional organizations, can shave hundreds off a quote.
The challenge lies in identifying all eligible discounts. Many drivers overlook multi-policy discounts or fail to ask about usage-based programs like Progressive’s Snapshot or State Farm’s Drive Safe & Save, which monitor driving habits via telematics. A driver in Arizona who installs a telematics device and maintains a 90 mph speed limit could see their quote drop by $400 annually. Similarly, paying the premium annually instead of monthly can reduce administrative fees by 5–10%, translating to $100–$200 in savings.
7. Common Mistakes in Quote Interpretation
Misinterpreting an **auto rate insurance quote** is a common pitfall that leads to overpaying or insufficient coverage. One frequent error is assuming the quoted premium is the final cost without accounting for state fees, taxes, or optional add-ons like roadside assistance or gap insurance. For instance, a quote of $1,200 in Pennsylvania might jump to $1,350 after adding a 12% state insurance tax. Another mistake is ignoring the deductible’s impact: selecting a low deductible (e.g., $250) to reduce the monthly premium can backfire if a claim exceeds the deductible savings over time.
Drivers also often overlook the importance of comparing quotes from multiple insurers. A study by the Insurance Information Institute found that drivers who shopped with three or more insurers saved an average of $720 annually. Additionally, failing to update quotes after life changes—such as moving, marrying, or purchasing a new car—can result in overpaying. For example, a driver who doesn’t notify their insurer after relocating from a high-risk urban area to a low-risk suburb might continue paying a premium 30% higher than necessary.
8. Technology’s Role in Quote Accuracy
Advancements in technology have revolutionized how **auto rate insurance quotes** are calculated, shifting from static underwriting to dynamic, real-time models. Telematics, for instance, allows insurers to monitor driving behavior—such as hard braking, speeding, or nighttime driving—via smartphone apps or plug-in devices. A driver in Texas who uses a telematics program and demonstrates safe driving habits might see their quote reduced by 15% within six months. Similarly, usage-based insurance (UBI) programs adjust quotes based on mileage: a driver who primarily uses their car for commuting (15,000 miles/year) could pay 20% less than someone who drives 30,000 miles annually for business.
Artificial intelligence and machine learning further refine quote accuracy by analyzing vast datasets, including weather patterns, local road conditions, and even social determinants like income levels in a ZIP code. For example, an AI-driven insurer might adjust quotes in real time during severe weather events, offering temporary discounts for drivers who reduce mileage during a blizzard. However, this level of personalization also raises privacy concerns, as drivers must weigh the benefits of data sharing against potential misuse.
Frequently Asked Questions
An **auto rate insurance quote** can seem complex—here are answers to the most common questions.
Question 1: Why do quotes vary so much between insurers for the same coverage?
Insurers use different underwriting models, claim data, and risk assessments. For example, Geico may offer lower quotes in states where it has strong market share, while a regional insurer might provide better rates in a specific city. Additionally, some insurers specialize in high-risk drivers or offer more discounts, leading to variability. Always compare at least three quotes to find the best fit.
Question 2: Does my credit score significantly affect my auto insurance quote?
Yes, in most states. A poor credit score (below 580) can increase premiums by 30–50% compared to excellent credit (720+). Insurers correlate creditworthiness with financial responsibility, assuming drivers with lower scores may file more claims. Improving credit by paying bills on time or reducing debt could lower quotes within a year.
Question 3: Can I lower my quote by increasing my deductible?
Increasing the deductible (e.g., from $500 to $1,000) typically reduces the premium by 15–30%. However, this strategy only works if you can afford the higher out-of-pocket cost in an accident. For example, a $1,000 deductible could save $400 annually but require paying $1,000 upfront after a claim, negating savings for minor incidents.
Question 4: Will my quote go up if I add a teenage driver to my policy?
Absolutely. Adding a teen driver—especially a male—can increase premiums by 100–200% due to their higher accident risk. For instance, a $1,200 quote for a 40-year-old driver might jump to $2,800 after adding a 16-year-old son. Mitigation strategies include enrolling the teen in a defensive driving course or adding them to a separate policy if eligible.
Question 5: How often should I update my auto insurance quote?
At least annually, or whenever life changes occur—such as moving, buying a new car, or marriage. For example, relocating from a high-crime city to a rural area could lower quotes by 25%. Additionally, insurers may adjust rates based on inflation or claim trends, so reviewing quotes every 6–12 months ensures you’re not overpaying.
Question 6: Are online quote tools accurate compared to quotes from an agent?
Online tools provide a close estimate but may not account for all discounts or local factors an agent could uncover. For example, an agent might negotiate a 10% discount for bundling policies or identify a lesser-known insurer with better rates. However, online tools are faster and useful for initial comparisons before consulting an agent for finalization.
13 Actionable Tips to Optimize Your Auto Rate Insurance Quote
Securing the best **auto rate insurance quote** requires strategy. Here are 13 practical steps to maximize savings and coverage.
Tip 1: Compare quotes from at least five insurers. Prices vary widely—shopping with Geico, Progressive, State Farm, and local providers can uncover savings of $500–$1,500 annually.
Tip 2: Bundle auto with home or renters insurance. Insurers offer 10–25% discounts for bundling. For example, bundling a $1,200 auto policy with a $900 home policy could save $250–$300 yearly.
Tip 3: Increase your deductible to lower premiums. Raising the deductible from $500 to $1,000 might cut your premium by $300–$500, but ensure you can cover the higher out-of-pocket cost.
Tip 4: Install anti-theft devices or a dashcam. Devices like OnStar or LoJack can reduce comprehensive quotes by 10–20%. Dashcams may also lower collision rates by discouraging fraudulent claims.
Tip 5: Ask about all available discounts. Many drivers miss discounts for low mileage, safe driving, or professional affiliations. A quick call to your insurer can reveal overlooked savings of $100–$400.
Tip 6: Pay your premium annually instead of monthly. Monthly payments often include fees of 2–5% per month, adding $60–$120 annually. Paying upfront can save $100–$200.
Tip 7: Maintain a clean driving record. Even one at-fault accident can raise quotes by 40–60% for three years. Defensive driving courses can sometimes mitigate this impact.
Tip 8: Choose a vehicle with safety features. Cars with top safety ratings (e.g., IIHS Top Safety Pick+) may qualify for 5–15% discounts on collision coverage.
Tip 9: Review and update your quote annually. Life changes—like moving, marriage, or a new car—can lower quotes. A simple policy review can save $300–$800.
Tip 10: Consider usage-based insurance programs. Apps like Progressive’s Snapshot or Allstate’s Drivewise track driving habits. Safe drivers can save 10–30% by demonstrating low risk.
Tip 11: Avoid lapses in coverage. Even a 30-day gap can increase future quotes by 20–40%. Set up automatic payments to prevent unintended cancellations.
Tip 12: Negotiate with your insurer. If you’ve been a loyal customer with a clean record, ask for a loyalty discount or rate adjustment. Some insurers offer 5–10% discounts for long-term clients.
Tip 13: Reassess your coverage needs every few years. As your car ages or your financial situation changes, adjust coverage to avoid overpaying. For example, dropping collision coverage on a 15-year-old car with low market value can save $500–$1,000 annually.
Conclusion
An **auto rate insurance quote** is far more than a static number—it’s a reflection of risk, coverage needs, and market dynamics. By understanding the factors that shape quotes—from vehicle specifics and driver demographics to geographic risks and available discounts—drivers can navigate the insurance landscape with confidence. The key lies in proactive comparison, leveraging technology, and regularly reviewing policies to align with changing circumstances. As insurers continue to adopt AI and telematics, quotes will become even more personalized, offering both challenges and opportunities for savvy consumers to secure fair, affordable coverage.
In the years ahead, the ability to interpret and optimize quotes will be a critical skill, ensuring drivers balance cost with comprehensive protection. Staying informed and strategic today sets the foundation for smarter, more secure insurance decisions tomorrow.

