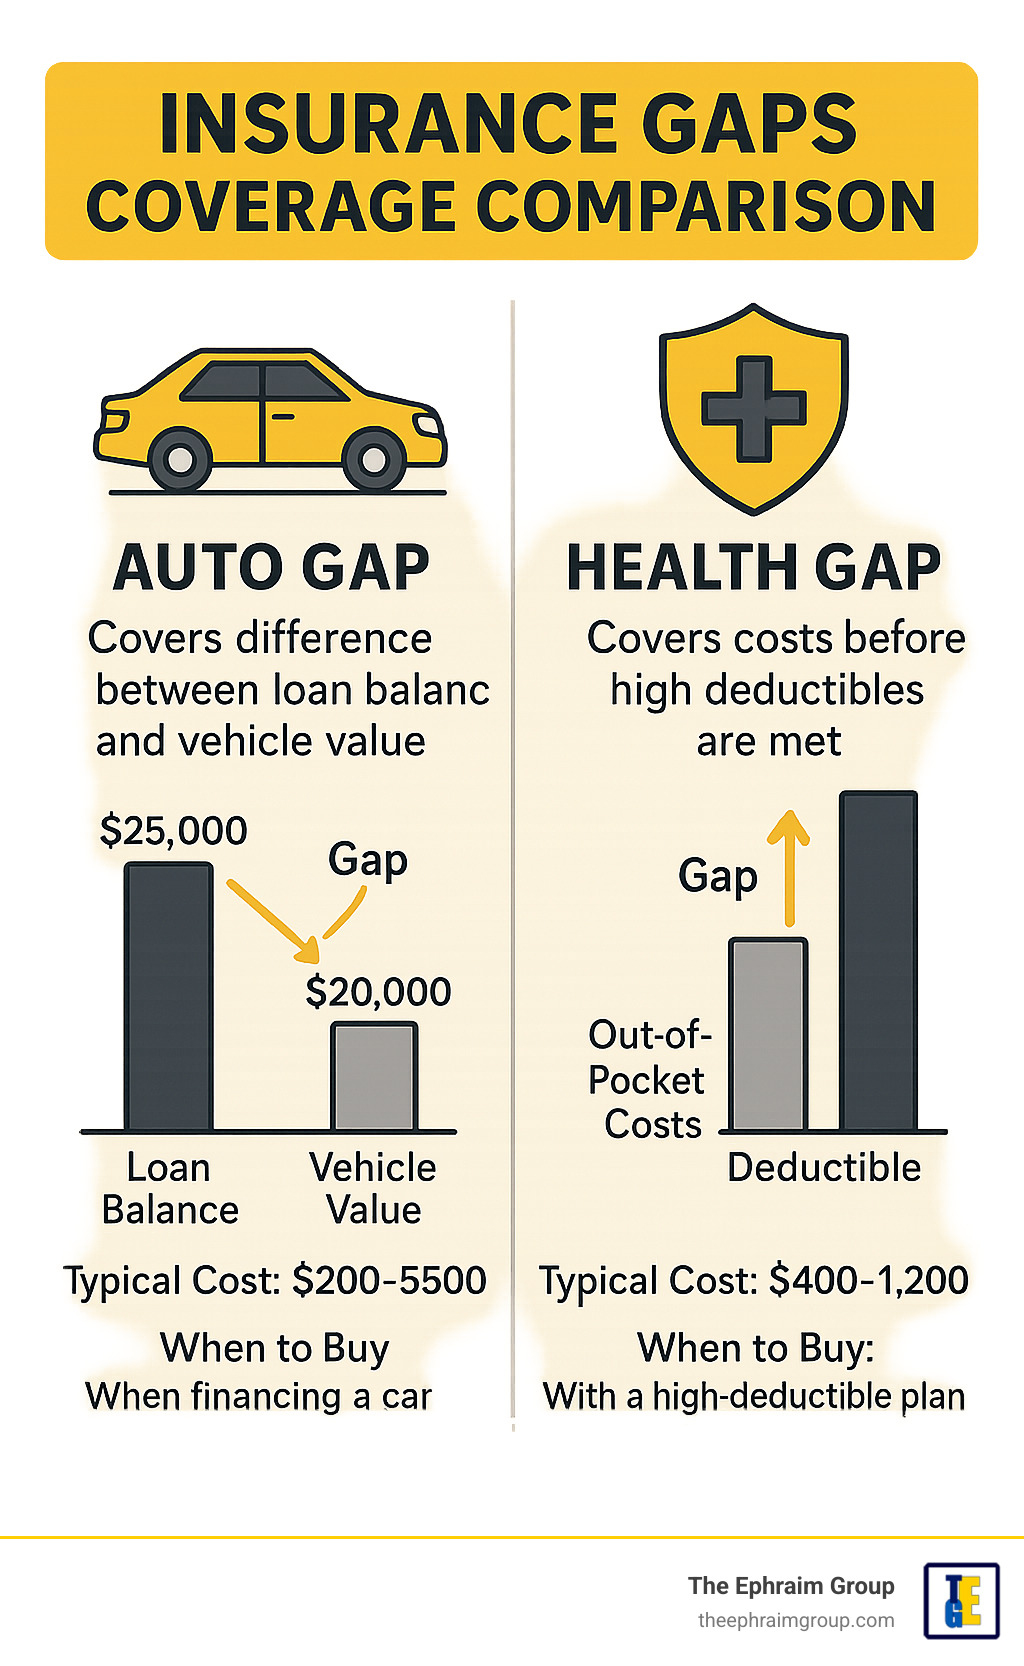
Auto insurance with gap coverage bridges the financial void that can appear when a vehicle is declared a total loss before the loan or lease balance is fully paid. For example, if a 2022 Honda Civic is totaled after 18 months and the market value is $18,000 while the remaining loan balance is $22,000, gap coverage would pay the $4,000 difference.
This protection matters because many drivers underestimate the depreciation rate of new cars and may face unexpected debt after an accident. Historically, gap policies emerged alongside the rise of high‑interest auto loans in the early 2000s, offering a safety net for borrowers who finance or lease vehicles.
The following sections unpack pricing dynamics, eligibility criteria, claim processes, common pitfalls, and strategies for selecting the right policy, ensuring a thorough grasp of auto insurance with gap coverage.
1. Pricing Dynamics
Premiums for gap coverage are influenced by vehicle age, loan amount, and insurer underwriting standards. Younger cars depreciate faster, prompting higher rates, while older models often qualify for lower fees.
- Depreciation Rate
The faster a car loses value, the more likely a gap claim becomes. A 2023 Tesla Model 3 may lose 20% of its value in the first year, raising the cost of gap protection for owners financing a $45,000 loan.
- Loan-to-Value Ratio
Borrowers who finance 110% of a vehicle’s purchase price face higher premiums because the insurer assumes a larger potential payout.
- State Regulations
Some states cap gap coverage fees or require insurers to disclose cost breakdowns, affecting overall pricing.
- Bundling Discounts
Adding gap coverage to an existing auto policy can shave 5‑10% off the combined premium, a common incentive offered by companies like State Farm and GEICO.
- Credit Score Impact
Higher credit scores often translate to lower loan interest rates and, indirectly, reduced gap coverage costs because the loan balance is smaller.
2. Eligibility Criteria
Not every driver automatically qualifies for gap coverage. Insurers typically require a financed or leased vehicle, a minimum loan term of 12 months, and a clear claim history. Those who own a car outright usually cannot purchase gap protection unless they refinance.
Leasing companies frequently mandate gap coverage as part of the lease agreement, protecting both the lessee and the lessor from residual value shortfalls.
3. Claim Process Explained
When a total loss occurs, the primary insurer first pays the actual cash value (ACV) of the vehicle. The gap insurer then assesses the remaining loan balance and any deductible to determine the supplemental payout.
- Documentation
Claimants must submit the loan statement, police report, and photos of the damaged vehicle. Clear paperwork accelerates the payout timeline.
- Timing
Most policies require a claim to be filed within 30 days of the loss; delays can result in reduced benefits or denial.
- Coordination
Insurers often coordinate payments directly with the lender, ensuring the borrower does not receive duplicate funds.
4. Common Mistakes to Avoid
Many drivers either overpay for gap coverage or neglect it altogether. Purchasing a policy without confirming the loan balance can lead to unnecessary expense, while omitting gap protection on a high‑depreciation vehicle leaves a financial hole.
Another frequent error is assuming that a standard comprehensive policy includes gap coverage; it does not, and a separate endorsement is required.
5. Choosing the Right Provider
Evaluating insurers involves comparing coverage limits, exclusions, and customer service ratings. Companies such as Allstate, Progressive, and USAA rank highly for claim satisfaction and transparent pricing.
- Coverage Limits
Some policies cap payouts at $10,000, which may be insufficient for high‑value loans; verify the maximum before signing.
- Exclusions
Policies may exclude losses due to illegal activities or intentional damage, so read fine print carefully.
- Customer Reviews
Platforms like J.D. Power and Consumer Reports provide insight into claim handling speed and fairness.
6. Financial Impact Over Time
Adding gap coverage typically adds $20‑$50 per month to an auto policy, a modest increase compared to the potential $5,000‑$10,000 shortfall after a total loss. Over a three‑year loan, the total cost may be $720‑$1,800, far less than the risk exposure.
Long‑term owners who pay off their loan early often discontinue gap coverage, reducing ongoing expenses without sacrificing protection.
Frequently Asked Questions
Below are concise answers to the most common queries about auto insurance with gap coverage.
Question 1: Does gap coverage apply to leased vehicles?
Yes, most lease agreements require gap coverage, ensuring the lessee does not owe money if the car is declared a total loss before the lease ends.
Question 2: Can gap coverage be added after purchasing a car?
Many insurers allow a gap endorsement within 30 days of financing; however, adding it later may involve higher premiums or limited coverage.
Question 3: What happens if the loan is paid off early?
Once the loan balance reaches zero, gap coverage no longer provides value and can be cancelled to avoid unnecessary cost.
Question 4: Is gap coverage taxable?
The payout from a gap claim is generally not taxable because it reimburses a debt, not income, but consult a tax professional for personal circumstances.
Question 5: Does comprehensive insurance include gap coverage?
No, comprehensive or collision coverage pays the vehicle’s actual cash value; gap coverage is a separate policy or endorsement that covers the loan shortfall.
Question 6: How does a deductible affect a gap claim?
The deductible is first applied to the primary insurer’s payout; the gap insurer then covers the remaining loan balance after the deductible is accounted for.
11 Essential Tips for Gap Coverage
Implement these actionable steps to maximize protection and minimize cost.
Tip 1: Review loan statements. Confirm the exact balance before selecting a gap policy to avoid overpaying.
Tip 2: Compare multiple quotes. Use aggregator sites to find the best rate and coverage limits.
Tip 3: Check for bundling discounts. Adding gap coverage to an existing auto policy often reduces overall premiums.
Tip 4: Verify state regulations. Some states require specific disclosures that can affect policy terms.
Tip 5: Understand depreciation schedules. Knowing how quickly a vehicle loses value helps gauge the necessity of gap coverage.
Tip 6: Keep documentation organized. Store loan agreements, insurance cards, and claim forms in a dedicated folder.
Tip 7: File claims promptly. Most policies mandate a 30‑day filing window to preserve full benefits.
Tip 8: Review exclusions. Ensure the policy does not exclude scenarios relevant to personal driving habits.
Tip 9: Cancel when loan ends. Discontinue gap coverage once the balance is zero to avoid wasteful expense.
Tip 10: Ask about payout caps. Verify the maximum amount the gap insurer will pay to avoid surprises.
Tip 11: Seek professional advice. Consult an insurance agent for personalized recommendations based on credit score and loan terms.
Conclusion
Auto insurance with gap coverage fills the financial gap between a vehicle’s market value and the remaining loan or lease balance, offering peace of mind and fiscal protection. By understanding pricing, eligibility, claim mechanics, and provider selection, drivers can make informed decisions that align with their budget and risk tolerance.
Armed with the insights and tips presented, future policyholders can confidently navigate the gap insurance landscape and safeguard their investments against unexpected total losses.

