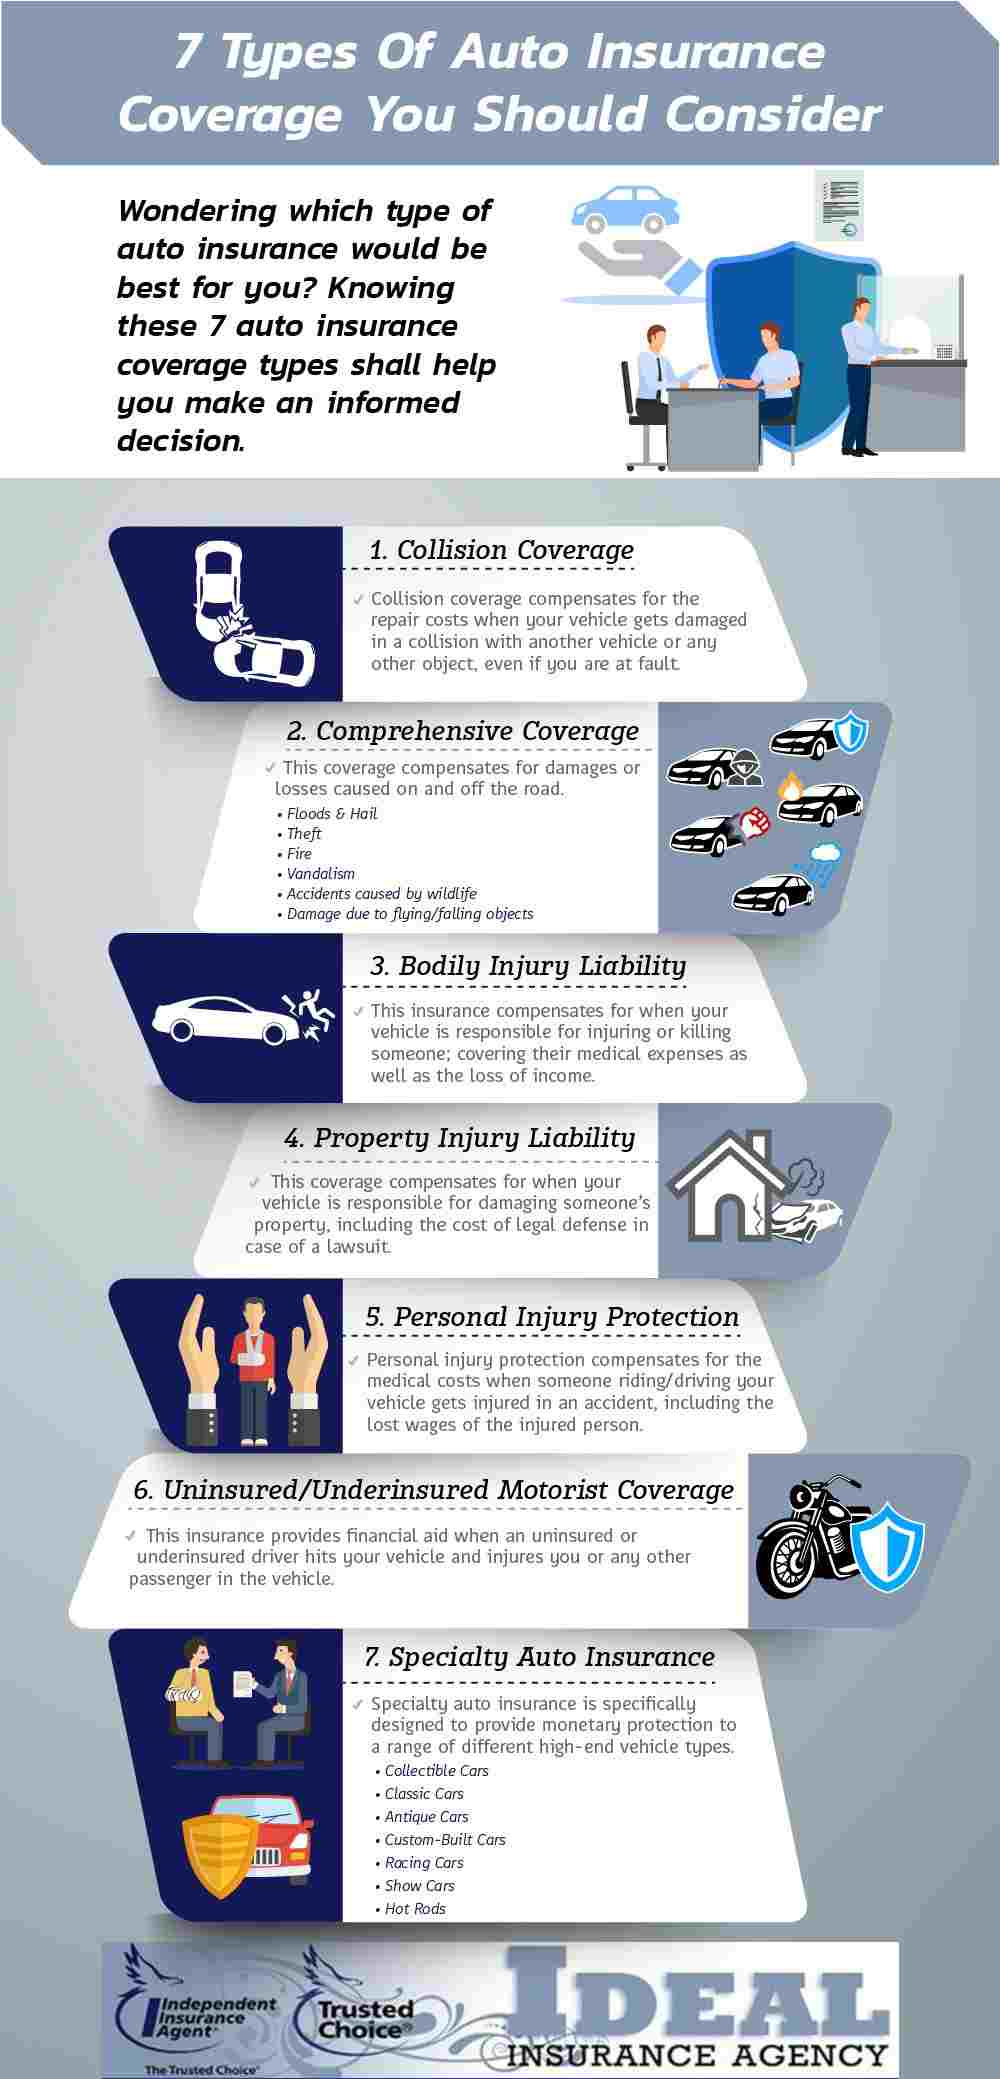
Understanding auto insurance types of coverage is essential for every driver who wants to protect both vehicle and finances. For instance, a driver in Florida might combine liability with uninsured motorist coverage to safeguard against accidents involving drivers without insurance.
These coverages have evolved from simple liability policies in the early 1900s to today’s multi‑layered plans that address a wide range of risks, from natural disasters to medical expenses. Proper selection reduces out‑of‑pocket costs, ensures compliance with state laws, and provides peace of mind on the road.
This article breaks down the major coverage categories, compares their purposes, and offers practical tips for tailoring a policy that fits individual driving habits and budget constraints.
1. Auto Insurance Types of Coverage Overview
Every auto policy is built from a core set of coverages, each serving a distinct purpose. Liability coverage handles damages to others, while collision protects the insured vehicle after a crash. Understanding how these pieces fit together helps drivers avoid gaps in protection.
Choosing the right mix depends on factors like vehicle value, driving frequency, and state requirements. For example, a high‑value sports car often warrants comprehensive and collision coverage, whereas an older commuter might rely mainly on liability.
2. Liability Coverage
- Bodily Injury Liability
Provides compensation for medical expenses of third parties injured in an accident caused by the insured driver. A driver in Texas who rear‑ended a sedan would pay for the passenger’s hospital bills, preventing personal financial loss.
- Property Damage Liability
Covers repair or replacement costs for another person’s vehicle or property. If a driver in Ohio hits a fence, this coverage pays the fence owner’s repair bill, keeping the insured driver from a costly lawsuit.
- State Minimum Limits
Each state sets required minimums; exceeding them reduces exposure. A driver in California opting for $100,000/$300,000 limits gains broader protection than the statutory $15,000/$30,000.
3. Collision Coverage
Collision insurance reimburses the insured for damage to their own vehicle after a crash, regardless of fault. It is especially valuable for newer cars where repair costs can approach the vehicle’s market value. A driver in Michigan who collides with a pole benefits from collision coverage that funds the repair, avoiding out‑of‑pocket expenses.
Deductibles typically range from $250 to $1,000; selecting a higher deductible lowers premium but increases immediate cost after a claim. Balancing these factors is key for cost‑effective protection.
4. Comprehensive Coverage
- Theft Protection
Covers loss when a vehicle is stolen. A driver in New York whose car was taken from a street parking spot receives reimbursement for the vehicle’s market value, minus deductible.
- Natural Disasters
Insures against damage from floods, hail, or earthquakes. In Florida, where hurricanes are common, comprehensive coverage can fund repairs after wind‑blown debris damages the roof.
- Vandalism
Pays for repair of intentional damage. If a teenager in Chicago sprays paint on a parked car, comprehensive coverage handles the repainting costs.
- Animal Collisions
Covers damage from hitting a deer or other wildlife. In rural Pennsylvania, drivers often rely on this facet after a sudden deer strike causes severe bumper damage.
5. Uninsured/Underinsured Motorist Coverage
These coverages protect the insured when the at‑fault driver lacks sufficient insurance. In states like California, where uninsured rates exceed 15%, this protection can cover medical bills and vehicle repairs that the negligent driver cannot pay.
Underinsured motorist coverage kicks in when the at‑fault driver’s policy limits are lower than the victim’s damages, filling the gap and preventing personal financial strain.
6. Medical Payments / Personal Injury Protection
Medical payments (MedPay) and personal injury protection (PIP) cover the insured’s medical expenses regardless of fault. In no‑fault states such as Florida, PIP also includes lost wages and funeral costs, offering broader support after an accident.
These benefits are especially useful for families with young children or for drivers who lack robust health insurance, ensuring prompt treatment without billing delays.
Frequently Asked Questions
Below are concise answers to common queries about auto insurance coverage.
Question 1: What is the difference between liability and collision coverage?
Liability covers damages you cause to others, while collision pays for repairs to your own vehicle after a crash, regardless of who is at fault.
Question 2: Is comprehensive coverage necessary for an older car?
It depends on the vehicle’s value and the driver’s risk tolerance; for low‑value cars, the cost may outweigh the benefit, but it protects against non‑collision events.
Question 3: How does uninsured motorist coverage work?
If an at‑fault driver lacks insurance, this coverage pays for your medical bills and property damage up to the policy limits, shielding you from the uninsured driver’s financial liability.
Question 4: Can I combine PIP with health insurance?
Yes; PIP typically covers immediate medical costs and lost wages, while health insurance can handle longer‑term care, providing complementary protection.
Question 5: What factors influence my auto insurance premium?
Premiums are affected by driving record, vehicle type, location, coverage limits, deductible choices, and credit score, among other risk indicators.
Question 6: Should I increase my liability limits above the state minimum?
Increasing limits reduces exposure to large lawsuits and can protect personal assets, making it a prudent choice for most drivers.
Tips
Here are thirteen actionable steps to optimize auto insurance coverage.
Tip 1: Review policy annually. Market rates and personal circumstances change; an annual check ensures optimal coverage and pricing.
Tip 2: Bundle policies. Combine auto with home or renters insurance to qualify for multi‑policy discounts.
Tip 3: Increase deductibles wisely. Higher deductibles lower premiums but require sufficient emergency funds for out‑of‑pocket costs.
Tip 4: Verify state minimums. Ensure your policy meets or exceeds local legal requirements to avoid penalties.
Tip 5: Add uninsured motorist coverage. Protect against drivers lacking insurance, a common risk in many states.
Tip 6: Consider comprehensive for high‑risk areas. If living in flood‑prone or hurricane zones, comprehensive coverage mitigates natural‑disaster losses.
Tip 7: Maintain a clean driving record. Safe driving often translates into lower premium tiers.
Tip 8: Use telematics if available. Usage‑based programs can reward low mileage and safe habits with discounts.
Tip 9: Shop quotes from multiple carriers. Competitive bidding uncovers better rates and coverage options.
Tip 10: Update mileage estimates. Accurate annual mileage helps insurers price risk more accurately.
Tip 11: Ask about loyalty discounts. Long‑term customers may qualify for reduced rates.
Tip 12: Review claim history. Frequent claims can raise premiums; assess whether filing is financially sensible.
Tip 13: Consult an independent agent. An expert can tailor coverage to specific needs without bias toward a single insurer.
Conclusion
The spectrum of auto insurance types of coverage—from liability to comprehensive—provides a layered defense against the unpredictable costs of driving. By understanding each facet, comparing limits, and aligning policies with personal risk profiles, drivers can secure both compliance and financial security.
Staying informed and periodically adjusting coverage ensures that protection evolves alongside life changes, keeping the road ahead safer and more affordable.

