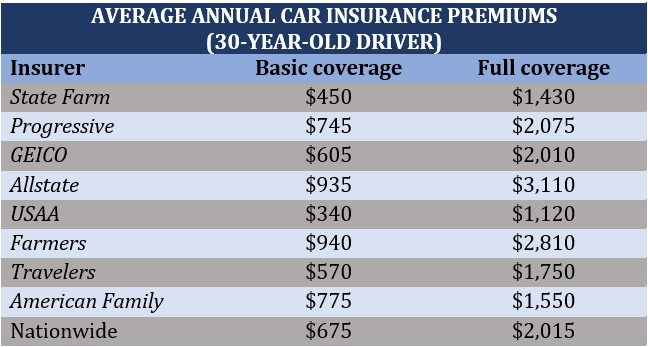
Auto insurance rate compare refers to the systematic process of evaluating premium offers from multiple carriers to identify the most cost‑effective and suitable coverage for a specific driver profile. For example, a 30‑year‑old driver in Ohio might receive a $1,200 quote from State Farm, a $1,050 quote from Geico, and a $970 quote from Progressive after entering identical vehicle and driving history details.
The practice holds critical importance because auto insurance represents one of the largest recurring household expenses, and even modest premium differences accumulate into substantial savings over the policy term. Historically, the rise of online aggregators in the early 2000s transformed a once‑manual, phone‑based comparison into a rapid, data‑driven experience, empowering consumers to leverage market competition.
This article dissects the mechanics behind auto insurance rate compare, highlights pivotal factors that shape premiums, outlines common pitfalls, and delivers actionable strategies for achieving optimal coverage while minimizing cost.
1. Pricing Dynamics
Premium calculations blend actuarial data, risk assessments, and business objectives. Insurers weigh variables such as driver age, vehicle type, mileage, and claim history to produce a base rate. Adjustments for regional accident frequency or local repair costs further refine the final figure. Understanding these dynamics equips policyholders to anticipate where price fluctuations may arise and to negotiate more effectively.
When a driver relocates from a rural county to an urban metropolitan area, the underlying risk exposure shifts dramatically, prompting insurers to recalibrate rates. Recognizing such cause‑and‑effect relationships enables smarter timing for rate compare activities.
2. Auto Insurance Rate Compare
- Quote Aggregators
Online platforms such as NerdWallet or The Zebra compile offers from dozens of carriers, presenting side‑by‑side premium tables. A driver in Texas discovered a $150 monthly saving by switching after the aggregator highlighted a lower‑cost option previously unknown.
- Policy Detail Matching
Accurate input of coverage limits, deductibles, and optional add‑ons ensures apples‑to‑apples comparisons. Overlooking a personal injury protection (PIP) rider can skew perceived savings, leading to under‑insured exposure.
- Time‑Sensitive Discounts
Many insurers offer limited‑time promotions tied to enrollment periods. Capturing a “new customer” discount within a 30‑day window can shave 5‑10% off the quoted premium.
3. Factors Influencing Rates
- Driving Record
A clean record with no moving violations typically yields lower rates. Conversely, a single speeding ticket can increase premiums by up to 20% depending on state regulations.
- Vehicle Characteristics
High‑performance sports cars attract higher premiums due to elevated repair costs and theft risk, while safety‑rated sedans often qualify for lower rates.
- Credit-Based Scoring
In most states, insurers incorporate credit scores into pricing models; a strong credit rating can reduce premiums by 15% or more.
- Annual Mileage
Drivers who log fewer than 7,500 miles per year frequently qualify for low‑ mileage discounts, reflecting reduced exposure to accidents.
- Geographic Location
Urban centers with dense traffic and higher accident frequencies command higher rates compared to suburban or rural locales.
4. Comparison Tools
Beyond aggregators, insurers provide proprietary calculators that factor in loyalty discounts, bundling incentives, and usage‑based telematics. For instance, State Farm’s “Drive Safe & Save” app records real‑time driving behavior, translating safe miles into premium credits. Leveraging both third‑party and carrier‑specific tools yields a comprehensive view of potential savings.
Spreadsheet models also assist analytical minds; by inputting variables such as deductible level, coverage limits, and discount eligibility, policyholders can simulate cost outcomes across multiple carriers before initiating a formal quote request.
5. Common Mistakes
- Overlooking Coverage Gaps
Focusing solely on price may lead to selecting policies lacking essential protections like uninsured motorist coverage, exposing drivers to financial risk after an accident.
- Neglecting Policy Updates
Failing to revise coverage after major life events—marriage, new vehicle purchase, or moving—can result in outdated premiums that either overpay or under‑protect.
- Assuming All Discounts Apply
Not all insurers honor the same discount categories; assuming a student discount will automatically apply can cause surprise at renewal.
- Comparing Inconsistent Terms
Mixing policies with different deductible amounts or liability limits skews perceived cost differences, leading to inaccurate conclusions.
6. Discounts and Savings
Insurers reward risk‑mitigating behaviors with a variety of discounts. Multi‑policy bundling—combining auto with home or renters insurance—often yields 10‑15% off each policy. Defensive driving courses, safe‑driver clubs, and anti‑theft device installations further lower rates. Additionally, some carriers provide loyalty discounts for policyholders who maintain continuous coverage for five years or more.
Strategic use of these incentives during an auto insurance rate compare exercise can dramatically improve the value proposition, turning a modest premium reduction into a multi‑hundred‑dollar annual saving.
7. State Regulations
Regulatory environments shape the parameters of what insurers may charge. States such as California enforce strict limits on how credit scores influence premiums, while Florida mandates minimum personal injury protection levels. Understanding jurisdictional rules helps drivers anticipate mandatory coverage costs and identify where optional add‑ons might be unnecessary.
When conducting an auto insurance rate compare across state lines—such as for a seasonal worker relocating temporarily—policyholders must account for these regulatory variations to avoid inadvertent non‑compliance.
Frequently Asked Questions
Below are common inquiries related to auto insurance rate compare.
Question 1: How often should a driver perform an auto insurance rate compare?
Experts recommend reviewing premiums at least annually, or whenever a major life event occurs, such as moving, purchasing a new vehicle, or experiencing a significant change in driving habits. Regular checks capture emerging discounts and market shifts, ensuring continuous cost efficiency.
Question 2: Do online quote aggregators guarantee the lowest price?
Aggregators provide a broad snapshot of available offers, but some insurers reserve exclusive discounts for direct inquiries. Therefore, combining aggregator results with direct carrier outreach often uncovers the absolute lowest rate.
Question 3: Which factors most heavily influence premium differences?
Driving record, vehicle type, credit score, and geographic location dominate premium calculations. Adjustments for mileage, age, and selected coverage limits also create notable variations between competing quotes.
Question 4: Can bundling policies affect the outcome of a rate compare?
Bundling typically reduces overall costs by 10‑20% and should be incorporated into any comparison. However, the combined premium must still meet coverage needs; a lower bundled price does not justify sacrificing essential protection.
Question 5: Are usage‑based telematics programs worth considering?
Drivers with consistently safe habits can see premiums drop 5‑30% through telematics programs. For high‑risk drivers, the savings may be minimal, making traditional rating models more appropriate.
Question 6: How do state minimum requirements impact a rate compare?
Each state mandates specific liability limits; failing to meet these thresholds can lead to penalties. Including state‑required minimums in every quote ensures accurate, compliant comparisons.
Tips for Comparing Auto Insurance Rates
Effective strategies enhance both savings and coverage quality.
Tip 1: Define coverage priorities. Identify essential protection levels before reviewing quotes to avoid extraneous add‑ons.
Tip 2: Use multiple aggregators. Different platforms may feature distinct carrier partnerships, expanding the pool of options.
Tip 3: Verify deductible consistency. Compare policies with identical deductibles to ensure true cost parity.
Tip 4: Input accurate vehicle data. Correct VIN, model year, and safety features prevent mispriced estimates.
Tip 5: Check for hidden fees. Look beyond the advertised premium to uncover administrative or processing surcharges.
Tip 6: Explore multi‑policy discounts. Bundling auto with home or renters insurance often yields substantial savings.
Tip 7: Ask about loyalty rewards. Long‑term policyholders may qualify for renewal bonuses not listed online.
Tip 8: Review credit‑score impact. If credit influences pricing, consider improving the score before requesting new quotes.
Tip 9: Consider usage‑based programs. Install telematics devices only if safe driving habits are consistently demonstrated.
Tip 10: Update personal information promptly. Changes in marital status, address, or vehicle ownership affect premium calculations.
Tip 11: Examine claim‑free discounts. Maintaining a clean claim history can unlock additional rate reductions.
Tip 12: Evaluate insurer financial strength. Choose carriers with strong ratings from agencies like AM Best to ensure claim reliability.
Tip 13: Read policy fine print. Clarify exclusions and limits to avoid unexpected out‑of‑pocket expenses.
Tip 14: Time purchases with promotional periods. Seasonal sales or anniversary offers can provide temporary rate cuts.
Tip 15: Negotiate directly with agents. Personalized discussions sometimes reveal unadvertised discounts.
Tip 16: Document all comparisons. Keep a record of quotes, dates, and discount details to support future negotiations.
Conclusion
The auto insurance rate compare process intertwines actuarial science, regulatory frameworks, and consumer behavior. By mastering pricing dynamics, recognizing influential factors, leveraging comparison tools, and avoiding common errors, drivers can secure optimal coverage at the most competitive price.
Continual vigilance and strategic application of the presented tips will ensure that future premium decisions remain both financially prudent and fully protective, keeping vehicles and drivers safeguarded on the road ahead.

