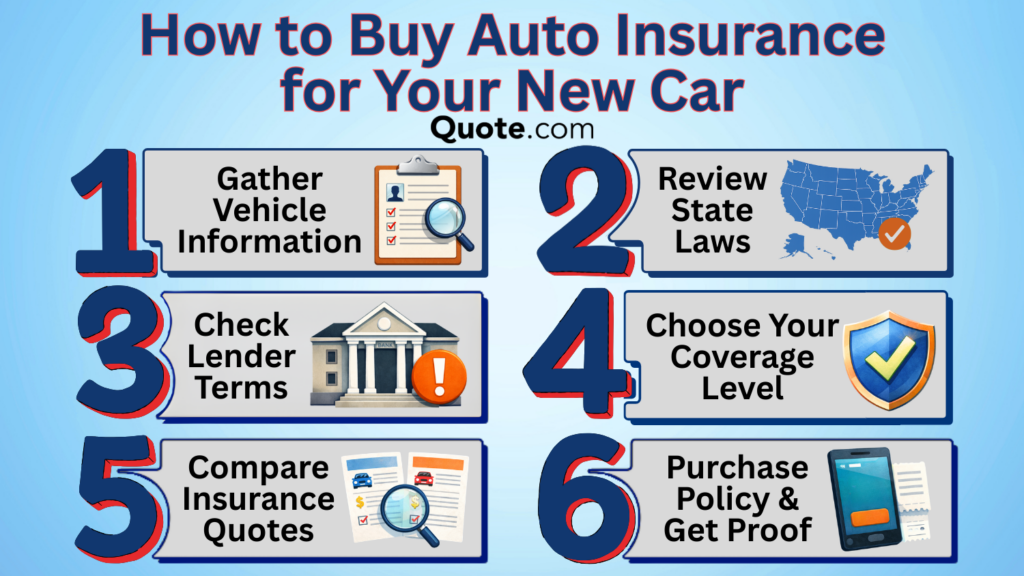
auto insurance for new cars protects the financial interests of owners when a recently purchased vehicle is involved in an accident, theft, or natural disaster; for example, a 2024 Honda Civic bought from a dealership can be covered by a policy that reimburses repair costs after a collision.
The importance of this coverage stems from the higher value and financing structures typical of new automobiles; lenders often require comprehensive protection, and modern safety features can affect premium calculations. Historically, auto insurance evolved alongside mass automobile adoption, and today sophisticated underwriting reflects both vehicle technology and driver behavior.
This article examines pricing dynamics, coverage options, discounts, claims handling, regulatory considerations, and common mistakes, providing a roadmap for selecting optimal protection for a brand‑new car.
1. Pricing dynamics
- Base premium
The foundational cost set by insurers reflects actuarial data; a driver in Ohio might see a base premium of $1,200 annually for a new sedan.
- Vehicle depreciation
New cars lose value quickly, and insurers adjust rates to mirror this decline; a 2025 Toyota Corolla may drop 15% in the first year, influencing premium reductions.
- Driving profile
Telematics data on speed, braking, and mileage can lower rates for cautious drivers; a fleet driver with a clean record may qualify for a 10% discount.
- Location risk
Urban areas with higher traffic density typically incur higher premiums; a downtown Los Angeles resident often pays more than a suburban counterpart.
2. Coverage options
- Liability
Mandatory in most states, liability covers injury and property damage to third parties; a crash involving a new SUV that injures a pedestrian triggers this coverage.
- Collision
Collision pays for repairs to the insured vehicle after an accident, regardless of fault; a new electric car struck by a delivery truck would be repaired under this provision.
- Comprehensive
Comprehensive addresses non‑collision events such as theft, fire, or hail; a hailstorm denting the roof of a freshly painted coupe would be covered.
- Gap coverage
Gap bridges the difference between the car’s actual cash value and the remaining loan balance; if a financed 2024 SUV is totaled, gap coverage prevents the owner from owing the lender.
3. auto insurance for new cars
When selecting a policy for a newly purchased vehicle, the balance between cost and protection is crucial. New cars often feature advanced driver‑assist systems that can qualify for reduced premiums, yet the higher replacement cost demands robust coverage limits.
Insurers may also offer manufacturer‑specific programs; for instance, a partnership between an automaker and an insurer can provide bundled coverage that includes roadside assistance and loan‑payoff protection.
4. Discount opportunities
- Multi‑policy
Bundling auto with homeowners or renters insurance frequently yields a 15% reduction; a homeowner insuring a new family car can leverage this saving.
- Safe driver
Drivers with no accidents or violations for three consecutive years often receive a safe‑driver discount, sometimes exceeding 10%.
- Telematics
Usage‑based programs that monitor mileage and driving habits can cut premiums for low‑usage owners; a commuter driving 5,000 miles annually may see a notable discount.
- Dealer incentives
Dealerships sometimes negotiate group rates with carriers, offering immediate discounts at the point of sale; a regional dealership network may present a 5% off policy for all new car buyers.
5. Claims process
Initiating a claim for a new vehicle typically begins with notifying the insurer within a specified window, often 24‑48 hours after an incident. Documentation such as police reports, photos, and repair estimates accelerates the assessment.
Many insurers assign a dedicated claims adjuster who coordinates with certified repair shops; for a brand‑new luxury sedan, the adjuster may recommend a factory‑authorized service center to preserve warranty coverage.
Prompt settlement is essential to avoid loan default; some policies include a rental‑car reimbursement clause, ensuring mobility while the new car is repaired.
6. State regulations
Regulatory requirements vary widely; some states mandate minimum liability limits of $25,000 per person, while others enforce higher thresholds for new vehicles. Additionally, certain jurisdictions require uninsured‑motorist coverage as a default component.
Compliance with state‑specific disclosure rules ensures that policyholders understand exclusions; for example, a state may prohibit insurers from excluding flood damage in coastal regions.
Staying informed about legislative changes, such as proposed increases in mandatory coverage limits, helps owners adjust their policies before renewal periods.
7. Common pitfalls
Underinsuring a new car is a frequent error; selecting limits based on the vehicle’s original MSRP rather than its current market value can leave gaps after depreciation.
Neglecting to review discount eligibility each year can erode savings; a driver who upgrades to a safer vehicle may qualify for additional reductions that go unnoticed.
Failing to read fine print regarding exclusions—such as aftermarket modifications or rideshare usage—can result in denied claims when those scenarios arise.
Frequently Asked Questions
Below are concise answers to common queries about protecting a newly purchased vehicle.
Question 1: How does financing affect required coverage?
Lenders typically require comprehensive and collision coverage until the loan is paid off, ensuring the vehicle’s value is protected against total loss or damage.
Question 2: Are there special rates for electric vehicles?
Many insurers offer discounts for electric cars due to lower fire risk and advanced safety features, though premium calculations may also consider higher repair costs for battery components.
Question 3: What is the role of gap insurance?
Gap insurance covers the difference between the insurer’s payout based on actual cash value and the outstanding loan balance, preventing the owner from owing money after a total loss.
Question 4: Can telematics lower premiums for a new car?
Usage‑based programs that track mileage and driving behavior often reward low‑risk drivers with reduced rates, making them attractive for owners of low‑usage new vehicles.
Question 5: How often should coverage limits be reviewed?
Reviewing limits annually or after major life events—such as a salary increase or home purchase—ensures that protection remains adequate and cost‑effective.
Question 6: Do dealer‑offered insurance plans provide better value?
Dealer partnerships can bundle services and offer convenience, but independent market comparison is advisable to confirm that premiums and coverage features are competitive.
Tips
Implementing these strategies can optimize protection for a new vehicle.
Tip 1: Compare multiple quotes. Gathering estimates from at least three insurers reveals pricing variations and coverage nuances.
Tip 2: Verify discount eligibility. Check for multi‑policy, safe‑driver, and telematics discounts each renewal cycle.
Tip 3: Choose reputable repair networks. Selecting certified shops preserves warranty and ensures quality workmanship.
Tip 4: Review policy limits annually. Adjust coverage to reflect changes in vehicle value and personal financial circumstances.
Tip 5: Understand exclusions. Read fine print for clauses that may affect claims involving aftermarket parts or rideshare usage.
Tip 6: Activate roadside assistance. Adding this service provides peace of mind for unexpected breakdowns.
Tip 7: Maintain a clean driving record. Consistently safe driving reduces risk scores and premium costs.
Tip 8: Utilize usage‑based programs. Install telematics devices if driving habits align with lower‑risk profiles.
Tip 9: Consider gap coverage early. Secure gap insurance at purchase to avoid coverage gaps if a total loss occurs.
Tip 10: Keep documentation organized. Store photos, receipts, and police reports for swift claim processing.
Tip 11: Evaluate deductible levels. Higher deductibles lower premiums but require out‑of‑pocket readiness.
Tip 12: Monitor legislative updates. Stay informed about state law changes that may affect minimum coverage requirements.
Tip 13: Reassess after major life events. Marriage, relocation, or a new job can influence risk assessments and discount opportunities.
Conclusion
The examined pricing structures, coverage choices, discount mechanisms, claims procedures, regulatory environments, and typical mistakes together form a comprehensive framework for selecting auto insurance for new cars. By applying the outlined considerations, drivers can align protection levels with financial goals and vehicle value.
Future developments in vehicle technology and insurance analytics promise even more personalized policies, encouraging proactive engagement with coverage decisions for each new automobile acquisition.

