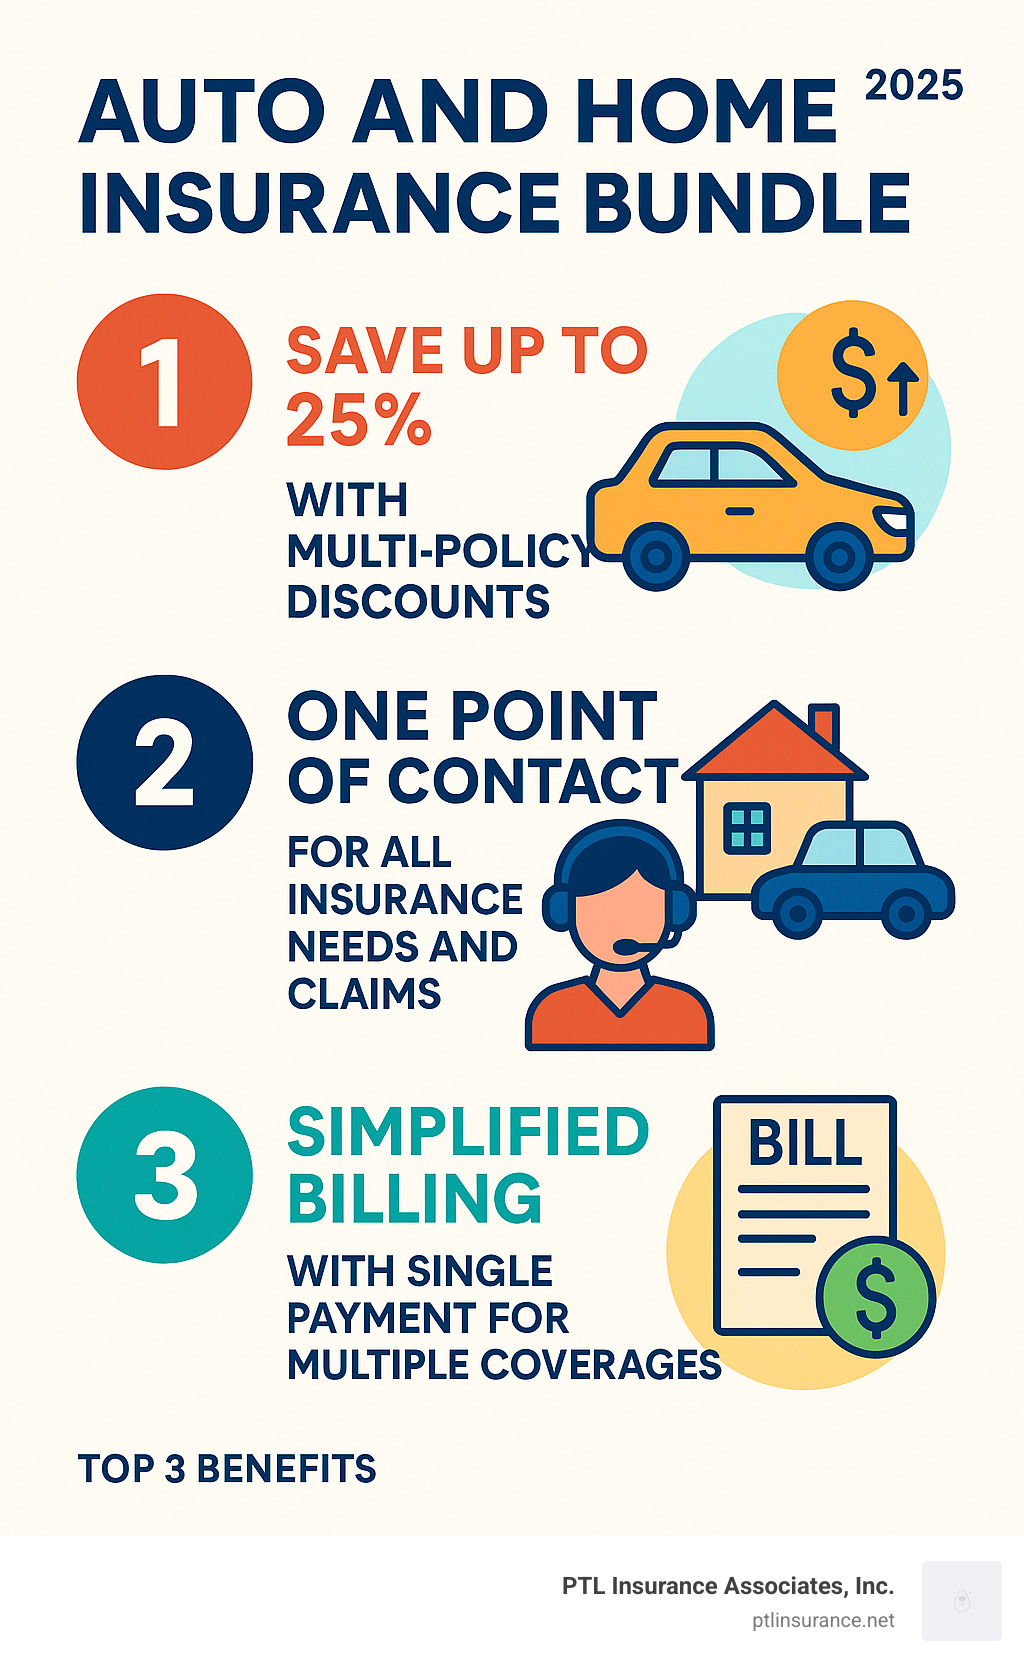
Auto home life insurance combines automobile, homeowners, and life policies into a single, streamlined package for comprehensive protection.
Bundling these three core coverages reduces administrative overhead, often yields multi‑policy discounts, and provides a unified risk management strategy that aligns with long‑term financial planning.
The following sections explore definition, pricing, coverage nuances, pitfalls, discounts, claims handling, and emerging trends, offering a complete roadmap for informed decision‑making.
1. Understanding auto home life insurance
This bundled offering integrates vehicle liability, property damage, and mortality coverage under one contractual umbrella. For example, a family in Ohio might purchase a combined policy that shields their sedan, primary residence, and provides a term life benefit for the breadwinner.
Key advantages include simplified billing, coordinated deductible structures, and the potential for loyalty discounts that exceed the sum of separate policies. Insurers also gain a holistic view of risk, enabling more accurate underwriting.
Regulatory frameworks vary by state, yet most jurisdictions permit multi‑line products as long as each component meets its specific statutory requirements.
2. Pricing dynamics
- Risk aggregation
Insurers assess the combined probability of loss across auto, home, and life lines. A lower aggregate risk often translates into reduced premium coefficients, especially for low‑claim households.
- Discount layering
Multi‑policy discounts can stack with safe‑driver, claims‑free, and home‑security rebates, producing cumulative savings that may reach 20 % of the total premium.
- Geographic weighting
Regions with lower accident rates or reduced natural‑disaster exposure receive favorable pricing adjustments, influencing the bundled rate more than isolated policies.
- Credit‑based underwriting
Many carriers incorporate credit scores into premium calculations; a strong credit profile can further lower the bundled cost.
Understanding how these factors interact helps consumers forecast budget impacts and negotiate optimal terms.
3. Coverage comparisons
When evaluating a bundled solution, compare the sum of individual coverages against the bundled offering. Look for equivalent liability limits, dwelling replacement cost, and death benefit amounts.
Pay attention to exclusions that may appear only in the bundle, such as limited coverage for high‑value collectibles or reduced roadside assistance tiers.
Side‑by‑side tables often reveal that bundled policies maintain parity while delivering administrative convenience.
4. Common pitfalls
- Over‑bundling
Purchasing a bundle without assessing actual needs can lead to paying for unnecessary coverage, such as excessive life insurance for a single‑income household.
- Inflexible adjustments
Changing one component—like upgrading a vehicle—may trigger premium recalculations across the entire bundle, complicating budgeting.
- Hidden deductibles
Some insurers apply a single deductible to multiple claims, potentially increasing out‑of‑pocket exposure during simultaneous events.
- Policy renewal mismatches
Renewal dates that are not synchronized can cause coverage gaps or double‑billing periods.
Avoiding these traps requires periodic policy audits and clear communication with the insurer.
5. Discount opportunities
- Safety device incentives
Installing anti‑theft alarms, smoke detectors, or advanced driver‑assistance systems often unlock additional premium cuts within the bundle.
- Loyalty rewards
Long‑term customers may qualify for tiered loyalty discounts that apply across all three lines.
- Paperless billing
Opting for electronic statements can shave a few percent off the total premium, reflecting reduced processing costs.
- Bundled deductible reduction
Negotiating a shared deductible lower than the sum of individual deductibles can yield savings on claim settlements.
Proactively requesting these incentives at renewal maximizes financial efficiency.
6. Claim process overview
Bundled policies typically employ a single claims portal, allowing policyholders to submit auto, property, or life claims through one interface. This centralization accelerates case assignment and reduces paperwork duplication.
However, claim adjusters must differentiate loss types; an auto collision may trigger a separate investigation from a home water intrusion, even within the same ticket.
Timely documentation—photos, police reports, and medical records—remains essential to avoid claim denial across any line.
7. Future trends
Telematics and smart‑home data are reshaping risk assessment, enabling dynamic premium adjustments based on real‑time driving behavior and property sensor alerts.
Artificial intelligence‑driven underwriting promises more granular bundling options, allowing consumers to tailor coverage percentages for each line without purchasing full‑scale policies.
Regulators are monitoring these innovations to ensure transparency and consumer protection as the market evolves.
Frequently Asked Questions
Below are concise answers to common inquiries about auto home life insurance.
Question 1: How does bundling affect overall premium cost?
Bundling typically reduces total premium by 10 % to 20 % through multi‑policy discounts, shared administrative fees, and risk aggregation benefits, though exact savings depend on individual risk profiles and insurer policies.
Question 2: Are coverage limits the same as purchasing separate policies?
Most carriers maintain equivalent limits across bundled and standalone policies; however, consumers should verify that liability, dwelling, and death benefit amounts match their specific needs.
Question 3: Can a policyholder modify one line without affecting the others?
Adjustments to a single line often trigger a review of the entire bundle, potentially altering premiums or deductible structures; insurers may require a full‑policy recalculation.
Question 4: What documentation is required for a life insurance claim within a bundle?
Standard documentation includes a certified death certificate, proof of identity, and any beneficiary designations; the bundled process consolidates these with auto and home claim files for streamlined handling.
Question 5: Do discounts for safety devices apply to all three lines?
Safety‑related discounts usually apply to the specific line they protect—such as anti‑theft alarms for home or advanced driver‑assistance for auto—but many insurers extend a cumulative discount across the bundle.
Question 6: How often should the bundled policy be reviewed?
Annual reviews are recommended to account for life changes, vehicle upgrades, home renovations, and evolving risk factors, ensuring the bundle remains cost‑effective and adequately protective.
Tips
Below are sixteen actionable recommendations for maximizing the value of an auto home life insurance bundle.
Tip 1: Conduct an annual needs assessment. Reevaluate coverage amounts to align with current assets and family circumstances.
Tip 2: Leverage telematics data. Share safe‑driving metrics with the insurer to qualify for usage‑based discounts.
Tip 3: Install certified safety devices. Use approved alarms and sensors to unlock additional premium reductions.
Tip 4: Synchronize renewal dates. Align policy expiration to avoid coverage gaps and simplify payment schedules.
Tip 5: Opt for electronic statements. Reduce processing fees by selecting paperless billing options.
Tip 6: Review deductible structures. Choose a shared deductible that balances out‑of‑pocket costs with premium savings.
Tip 7: Maintain detailed claim records. Preserve photos, receipts, and reports to expedite any future settlements.
Tip 8: Verify exclusion clauses. Ensure the bundle does not omit critical coverages needed for high‑value items.
Tip 9: Update beneficiary designations. Keep life‑insurance beneficiaries current after major life events.
Tip 10: Explore loyalty programs. Inquire about tiered rewards for long‑term policyholders.
Tip 11: Negotiate bundle discounts. Request a review of all applicable multi‑policy incentives at renewal.
Tip 12: Assess credit impact. Maintain a strong credit score to benefit from credit‑based underwriting reductions.
Tip 13: Compare carrier ratings. Choose insurers with high financial strength and customer satisfaction scores.
Tip 14: Utilize a single claims portal. Consolidate reporting to reduce administrative effort.
Tip 15: Monitor regulatory changes. Stay informed about state‑level insurance reforms that may affect bundled products.
Tip 16: Seek professional advice. Consult a licensed insurance advisor to tailor the bundle to unique risk profiles.
conclusion
The preceding sections have detailed definition, pricing mechanisms, coverage considerations, common errors, discount strategies, claims handling, and future developments surrounding auto home life insurance. By applying the outlined best practices, consumers can achieve comprehensive protection while optimizing cost efficiency.
Continued awareness of market innovations and periodic policy reviews will ensure that bundled coverage remains aligned with evolving personal and financial goals.

