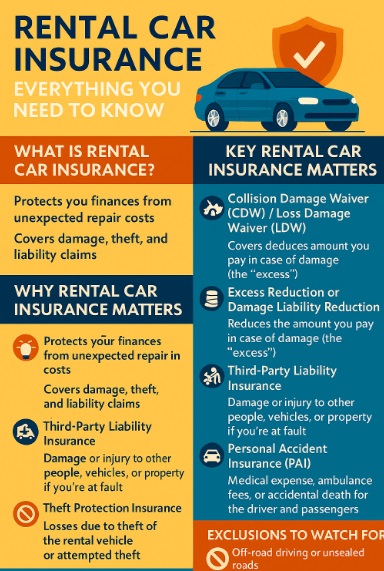
Auto and tenant insurance combines two distinct protection plans—vehicle coverage and renter’s policy—into a cohesive financial safety net for individuals who own a car and lease a dwelling. For example, a young professional driving a compact sedan while renting a city apartment can file a single claim that addresses both a car accident and water damage to personal belongings.
The importance of this dual approach lies in its ability to streamline risk management, reduce administrative overhead, and often qualify for bundled discounts. Historically, insurers recognized overlapping customer bases and began offering combined quotes in the early 2000s, reflecting a practical response to consumer demand for simplicity and cost efficiency.
This article unpacks the fundamentals of auto and tenant insurance, explores pricing dynamics, common pitfalls, coverage nuances, claims processes, legal considerations, and future trends, equipping readers with the knowledge to make informed decisions.
1. Understanding auto and tenant insurance
Grasping the basic structure of each policy clarifies how they intersect. Auto insurance typically includes liability, collision, and comprehensive coverage, while tenant (renter’s) insurance offers personal property protection, liability, and additional living expenses. When combined, insurers may offer a unified deductible and coordinated claims handling, simplifying the experience for policyholders.
2. Pricing dynamics
- Bundling discounts
Insurers often reduce premiums by 10‑15% when both policies are purchased together. A family in Chicago saved $250 annually by bundling their auto and renter’s policies with the same carrier.
- Risk assessment
Underwriters evaluate driving history, location, and claims frequency. High‑risk drivers may see limited savings, highlighting the need to maintain clean records.
- Coverage limits
Choosing higher limits on both policies can increase overall cost but provides stronger protection against catastrophic losses.
- Deductible strategy
Aligning deductibles across policies can lower administrative fees; a $500 deductible on both policies may reduce the combined premium by $30 per year.
- Credit score impact
Many insurers factor credit scores into pricing. Improving a score from 620 to 720 can shave 5‑7% off the total premium.
3. Common mistakes to avoid
Overlooking policy gaps is a frequent error. For instance, some renters assume their landlord’s insurance covers personal belongings, which is rarely true. Another pitfall is under‑insuring vehicle value, leading to inadequate reimbursement after a total loss.
Failing to update policies after major life events—such as moving to a new city or purchasing a higher‑value car—can result in insufficient coverage or higher out‑of‑pocket costs.
4. Coverage nuances
- Liability overlap
Both policies provide liability protection, but auto liability covers bodily injury and property damage caused by the vehicle, whereas renter’s liability covers incidents inside the rental unit. Understanding the distinction prevents duplicate claims.
- Personal property limits
Renter’s policies typically cap personal belongings at $30,000. High‑value items like electronics may require a rider or schedule endorsement.
- Comprehensive auto add‑ons
Roadside assistance, rental reimbursement, and gap coverage can be added to the auto portion, enhancing overall protection.
5. Claims process synergy
When a single event affects both assets—such as a hailstorm damaging a car and flooding a rental unit—having a unified insurer can expedite claim resolution. The adjuster can assess both losses in one visit, reducing duplication of paperwork and speeding up payouts.
Conversely, using separate insurers may lead to conflicting timelines, emphasizing the advantage of a coordinated approach.
6. Legal and regulatory considerations
State mandates differ for auto liability minimums, while renter’s insurance is usually optional but sometimes required by lease agreements. Understanding local requirements prevents inadvertent non‑compliance.
Additionally, some jurisdictions enforce “fair claims” statutes that limit claim denial reasons, offering policyholders greater protection regardless of bundled status.
7. Future trends and technology
Telematics and usage‑based insurance (UBI) are reshaping auto premiums, rewarding low‑mileage drivers with lower rates. Simultaneously, smart home devices are influencing renter’s insurance pricing by reducing fire and theft risk.
Emerging AI‑driven risk models promise more personalized bundles, potentially offering dynamic discounts based on real‑time behavior across both vehicle and home environments.
Frequently Asked Questions
Below are concise answers to the most common queries about auto and tenant insurance.
Question 1: How does bundling auto and tenant insurance affect premiums?
Bundling typically yields a 10‑15% discount on the combined premium, though exact savings depend on the insurer, risk profile, and selected coverage limits. The discount arises from reduced administrative costs and incentivized loyalty.
Question 2: Are personal belongings covered by a landlord’s policy?
No. Landlord insurance protects the building structure, not the tenant’s possessions. Renters need their own policy to cover furniture, electronics, and clothing against theft, fire, or water damage.
Question 3: Can the same deductible apply to both policies?
Many insurers allow a unified deductible, simplifying claim filing and potentially lowering overall fees. Aligning deductibles should be balanced against the risk tolerance of the policyholder.
Question 4: What happens if a hailstorm damages both car and rental unit?
A bundled insurer can process both claims concurrently, often assigning a single adjuster. This coordination reduces paperwork, shortens settlement time, and may result in a combined payout faster than handling separate policies.
Question 5: Does renter’s insurance cover liability for car accidents?
No. Renter’s liability covers incidents occurring within the rented space, such as a guest slipping. Auto liability is distinct and must be covered by the auto policy.
Question 6: Are there credit‑score impacts on combined policies?
Yes. Insurers often use credit scores to determine risk for both auto and renter’s coverage. Improving the score can lower the combined premium by several percent, making credit management a valuable cost‑saving tool.
Tips for Maximizing Auto and Tenant Insurance Benefits
Follow these ten actionable steps to ensure optimal coverage and cost efficiency.
Tip 1: Review policy limits annually. Adjust limits to match lifestyle changes and avoid under‑insurance.
Tip 2: Align deductibles. Choose a consistent deductible across both policies to simplify claims.
Tip 3: Leverage bundling discounts. Ask insurers about combined quotes before renewing separate policies.
Tip 4: Add riders for high‑value items. Schedule jewelry, art, or electronics to guarantee full reimbursement.
Tip 5: Maintain a clean driving record. Lower accident frequency translates to reduced auto premiums.
Tip 6: Upgrade home security. Smart locks and alarms can lower renter’s premiums by demonstrating risk mitigation.
Tip 7: Use telematics wisely. Enroll in usage‑based programs if mileage is low to capture discounts.
Tip 8: Update address promptly. Relocating changes risk exposure; inform insurers to keep coverage accurate.
Tip 9: Compare annual renewal offers. Market rates shift; periodic comparison ensures competitive pricing.
Tip 10: Document belongings. Keep an inventory with photos to expedite claims and prove value.
Conclusion
The interplay of auto and tenant insurance offers a streamlined, cost‑effective way to protect two of the most valuable personal assets. Understanding pricing dynamics, coverage nuances, and claims coordination enables smarter decisions and stronger financial resilience.
As technology continues to personalize risk assessment, staying informed about emerging tools will further enhance the value of combined coverage, ensuring lasting peace of mind for drivers and renters alike.

